
How to Invest in Tomorrow’s Tech Trends Today
We put the question to Jerry Yang co-founder of Yahoo!

By LAUREN R. RUBLIN
Tue, May 11, 2021 3:31pm 3 min
3 min


We put the question to Jerry Yang co-founder of Yahoo!
3 min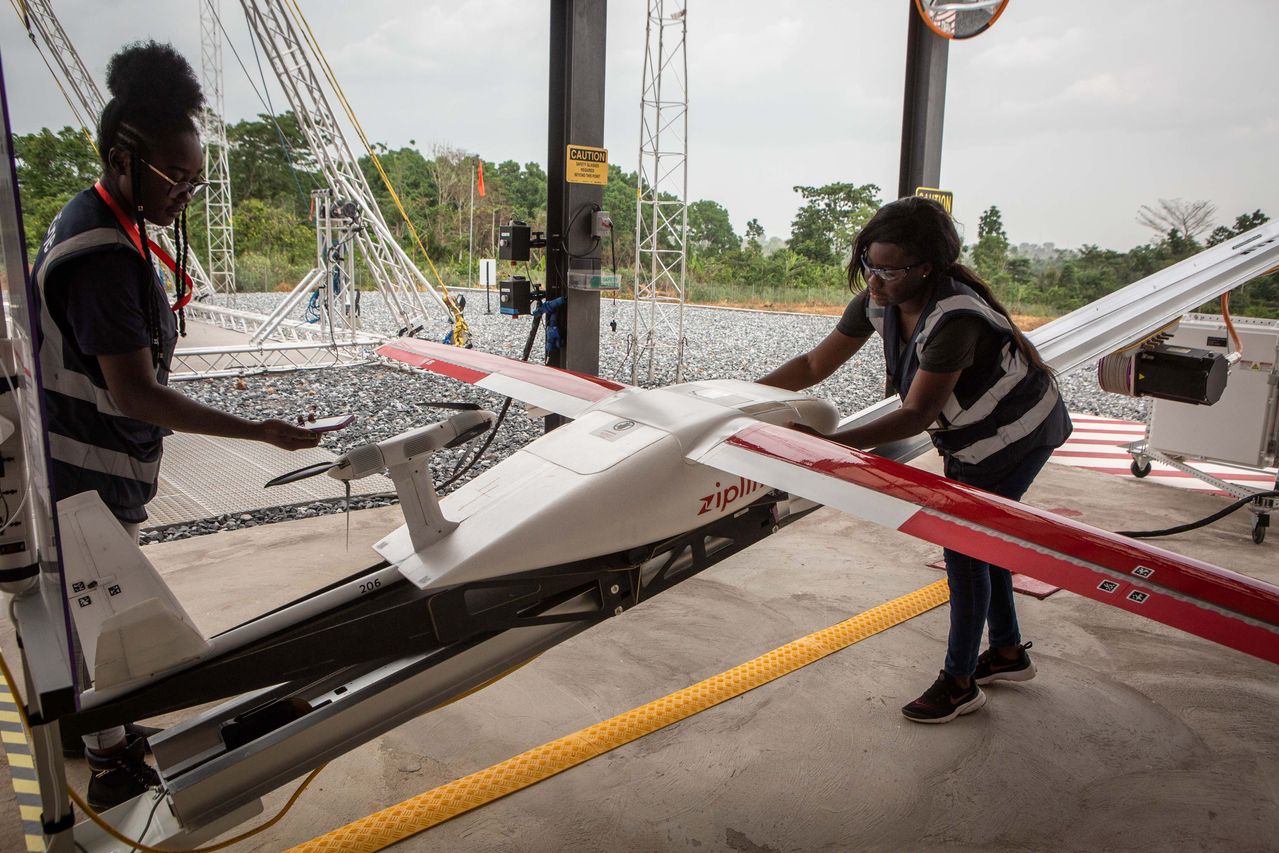
Which companies, public and private, are best-positioned for the next 100 years—or at least the next few years? We put the question to Jerry Yang, founding partner of AME Cloud Ventures and co-founder of Yahoo!, and a member of Barron’s Centennial Roundtable. Yang, a longtime venture capitalist based in Silicon Valley, has seen his share of start-ups and innovations. He highlights some of today’s most promising companies and trends in the edited interview below.
Barron’s: Which companies excite you these days, and why?
Jerry Yang: I’ll start with Zoom Video Communications [ticker: ZM]. Never in a thousand years would we have thought that ‘Zoom’ would become a verb in this context. This company took the opportunity to become massively skilled in the past 15 months. In hindsight, we might say it was easy for them to have done that, but they had to overcome a lot of privacy and scale issues. They really matured in a hurry. The future for video is huge. How do we enhance it? How do we make video more intelligent and productive?
Will the future belong to Zoom or a host of competitors?
From the big competitors to start-ups, everyone is emulating or attempting to catch up to Zoom’s capabilities. Zoom has announced a platform marketplace for applications. It is adding more intelligence to its platform, and more productivity tools. In my view, by launching an app store of sorts, Zoom can create an ecosystem that is a defensible barrier to competition.
Zipline, an on-demand delivery service, is another company to watch. It operates fixed-wing drones that carry a few kilograms of payload. They can fly 160 kilometres round trip. When they reach their destination, they drop an insulated package with a parachute. Zipline was founded in Silicon Valley, but its first scaled deployment is medical supply in Rwanda, Africa. Zipline delivers blood supplies and critical medicines. It continues to scale. It is an incredibly exciting company.
Do you expect Zipline to go public in the next few years?
That’s a good question. Companies are raising as much money now in private funding rounds as they would have in an initial public offering. IPOs help with branding and maybe create a new investor base, but if a company just needs capital, there is plenty in the private market. From 2012 to 2015 or ’16, there were few companies coming public. The IPO market goes in cycles. With today’s abundance of low-cost capital, private companies can take risks and have the money to grow.
What other industries or companies look promising to you?
In the area of artificial intelligence and drug discovery, we invested in Recursion Pharmaceuticals [RXRX], which went public in April. Recursion is based in Salt Lake City, which has become a hotbed for biotech start-ups. The company uses massive data computational tools, lab robotics, and a petabyte-level database to speed up the drug-discovery process. Zymergen [ZY] also operates in an area I’m pretty excited about—biofacturing. This is a materials manufacturing company, using AI, automation, and biology for scale manufacturing.
How does biology fit into the equation?
Instead of using chemicals, for instance, they’re using yeast fermentation to make new materials and products—from new electronic displays to naturally derived bug repellents. Ginkgo Bioworks is another biofacturing company I’m excited about. More broadly, the birth of genetic sequencing launched a whole industry that’s exciting, including gene editing. Synthetic biology is at an early stage, but we’re already starting to see companies come to fruition, such as Twist Bioscience [TWST], which manufactures and sells synthetic DNA-based products. The world will need more of these technologies in coming years. Ten years ago, we hadn’t “printed” a single gene. Now we’re printing tens of millions, and that will go to billions in the next few years.
What other technologies should we be watching?
I’ll emphasize a couple of trends. We’re moving into a world where cameras will be smarter. Whether cameras are manned by Zoom apps or cars or your watch, they will be equipped with more sensors, and the sensors will get smarter. That means more data will be fed into the cloud. We’re also seeing huge investments in natural-language processing. A lot of theoretical work was done in this area, and now we’re starting to see practical applications. All of this means the cloud is getting smarter. We’re going to need a lot more bandwidth. If we build bandwidth, the applications will come. Sensors and devices will be communicating with each other, without human intervention. That’s another massive source of new data that will come online.
The idea of using biomaterials in sensors is still in the research lab, but it’s something to watch. Sensors made of carbon, instead of silicon, could be much more responsive to an individual’s biology.
We haven’t talked about longevity. Science tells us the average life span for today’s teenagers could be well beyond 100.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
