
The Office Market Had It Hard in 2023. Next Year Looks Worse.
Office building owners are losing hope that occupancy rates will rebound soon

By PETER GRANT
Wed, Dec 20, 2023 8:58am 4 min
4 min


Office building owners are losing hope that occupancy rates will rebound soon
4 min
Office building owners, hammered by falling demand and high interest rates, struggled in 2023. But they mostly managed to stay afloat.
That is going to be a lot harder to do next year.
Many landlords have been able to extend their loans, often by putting in more capital. But a lot of those extensions are now expiring, and owners are losing hope that occupancy rates will rebound soon.
That means many more office landlords will be compelled to pay off their mortgages, sell their properties at a steep discount or hand their buildings over to their creditors.
“In 2024, it’s game time,” said Scott Rechler, chief executive of RXR Realty, a major owner of office buildings in the New York region. “Owners and lenders are going to have to come to terms as to where values are, where debt needs to be and right-sizing capital structures for these buildings to be successful.”
Office demand shows no sign of returning to pre pandemic levels. While the number of full-time remote employees has dwindled, hybrid workplace policies look here to stay. In the fourth quarter, 62% of U.S. businesses allowed employees to work from home some days of the week, up from 51% in the first quarter, according to Scoop Technologies.
Return-to-office rates also stalled for most of 2023. Kastle Systems, which tracks security-card swipes in 10 major U.S. cities, said that average office attendance is about half of its pre pandemic level. Placer.ai, which tracks mobile phone data, puts it in the 60% to 65% range. But it also said the return rate has topped out.
The office market has shown “some monthly fluctuations but little real change in the overall trajectory,” Placer.ai said in a November report.
The U.S. office vacancy rate stands at a record 13.6%, up from 9.4% at the end of 2019, according to data firm CoStar Group. The firm is forecasting it will rise to 15.7% by the end of 2024 and will peak above 17% by the end of 2026.
That vacancy rate is poised to push higher because nearly half of office leases signed before the pandemic haven’t expired, CoStar said. When they do, many of the businesses will likely take less space than they are currently occupying, whether they are renewing or relocating.
Take the case of Chicago law firm Neal Gerber Eisenberg, which signed one of the city’s largest 2023 office leases earlier this fall. The firm, which has grown steadily throughout the pandemic, adopted a policy that requires employees to work from the office at least eight days a month. Neal Gerber leased 90,000 square feet at its new location, down from the 113,000 square feet it will be giving up.
Beyond the longer-term decline in demand, office landlords are still contending with high interest rates. Landlords that have to refinance debt borrowed when rates were at historic lows will face much higher borrowing costs as high vacancy is putting rents and incomes under pressure.
In recent weeks, inflation has been declining and the Federal Reserve is likely to ease interest rates in 2024. That will soften the blow. But landlords still face a financial squeeze, analysts say.
“If you have a mortgage that’s expiring at 3% or 4%, there’s no way you’re refinancing at 3% or 4%,” said Steve Sakwa, an analyst with Evercore ISI. Even though rates have come down, he added, property owners are still looking at rates that could be double their expiring rates to refinance.
Not all the signals are bleak for the office market in 2024. Demand is still strong for the highest quality and best-located space in many markets from tenants willing to pay high rents to encourage employees to return to offices.
Developers have retreated from new construction in the sector, so there’s little competition from new supply. The 30 million square feet in office construction starts in 2023 was the lowest amount since 2010, according to CoStar.
Cities such as San Francisco, New York and Boston are lowering costs and streamlining the process for converting obsolete office buildings into apartments. While this isn’t expected to result in a big decline in vacancy, the actions might bring more activity to business districts, giving a psychological boost to downtown landlords and businesses.
But the steadily rising number of owners who are defaulting on their mortgages because of falling rent rolls looms over the market. The delinquency rate of bank loans and loans converted into commercial mortgage-backed securities currently is over 6% compared with below 1% before the pandemic hit, according to data firm Trepp.
High delinquencies combined with the dismal office outlook already have convinced some owners to hand properties back to lenders or sell for sharply discounted prices.
In Stamford, Conn., the owner of One Stamford Forum, a 500,000-square-foot building whose tenants include troubled Purdue Pharma, this fall gave the building back to its creditors, according to Trepp. In San Francisco, buyers have purchased office buildings like 60 Spear Street and 350 California Street for fractions of what they were worth before the pandemic.
Trepp is projecting that the office delinquency rate could be over 8% by the second half of next year. As more landlords default, the new owners that replace them—buying in at greatly reduced prices—will likely put more pressure on the market because they’ll be able to charge lower rents and still make a profit.
“What could be catastrophic is if you start seeing corporate profit pressures leading to continued or accelerated pace of office downsizing,” said Stephen Buschbom, Trepp’s research director.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
3 min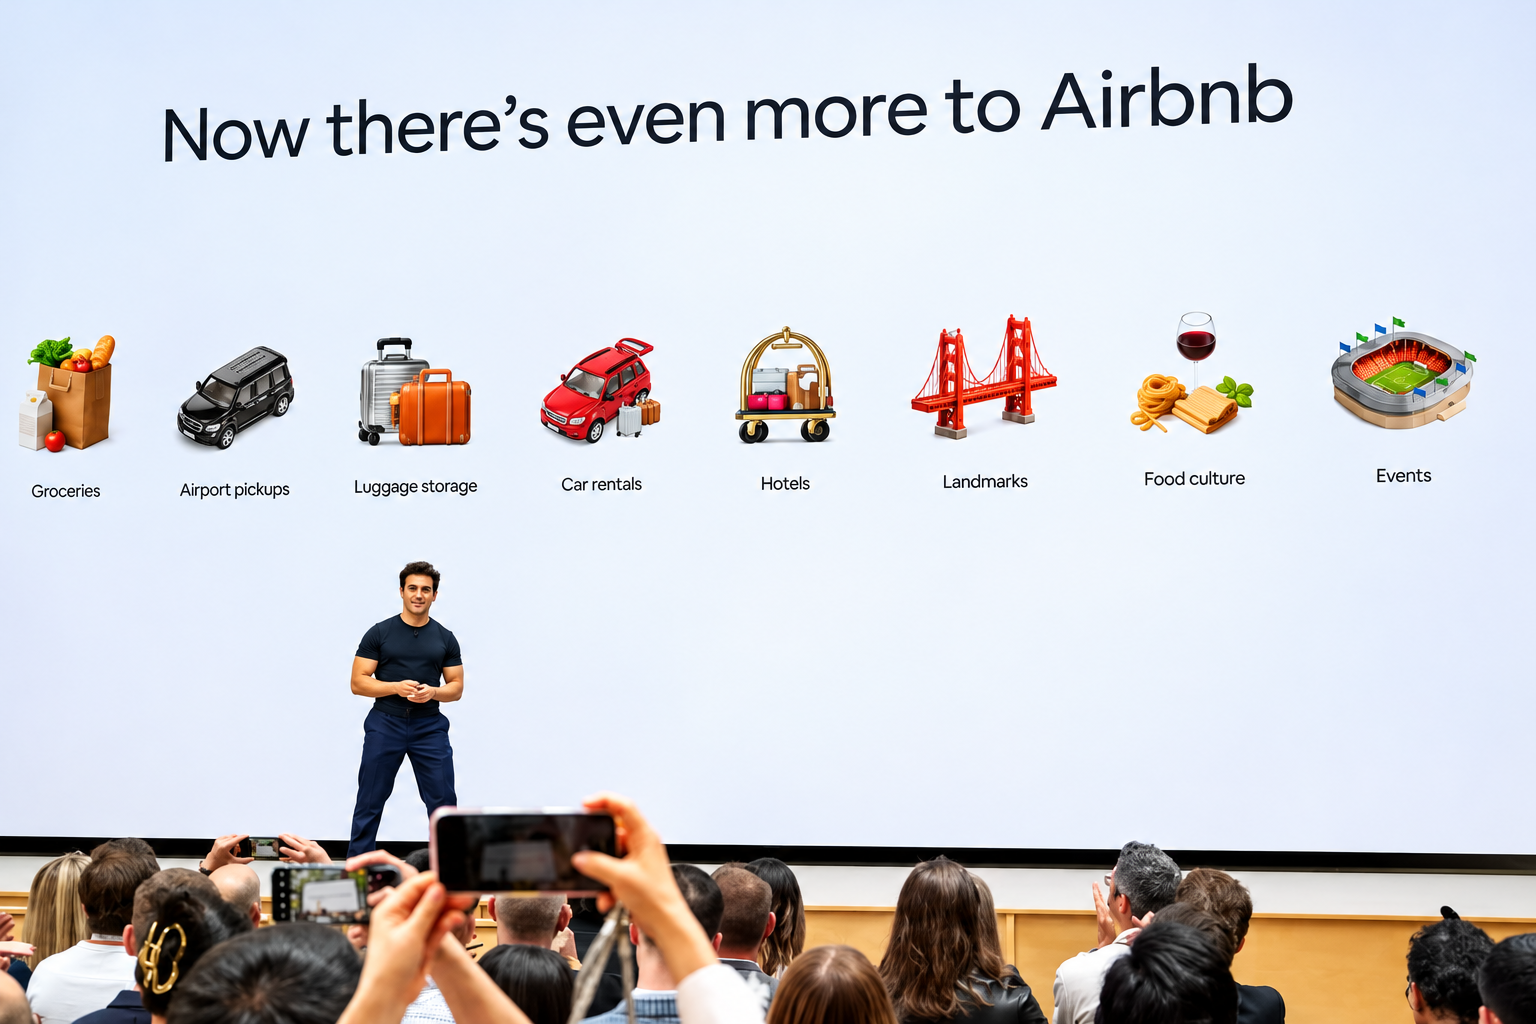
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.
