
The $65 Million Perk for CEOs: Personal Use of the Corporate Jet Has Soared
Company spending on the benefit has climbed 50% since before the pandemic

By THEO FRANCIS
Wed, Jan 17, 2024 9:25am 5 min
5 min


Company spending on the benefit has climbed 50% since before the pandemic
5 min
One of the flashiest executive perks has roared back since the onset of the pandemic: free personal travel on the company jet.
Companies in the S&P 500 spent $65 million for executives to use corporate jets for personal travel in 2022, up about 50% from prepandemic levels three years earlier, a Wall Street Journal analysis found. Early signs suggest the trend continued last year.
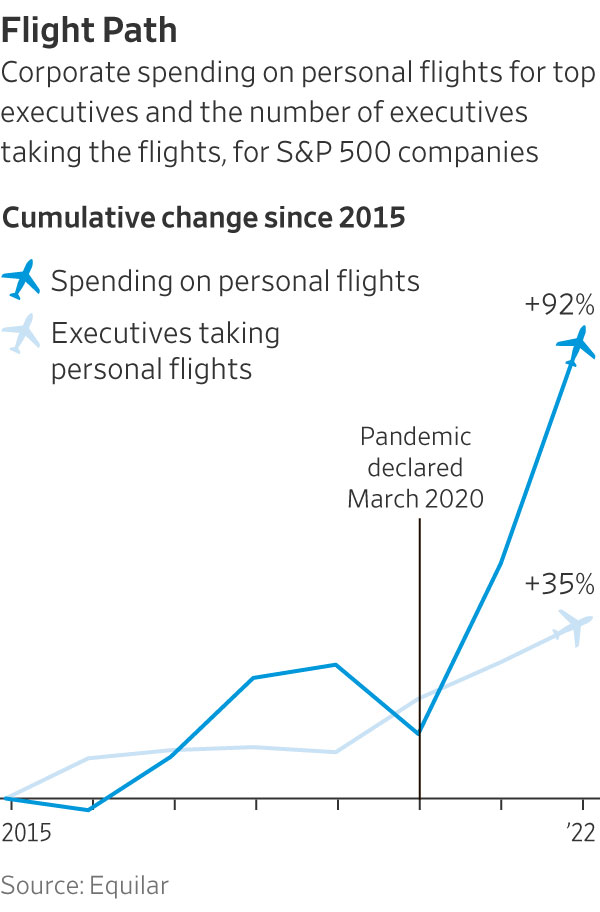
Overall, the number of big companies providing the perk rose about 14% since 2019, to 216 in 2022, figures from executive-data firmEquilar show. The number of executives receiving free flights grew nearly 25%, to 427.
Most companies report executive pay and perks in the spring.
Meta Platforms spent $6.6 million in 2022 on personal flights for Chief Executive Mark Zuckerberg and his then-lieutenant, Sheryl Sandberg—up about 55% from 2019, the Journal found. Casino company Las Vegas Sands spent $3.2 million on flights for four executives, more than double its annual expense in any year since 2015. Exelon, which owns Chicago’s Commonwealth Edison utility, more than tripled its spending on the perk since 2019.
Company jets have long symbolised corporate success and, to critics, excess. Companies typically say flying corporate is safer, healthier and more efficient. Some companies—including Cardinal Health, Raymond James Financial and Hormel Foods—added or expanded the perk in 2020 or 2021, citing pandemic health and safety concerns. Most spending growth came at companies already paying for personal flights in 2019.
Palo Alto Networks began subsidising personal flights for CEO Nikesh Arora in the year ended July 2022, spending about $650,000. Thattotal rose to $1.8 million in its most recent fiscal year, plus a further $286,000 to cover his tax bill for the perk, the cybersecurity company said in an October securities filing.
The company said in filings that its board requires Arora to fly corporate in response to a security consultant’s report. “There was a bona fide, business-related security concern for Mr. Arora and credible threat actors existed with both the willingness and resources necessary for conducting an attack on Mr. Arora,” it said.
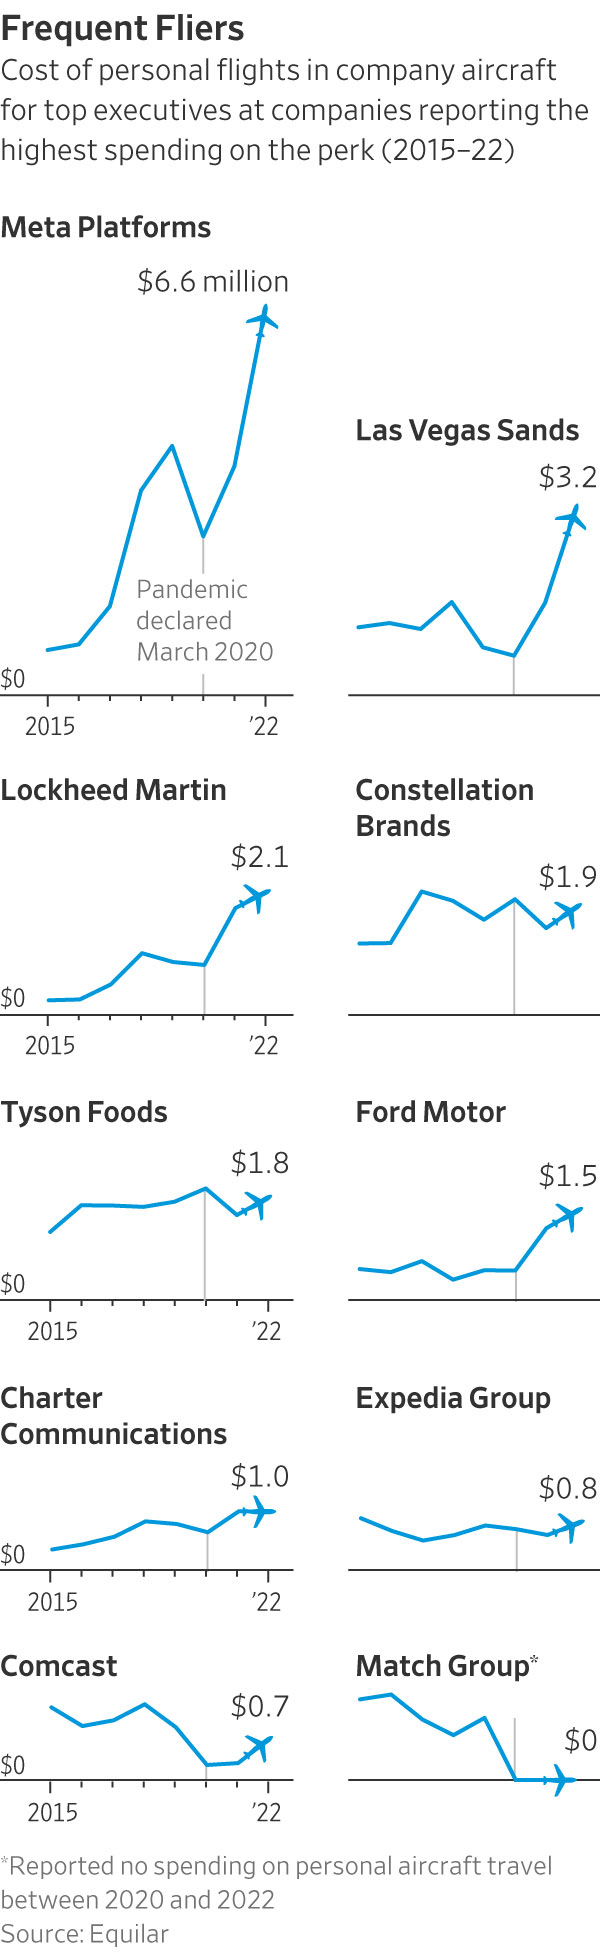
Companies report spending on flights they can’t classify as business-related, including trips to board meetings for other companies or commuting from distant residences. Some give executives a fixed personal-flight allowance in hours or dollars, and require reimbursement beyond that.
The sums have little financial impact on most giant corporations, even when annual flight bills exceed a million dollars. Critics say the free flights indicate directors too eager to please top executives.
“The vast majority of S&P 500 companies do not offer this perk,” said Rosanna Landis Weaver, an executive-pay analyst at As You Sow, a nonprofit shareholder-advocacy group that has produced annual lists of CEOs it considers overpaid.
The Journal’s analysis reflects what companies disclose in securities filings, typically in footnotes to annual proxy statements. Federal rules generally require companies to itemise the perk for each top executive if it costs the company $25,000 or more in a year.
PepsiCo spent $776,000 on personal flights for five executives in 2022, double what it paid for the perk in 2019. Two-thirds of the spending subsidised flights by CEO Ramon Laguarta, who is required to use company aircraft for personal flights for safety and efficiency reasons. In an interview last spring, Laguarta said he sometimes ended business trips to Europe by flying to visit his mother in his native Barcelona. She died later in the year, in her 90s.
A PepsiCo spokesman said the company jet allows executives to reach remote facilities.
Personal jet use can draw investor and regulatory scrutiny. It contributed to the ouster of Credit Suisse’s chairman in 2022.
In June, tool maker Stanley Black & Decker settled Securities and Exchange Commission charges that it failed to disclose $1.3 million in perks for four executives and a director, mostly their use of company aircraft, from 2017 through 2020. In 2020, Hilton Worldwide Holdings settled SEC charges that it didn’t disclose $1.7 million in perks over four years, in part by underreporting costs for CEO Christopher Nassetta’s personal flights by 87%in two of those years. Hilton paid a $600,000 penalty.
Both companies settled without admitting or denying wrongdoing.
Stanley Black & Decker said it raised the errors with the SEC and settled without a fine. In 2022, Stanley Black & Decker reported spending nearly $143,500 on personal flights for former CEO James Loree and his successor, Donald Allan Jr., primarily to fly to outside board meetings or from second homes to work.
Hilton cited higher fuel prices in reporting about $500,000 in flights for Nassetta in 2022.
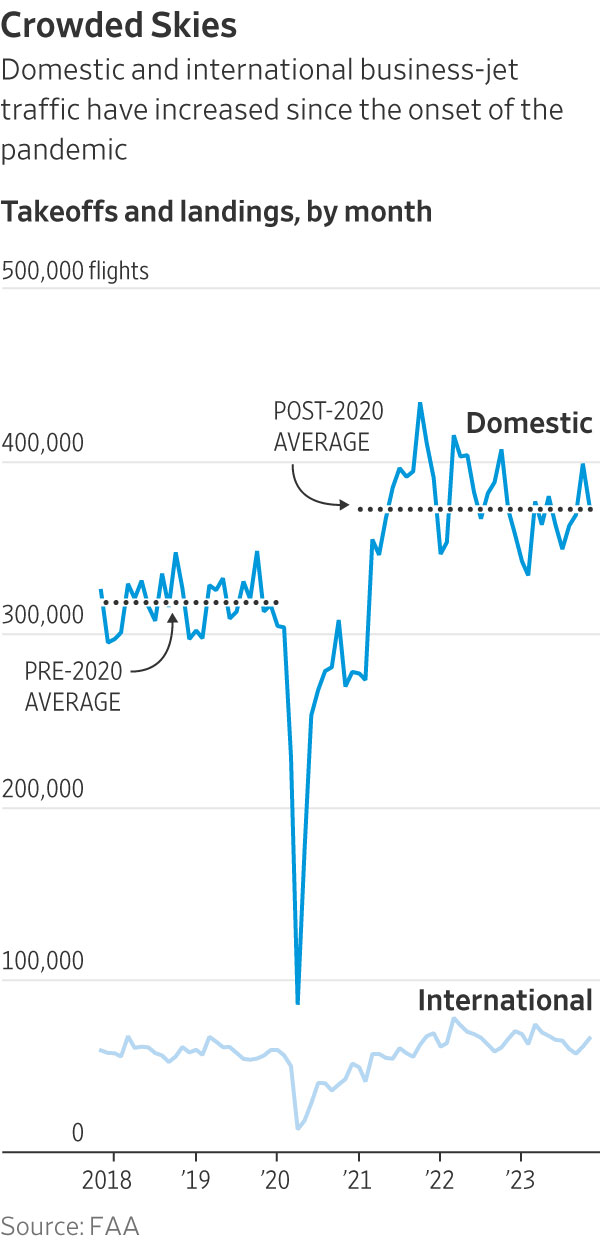
Spending on executives’ personal travel outpaced overall growth in business-jet traffic. Takeoffs and landings are up by about 19% since 2019, after dropping sharply in 2020, Federal Aviation Administration data show. Corporate spending on the perk rose 52%, the Journal found.
Higher fuel costs in 2022 contributed to the increase in spending, and there is little indication of a slowdown last year. Of the 15 S&P 500 companies that have reported spending on the perk in fiscal years ended in the second half of 2023, 10 said they increased spending, including three that didn’t report the perk a year earlier, securities filings show.
Sixteen companies that started paying for personal flights during the pandemic have since stopped. An additional 31 continued spending into 2022, with a median of $124,000. Accenture, Palo Alto Networks and concert promoter Live Nation Entertainment reported spending more than $500,000 apiece.
In 2020, Julie Sweet’s first full year as CEO, Accenture capped annual spending for her personal flights at $200,000, then doubled it the next year. Accenture raised the cap to $600,000 in its year that ended Aug. 31, when it spent about $575,000 on Sweet’s personal flights, the company said in a December securities filing.
In its filings, Accenture said it encourages Sweet to use company aircraft for personal travel, citing a security study the company commissioned.
Companies that provided the perk already in 2019 accounted for most of the recent growth in spending, the Journal found.
Meta, for example, spent nearly $11 million on Zuckerberg and Sandberg’s personal flights from 2015 through 2019, and a further $13.3 million over the next three years. Zuckerberg’s company-paid travel included trips on an aircraft he owns, which Meta charters for business, paying $523,000 in 2022. The Facebook owner stopped paying for Sandberg’s personal flights when she stepped down as a company employee in September 2022. She remains on Meta’s board.
Spokesmen for Meta and Sandberg declined to comment beyond Meta’s securities disclosures.
CEOs incurred most of the personal flight spending, making up half the executives receiving the perk in 2022 and two-thirds of the overall cost, Equilar’s data show.
At some companies, other executives are making up a bigger share of the cost. Four Norfolk Southern executive vice presidents accounted for just over half its roughly $370,000 in spending on personal flights in 2022, securities filings show. CEO Alan Shaw accounted for the rest. By contrast, the railroad reported subsidizing flights only for then-CEO James Squires in the five years through 2020.
Shaw may take as many as 60 hours of personal flights on company aircraft before reimbursing Norfolk Southern, the company said in its filings. Personal use of company aircraft by executives other than the CEO was infrequent, it added. Norfolk Southern didn’t respond to requests for comment.
—Jennifer Maloney contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
