Returning From Parental Leave Can Be Stressful. How Some Employers Aim to Fix That.
Companies increasingly are creating formal ‘reboarding’ programs to help new parents transition back to work more easily
By TARA WEISS
Thu, Feb 1, 2024 9:04am 5min
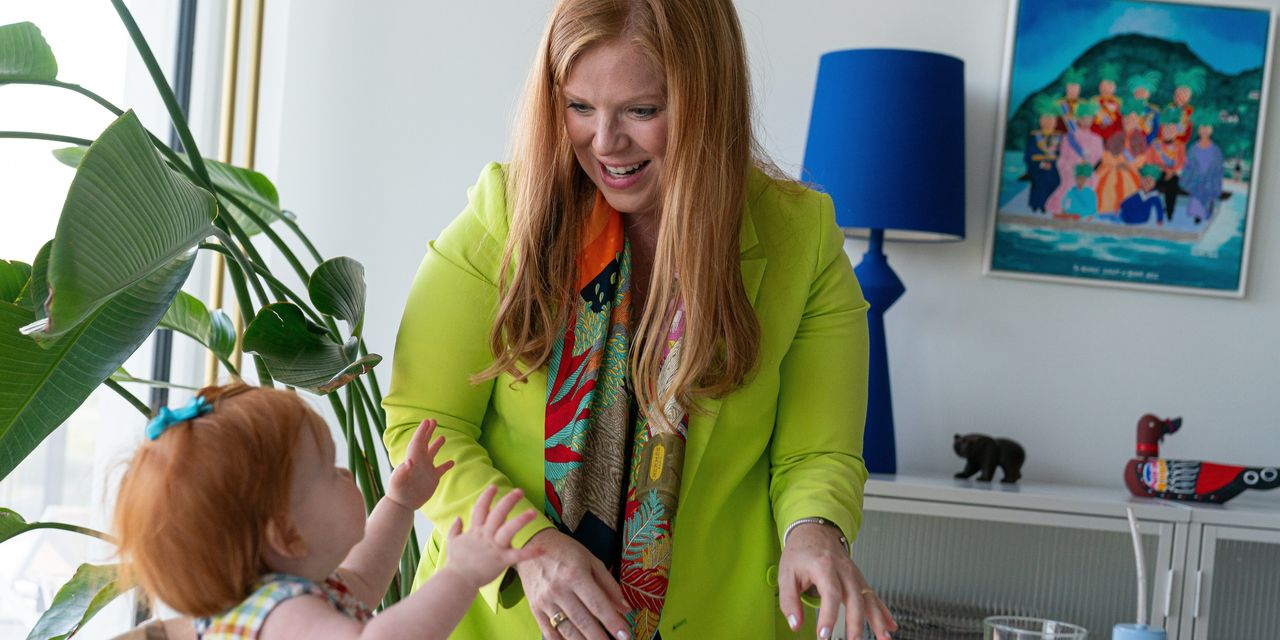
Sarah Tucker-Ray, a partner at McKinsey, had a reintegration plan all set before going on parental leave. ELIZABETH FRANTZ FOR THE WALL STREET JOURNAL
Sarah Tucker-Ray, a partner in McKinsey’s Washington, D.C., office, felt a lot of trepidation when she took a six-month parental leave in 2022.
“There is fear about, ‘Am I going to get written out of the story?’ ” says the 36-year-old Tucker-Ray, whose daughter, Viviana, was born in August 2022. “Is someone going to step in for me and take over? How will I come back?”
She addressed those fears in a reintegration plan that she drafted before going on leave. It included instructions for those who would be covering her workload while she was out, and it laid out what she wanted her job to look like when she returned. For example, Tucker-Ray didn’t want her role to change significantly, but she asked to not be given any internal projects—those focused on McKinsey’s own operations versus those of outside clients—during her first six months back. She also thought about small stuff, such as writing down all of her passwords, and she connected with other working mothers at the company who served as peer counsellors before she went on leave.
“They told me that the goal for week one is to get dressed, have breakfast with my baby, get into a suit without getting spilled on and get out the door,” she says. “It sounds so basic but I hadn’t had to do that yet.”
The days, weeks, and months after a new parent returns to work after leave can be a critical and challenging time for an employee. Many experience anxiety about how they are going to manage work and parenting, and some end up feeling like a failure at both.
To address that, some organisations have launched formal “reboarding” programs that structure those first months back after leave so they aren’t overwhelming for new parents, while also providing them with emotional support. McKinsey tested such a program in Europe and then expanded it globally
Many see it as a business imperative. Organisations are making substantial investments in paid maternity and paternity leave—in 2023, 40% of organisations in a Society for Human Resource Management survey offered paid maternity leave and 32% offered paid paternity leave—and they want to ensure new parents return to work and are productive and content when they do.
Tucker-Ray was happy to learn that McKinsey would cover the cost of her daughter and her husband to join her on a business trip. PHOTO: ELIZABETH FRANTZ FOR THE WALL STREET JOURNAL
Creating a plan
A successful reboarding program requires planning, and it and starts long before an employee goes on leave, consultants and HR leaders say. It begins with mapping out a comprehensive work-coverage plan, including if and under what circumstances the employee wants to be contacted about work while out on leave. The plan also should create clear expectations about what the return-to-work will look like, including the employee’s job description post-leave and even an explanation of what that first daunting day back might entail.
Many reboarding programs also connect new moms with experienced working parents or colleagues who have recently returned from parental leaves, as well as a coach (often an outside consultant) who can help set priorities and guidance on best practices.
When Maria del Mar Martinez became head of McKinsey’s diversity, equity and inclusion efforts in Europe in 2018, she learned that working moms left the management-consulting firm at nearly double the rate of their childless female peers with similar tenure. In exit interviews, women shared common grievances, including the challenge of balancing parenthood with a demanding job, a lack of support from their managers and few role models.
She heard similar sentiments in Asia and the U.S.
“That was a business problem,” says del Mar Martinez, now the global head of DEI at McKinsey. “I don’t want to lose those amazing women coming up the pipeline.”
To combat attrition, del Mar Martinez created a reboarding pilot program in Europe that included coaching employees before, during and after a parental leave. (Men are eligible to take part in the program if they have taken 12 weeks or more of leave.)
Built into the plan was a guarantee that new parents would have “meaningful work” upon their return, with the option of slowing down if that’s what they wanted, says del Mar Martinez. One issue, she and others say, is that managers often incorrectly assume that new mothers want lighter workloads or don’t want to travel, which is why it’s important for employees to spell out their preferences in a reboarding plan.
The McKinsey pilot required managers to confirm they understood their employee’s reintegration plan and to calibrate goals in performance reviews to ensure the person taking leave wouldn’t be penalised.
It worked. McKinsey closed the European attrition gap in 18 months, del Mar Martinez says, and later expanded the program globally.
The manager’s role
Other companies are increasing the support they offer to new parents, too, including Wall Street’s Morgan Stanley, which in 2019 appointed Allyson Bronner head of family advocacy at the company’s institutional division, a full-time position that focuses on supporting employees before, during and after parental leaves.
Bronner says one of the best ways to ensure a successful return experience for new parents is to include managers in the process.
To that end, she meets with an expecting employee’s manager between the 25th and 30th week of pregnancy to preview what the employee’s return-to-work will look like and discuss best practices for easing the transition.
“It’s important to set the scene and give them tools to manage their employees,” she says.
She says her next meeting with the manager occurs about a month before the employee is due back to discuss how the first month should be structured. She suggests the manager call the new parent two to three weeks ahead to preview what the first few days back will look like—namely, checking email and showing colleagues baby pictures.
The support continues throughout the first several months, with managers having weekly check-ins with the employee for the first six weeks and then monthly check-ins after that. Bronner encourages managers to ask new parents how they are doing and how their child care is going to determine whether they would benefit from more support or advice in that area.
Since Morgan Stanley created the family advocacy role, “it feels like there has been a culture shift,” Bronner says. “It’s hard to quantify in numbers, but culturally it feels like we’re moving in a more positive direction.”
A culture shift is also under way at chip-equipment maker ASML, which recently expanded the paid parental leave it offers and in May joined forces with employee-benefits firm Parentaly to create a support system for new parents.
ASML is in a male-dominated industry, says Karen Reinhardt, the firm’s chief human-resource officer in the U.S., so retaining women is critical to having a diverse workforce.
As of December, 82 employees had registered for the reboarding program, “more people than we expected,” Reinhardt says.
Among them is Meredith Polm Sheain of San Diego, a knowledge-management developer who went out on maternity leave in late August. In her reboarding plan, she made clear that she wanted to be notified while on leave about any bumps in a recently launched product. She also laid out her priorities for the first two months of her return.
“I felt so much better about the concept of returning to work once I gave my team this plan,” says Polm Sheain, who returned to work on Dec. 22. “I left them and myself in the best position I could.”
Reboarding isn’t the only new benefit companies are offering to make life easier for new parents.
McKinsey’s Tucker-Ray was asked to attend a partner conference in Atlanta about six weeks after returning from maternity leave. The firm covered the cost of her daughter and caregiver (her husband) to join her on the trip since she was still breast-feeding.
“I would have been torn about going away for nearly a week for an internal event but it became a nonevent,” she says. “It got rid of the barrier to feeling you can’t participate fully in parenting and be a leader.”
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
By Laura Saunders
Fri, Oct 9, 2026 4min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.


 5 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



