
Build Your Own Rolls-Royce: Inside the Arcadia Droptail Roadster, the Latest From the Company’s Coachbuild Operation

By Jim Motavalli
Wed, Mar 6, 2024 9:11am 3 min
3 min

 3 min
Rolls-Royce’s Bespoke division is exclusivity personified, and the highest rung in that ladder is Coachbuild—which goes far beyond selecting unique colours or interior finishes and gives customers the chance to help design their own new cars.
The first of the Coachbuild cars was the Phantom-based Sweptail, hand-built over four years, reportedly for Hong Kong businessman Sam Li. It has a dramatic fastback roof that was a hit when revealed to the public in 2017. Rolls didn’t confirm the car’s cost, but some reports said more than US$12 million. The Sweptail has been spotted on the road in Europe.
The Boat Tail, shown (above) in 2021 and built on the Architecture of Luxury platform with Phantom V12 power, was the first commission from a consortium of three couples. It’s a unique convertible with a carbon-fibre parasol that opens to shade its occupants during al fresco parties. Beyoncé and Jay-Z are reported Boat Tail owners. Argentine footballer Mauro Icardi is said to be another keeper of the keys. The purchase price of these cars is around US$28 million, sources say.
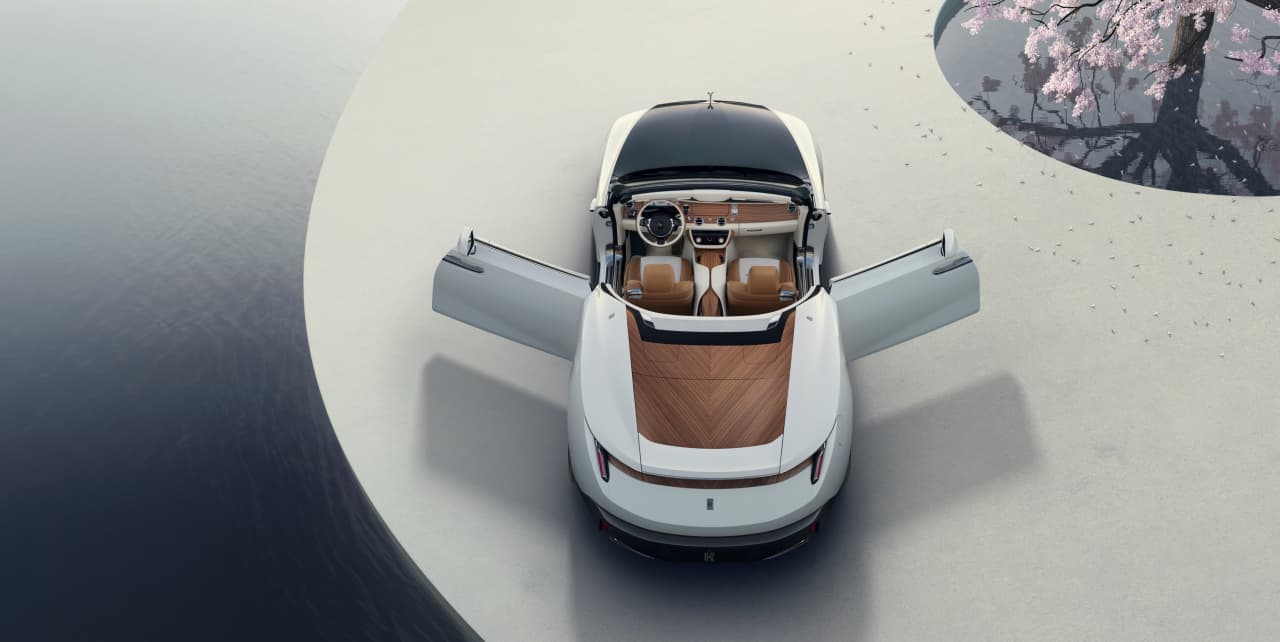
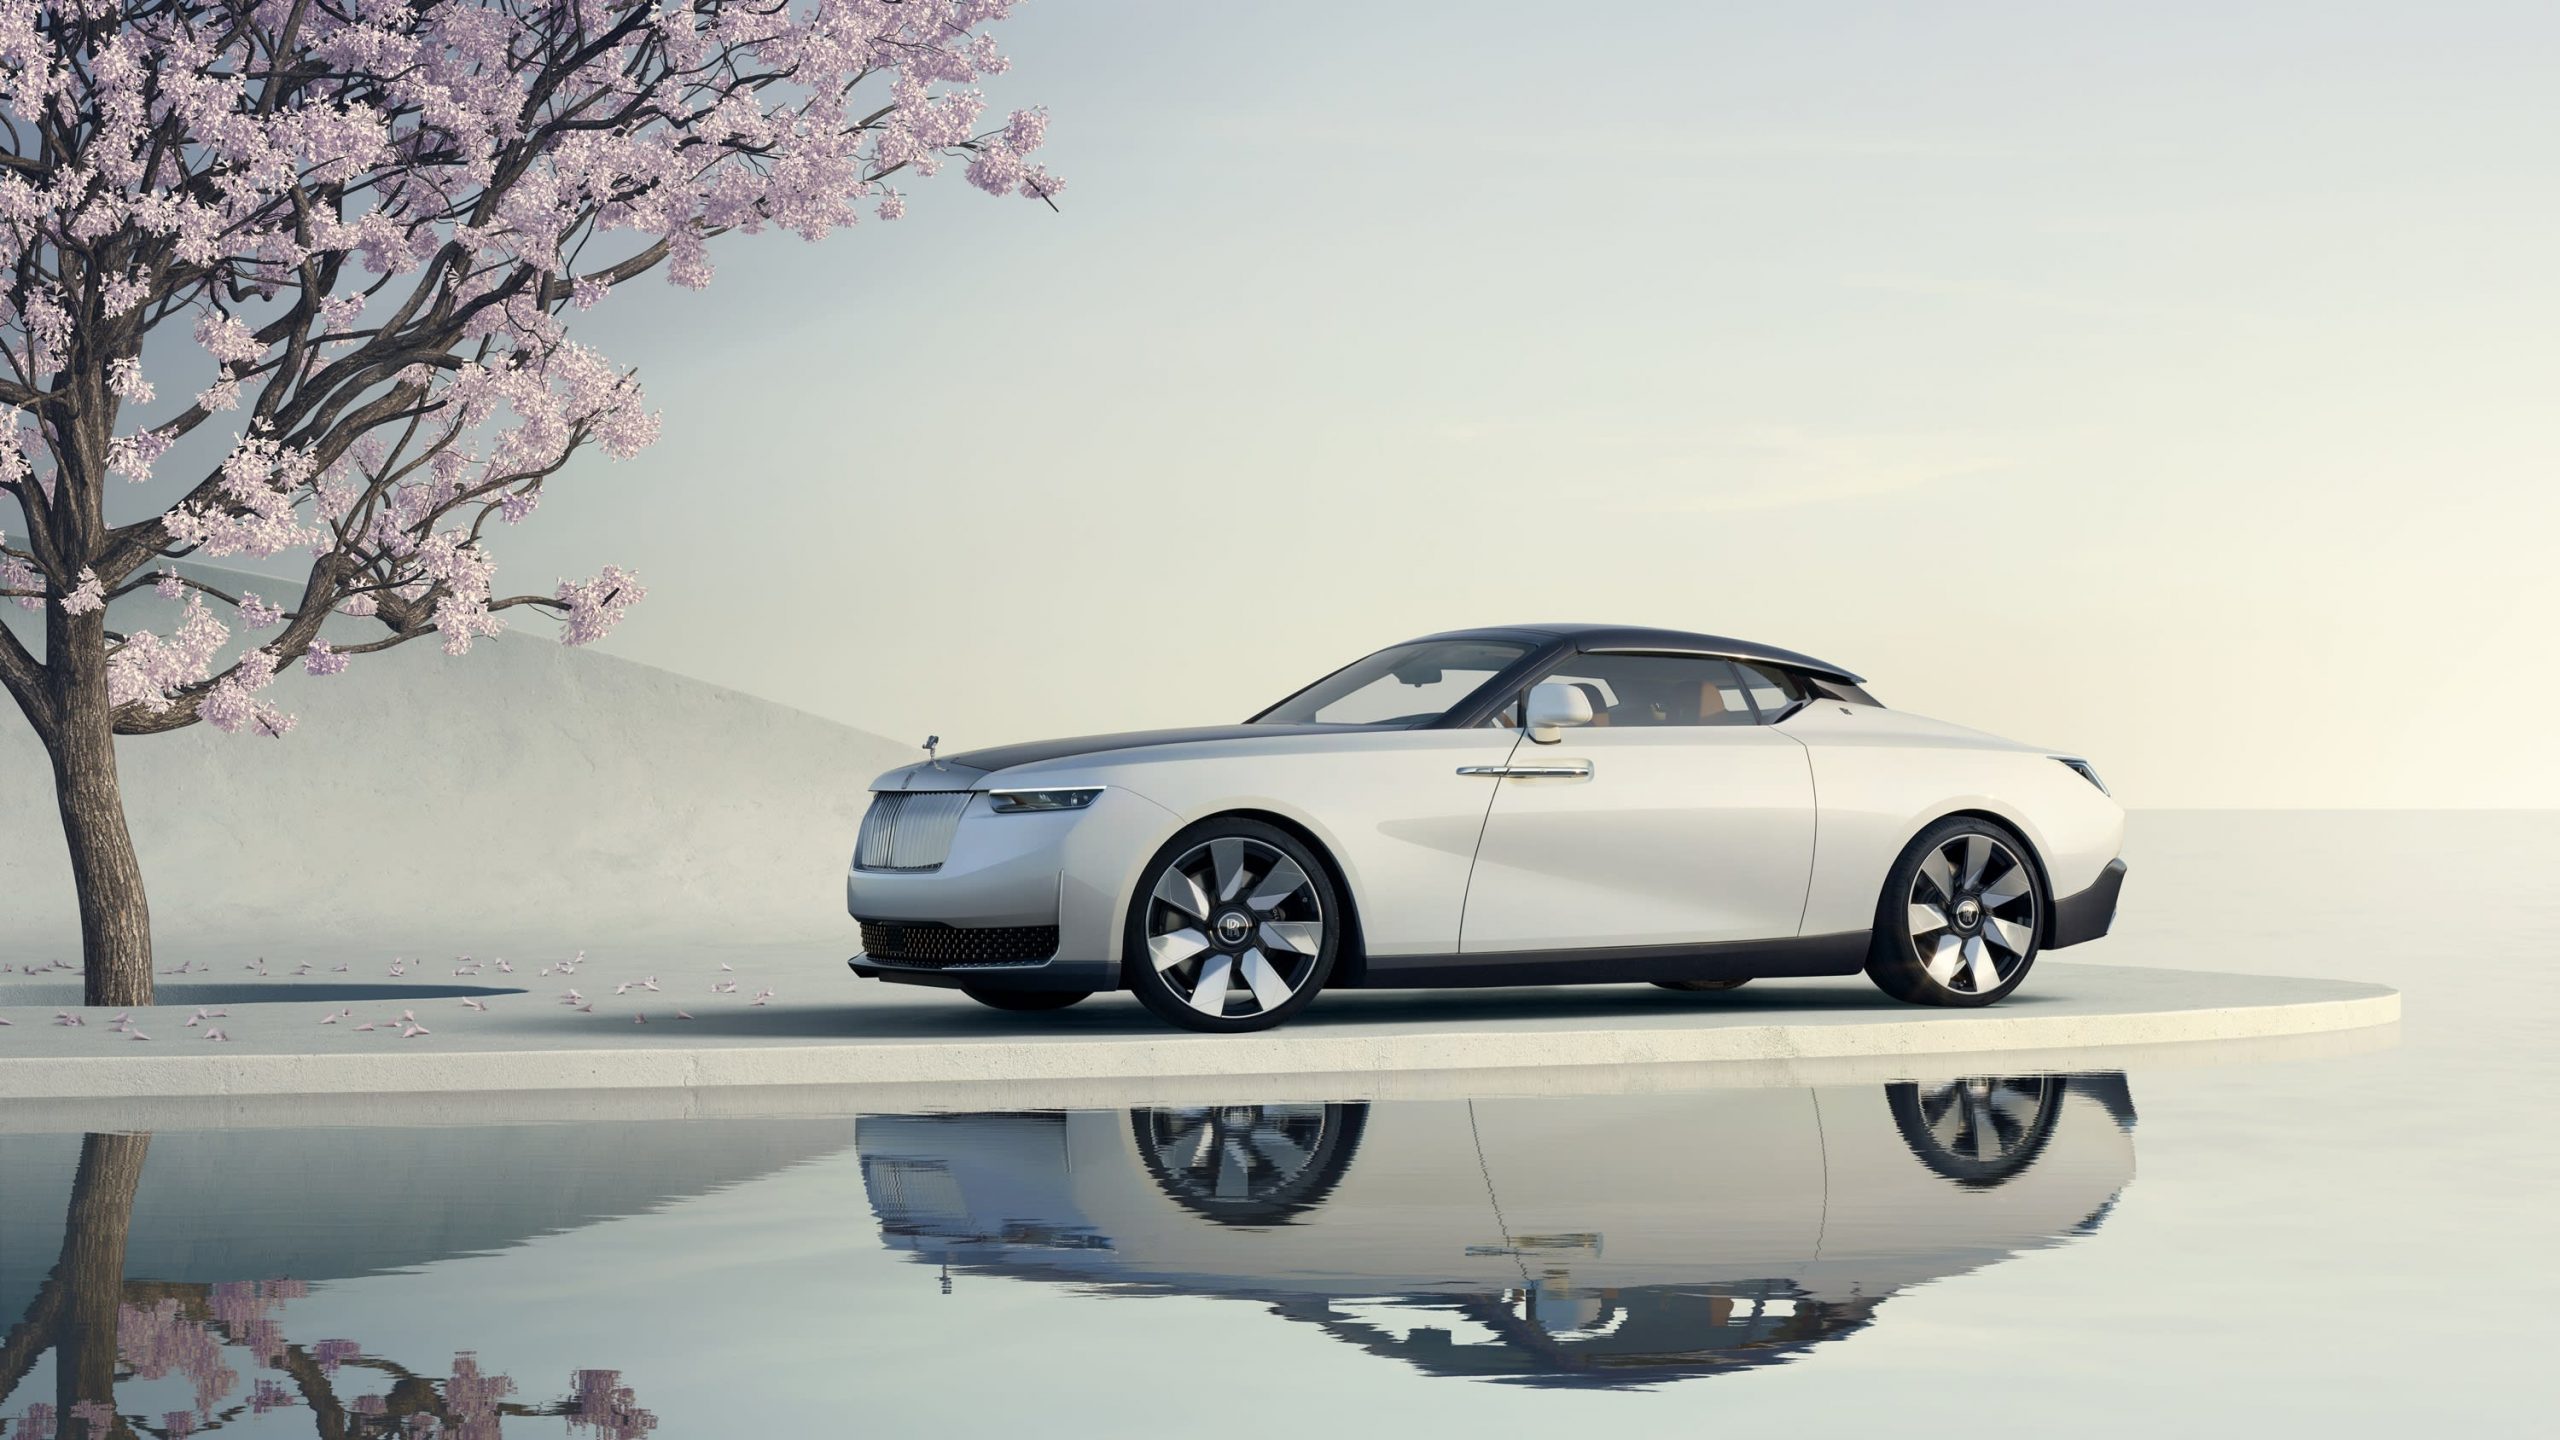
There will be a total of four Droptail roadsters created, and these now include the Amethyst Droptail and the La Rose Noire Droptail, each with unique rear-deck treatments and personal detailing throughout. The newest, third commission is Arcadia Droptail, which will come with a removable hardtop (and no soft top). The car will be delivered to an international client in Singapore, said Rolls’ Americas spokesman, Gerry Spahn. The price tag is likely in Boat Tail territory.
Arcadia was known in Greek mythology as a place of “Heaven on Earth.” The one-off car has a vivid recessed wood-panelled rear deck that took 8,000 hours to create, according to the company, and recalls vintage Chris Craft power boats—or woodie station wagons. It’s in left-hand drive, reportedly to better facilitate its use around the world. Rolls used a 3-D environment to show the client how the car would look in various locales.
“Coachbuild commissions like Droptail Arcadia are immediately the classic Rolls-Royce collectibles. Coachbuild is more than Bespoke, it’s the ultimate personal statement,” says Martin Fritsches, president of Rolls-Royce Motor Cars in North America.
Alex Innes, head of Coachbuild Design, added (in a statement) that the Arcadia is “one of the most faithful expressions of an individual’s personal style and sensibilities we have ever created within the Coachbuild department.”
Design inspiration for the Arcadia came from sky gardens in Singapore, Indonesia, and Vietnam, in addition to British “biometric” architecture.
The white paint is infused with aluminium and glass particles to give it depth and shine. The lower sections of the Arcadia Droptail are in carbon fibre, painted silver. The wood on the rear panel is mirrored on the dashboard (in Santos Straight Grain veneer), door linings, and central armrest. The wood pieces were mounted on stiff bases developed using carbon-fibre layering techniques derived from Formula One racing.
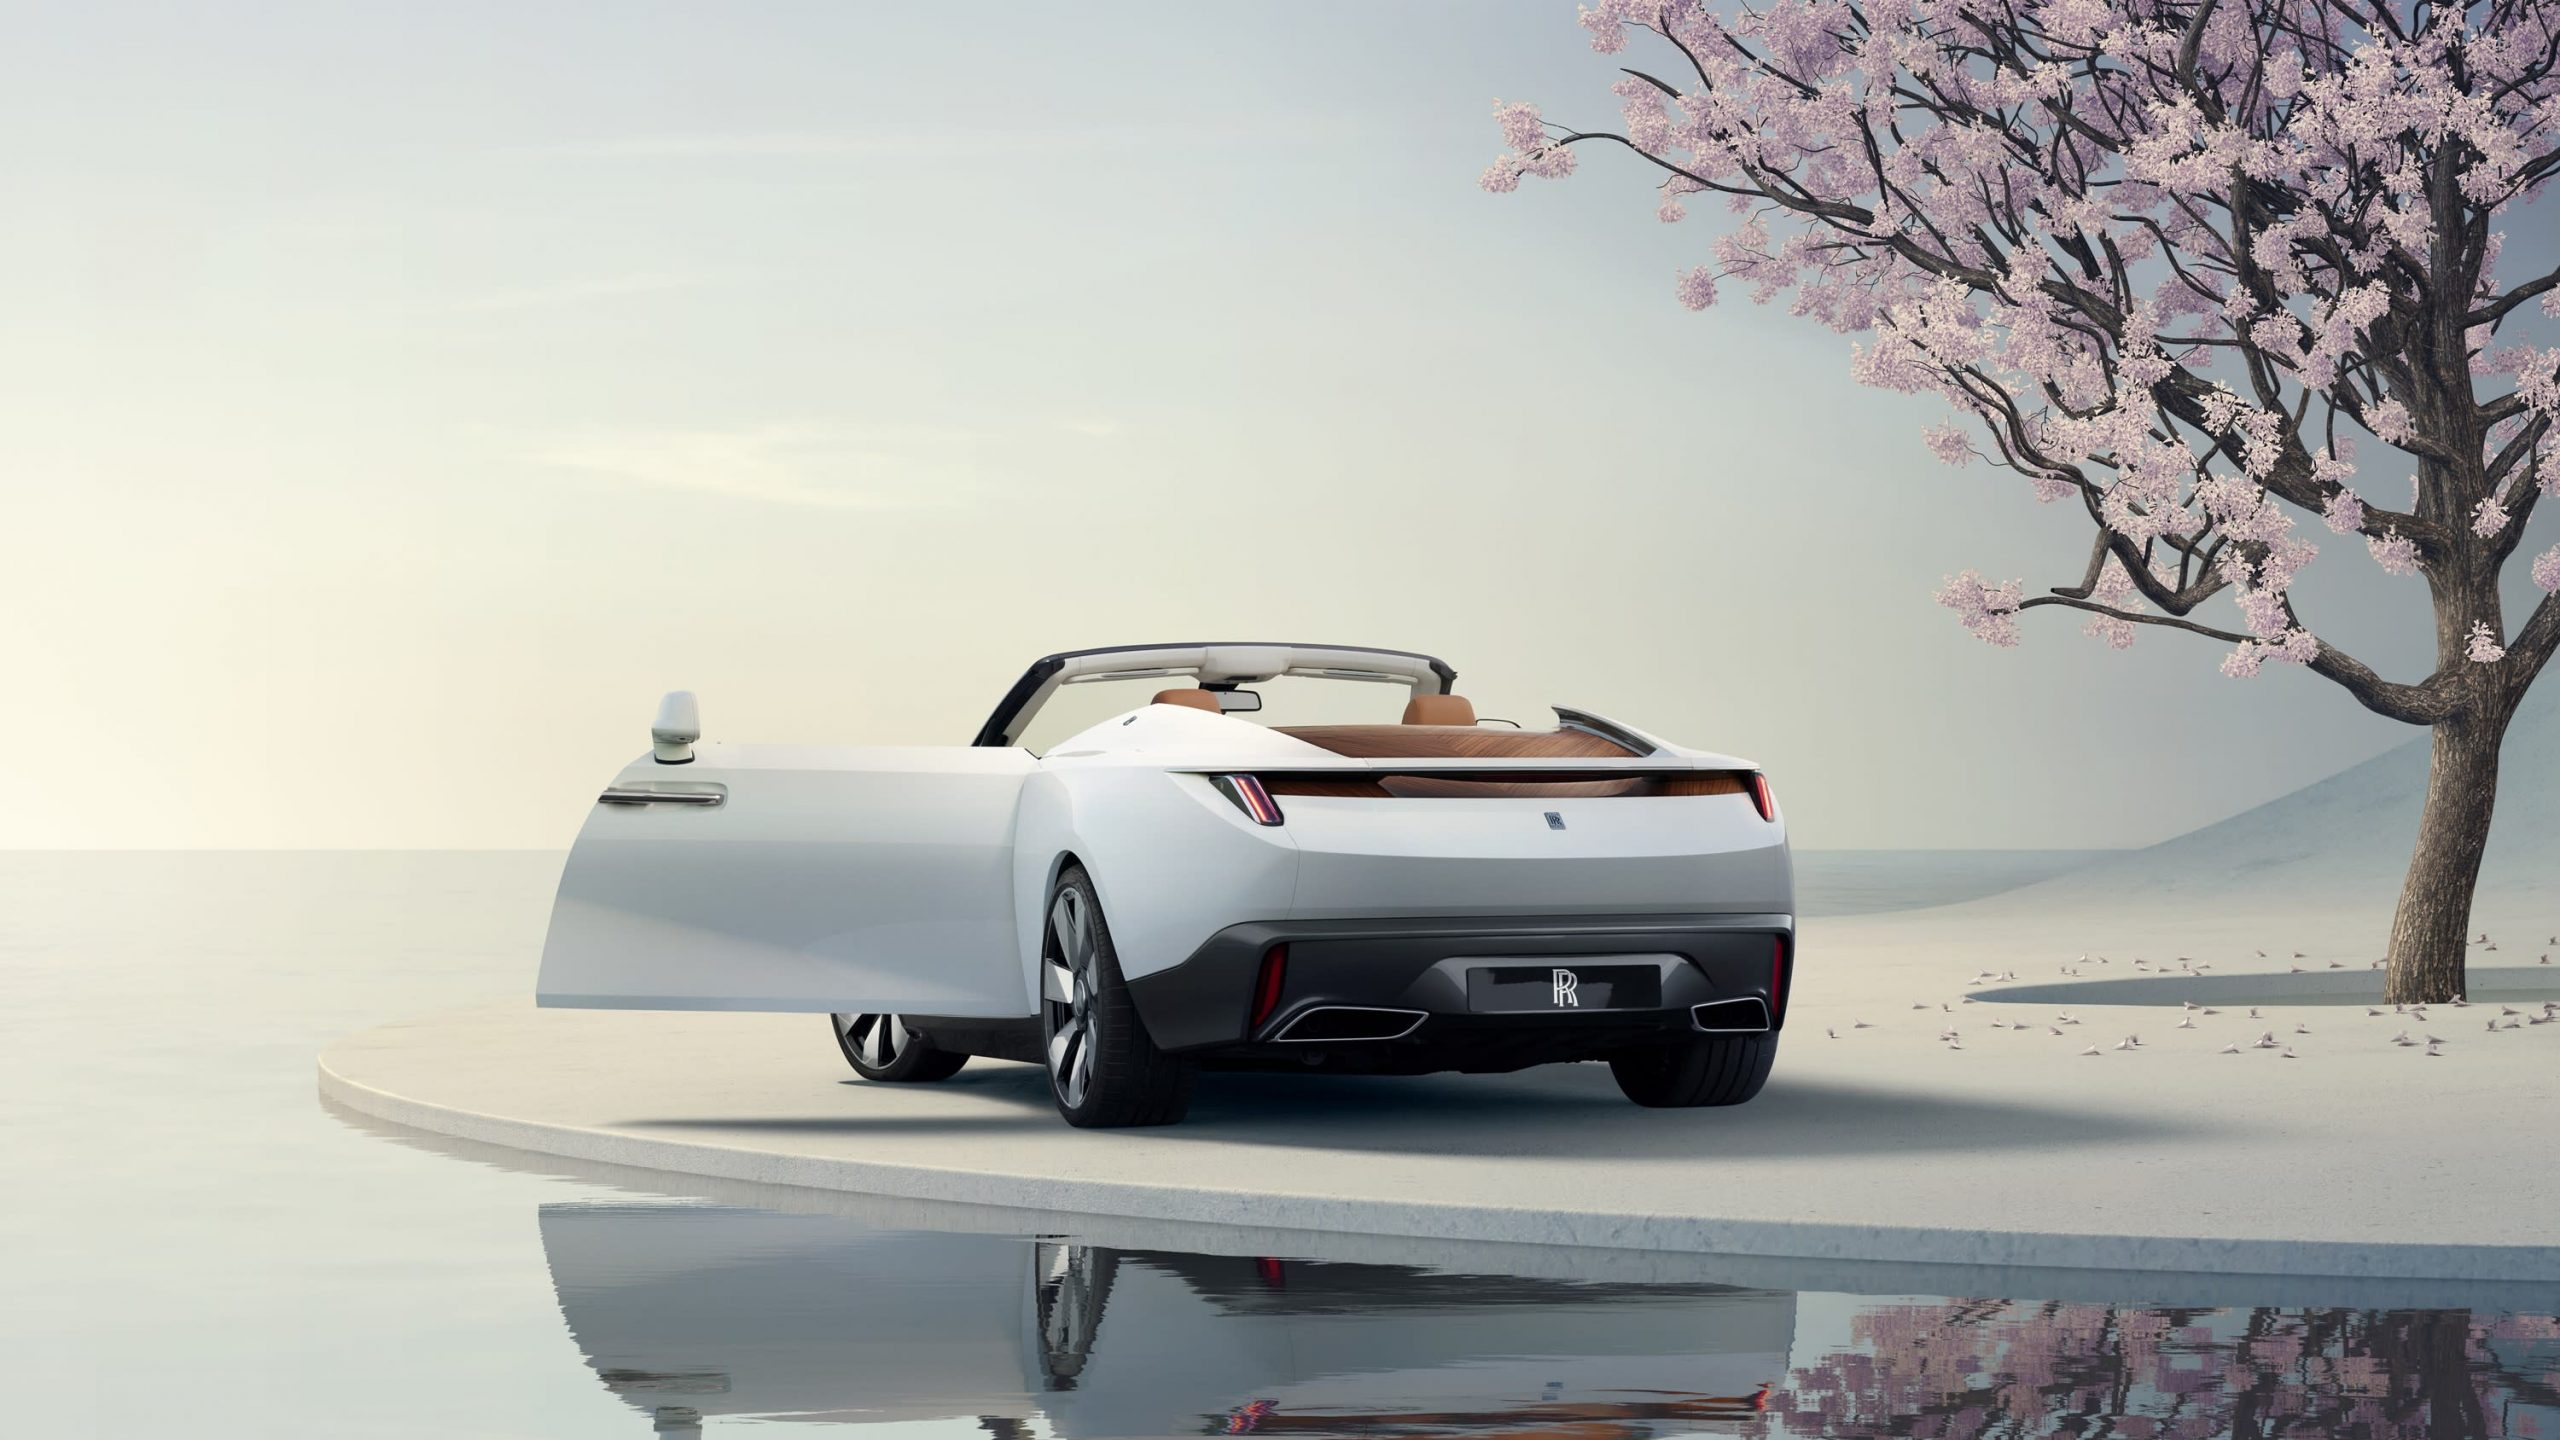
The hardtop, in a contrasting dark colour, slants down to a short rear greenhouse, giving the car a racy look. The doors are rear-hinged, with prominent chromed handles. The nose and grille are somewhat rounded, with narrow horizontal headlights, yielding a more aerodynamic prow than is customary in Rolls-Royce history.
The dash’s crown jewel is a clock with a face that took five months to assemble, after two years of development. Its raw metal geometric guilloche pattern has 119 facets. Rolls describes it as “the most complex Rolls-Royce clock face ever created.” The hands are partly polished and partly brushed, and have 12 hand-painted “chaplets” (hour markers) that are only 0.1 millimetres thick.
Many automakers are establishing bespoke divisions, but Rolls-Royce is, per tradition, taking it further than others.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
