
Former Wells Fargo Advisors Sue the Company Over Cross-Selling

By KENNETH CORBIN
Sat, Mar 9, 2024 7:40am 3 min
3 min

 3 min

Two former Wells Fargo advisors are suing the firm for breach of contract, unfair business practices, and retaliation after they say they resisted pressure from their supervisors to secretly transfer sensitive client information from the advisor and brokerage side of the company to the private bank.
The advisors, Karen Keusayan and Richard Green, are also alleging that Wells Fargo improperly withheld deferred compensation after they resigned in 2021 and joined Morgan Stanley , where they are still registered.
In their complaint, filed in Los Angeles County Superior Court, the advisors describe themselves as high-producing employees who were loyal to the company even through the “nightmarish” years of 2015 to 2017, when Wells Fargo’s banking division was “publicly scorned” for the fake account scandal.
“This is not the ‘sour grapes’ case of a disgruntled employee(s) who sought a promotion and did not get one,” the advisors say in their complaint. “Neither Ms. Keusayan nor Mr. Green ever wanted to leave Wells Fargo. The goal for each had always been to retire at Wells Fargo.”
Wells Fargo declined to comment on the lawsuit.
The two advisors joined forces in 2015 to form a “production partnership,” according to the complaint, which says they grew their book of business to more than $1 billion by 2020.
In 2018, Wells Fargo introduced a new element to its advisor compensation plan, according to the complaint. Advisors were expected to complete forms called client discovery reviews, or CDRs, detailing information about advisory clients. The plaintiffs say they were directed by a compliance officer to keep the forms secret from the clients themselves.
Instead, the CDRs were intended for Wells Fargo’s private bank, “not the broker-dealer/financial services side where plaintiffs worked,” according to the complaint.
They contend that advisors were pressured to work with clients to complete CDRs, which would be secretly shared with Wells Fargo private bankers who could use them as sales leads.
Before submitting the forms to count toward a quota that resulted in additional compensation, the advisors had to check three boxes stating that they had discussed the information with the client, that the information was accurate, and that they had offered the client an opportunity to obtain a copy of the document. On that last item, the plaintiffs allege that Wells Fargo essentially instructed the advisors to lie, explaining that the document didn’t belong to the advisors, but the bank, even though the information came from their own clients.
“[H]igh-ranking compliance personnel at Wells Fargo Advisors repeatedly told plaintiffs to never deliver or present the CDR to the client since, as it was explained by compliance, the CDR was a bank document,” the complaint states. “Worse, plaintiffs were told not to inform the client that a CDR had been prepared.”
The plaintiffs say that these “dishonest instructions” put them in an “impossible position” and that they soon began raising concerns with their superiors. But each time they spoke out, they were told by their supervisors to continue submitting the forms as a requisite part of the company’s compensation plan.
The complaint describes the advisors’ growing unease with being pressured to falsify the CDR submission document, as well as concerns over the personal privacy of their clients, whose information was allegedly being shared internally without their knowledge or permission.
The advisors say that their bosses undertook a retaliatory campaign against them for continuing to raise objections to the CDR program, “including by failing to provide the banking support that plaintiffs and their clients had come to expect as a benefit of being associated with a large, full-service, retail bank,” according to the complaint.
They also say that the advisors felt their jobs were at risk, offering examples of a hostile or coercive work environment. “Mr. Green was berated by a yelling supervisor in front of fellow employees, and Ms. Keusayan was informed that the bank would not issue a routine credit card to her sister (a customer) if a CDR was not on file,” according to the complaint.
The advisors say the deteriorating work environment ultimately led them to resign around July 2021, after which they were informed that they were ineligible for large sums of deferred compensation—$662,000 for Keusayan and nearly $814,000 for Green.
The advisors are seeking to recoup the deferred comp they say they are owed, and are asking the court for additional damages, as well as an injunction barring Wells Fargo from engaging in the conduct alleged in the complaint, among other relief.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
3 min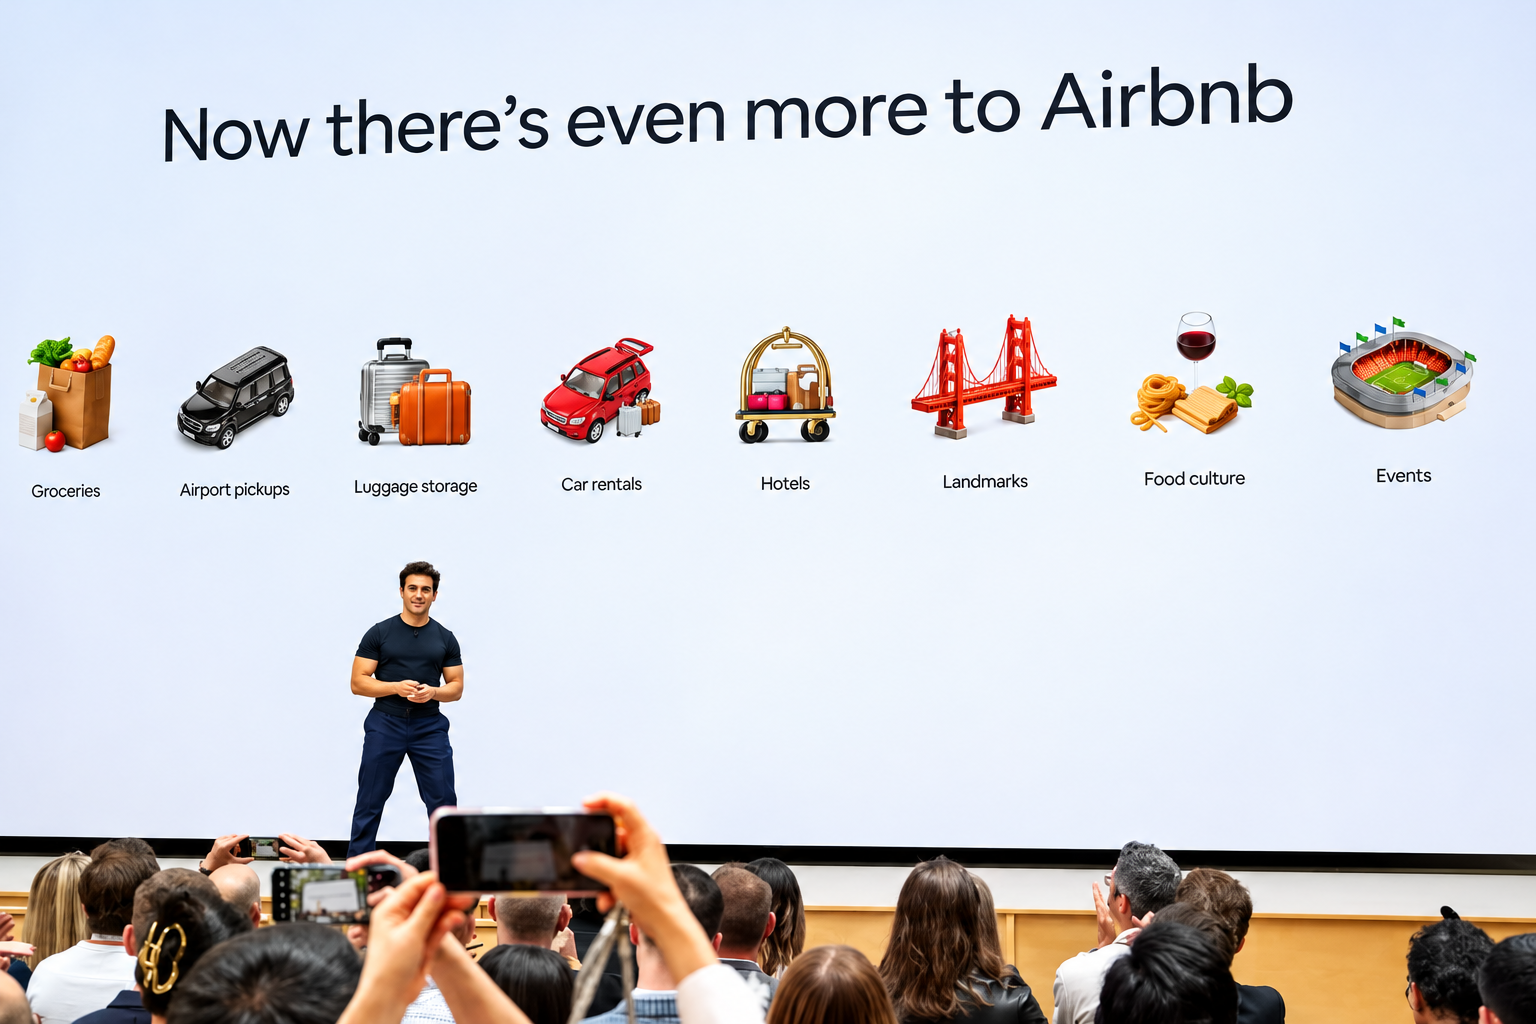
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.
