Stanley Looks to Replicate the Water-Bottle Hype Among Guys - Kanebridge News
Share Button

Stanley Looks to Replicate the Water-Bottle Hype Among Guys

Company wants to widen consumer base and product lines after its blockbuster growth among thirsty women

By KATIE DEIGHTON
Sat, Mar 23, 2024 7:00amGrey Clock 3 min

Stanley has spent the past few years turning a vacuum-insulated, 40-ounce water bottle into one of the most-desired womenswear accessories on the planet. Now it is widening its focus to include the customer it was first designed for more than 110 years ago—men.

The company, which is owned by Chicago-based HAVI, next year plans to release new products geared toward guys beyond its current male audience of outdoor enthusiasts.

The new Stanley man might not require a steel canteen to take into the wilderness, but he might want a sleek water bottle to take from the office to the gym to date night in a wine bar, according to Jenn Reeves, Stanley’s vice president of global brand marketing.

“He’s not a fashionista, but he cares about how he’s put together. He’s into grooming and how he looks, and into sports,” Reeves said. That hypothetical male customer wants water bottles that are a little sleeker and subtler than the brightly colored giant flasks coveted by Stanley’s female audience, she said.

The bid for diversification comes as Stanley looks to hold on to the brand equity it has accrued in a remarkably short time.  

Stanley’s annual revenue jumped to around $750 million in 2023 from $73 million in 2019, and scores of articles and think pieces have in the past year been written to explain how a company originally targeting construction workers became one of the trendiest brands of the moment. Much of the success comes down to the recent rise of the brand’s 40-ounce Quencher, which it introduced in 2016. The $45 metal cup with a straw and a handle has become a status symbol among women and tweens, caused new-product frenzies in stores, and generated a “Saturday Night Live” skit lampooning women who drink out of comically “big dumb cups.”

Imitators and competitors for thirsty consumers are hot on Stanley’s heels. They include cooler-maker Yeti , which last year introduced a 42-ounce straw mug similar in design to the Quencher.

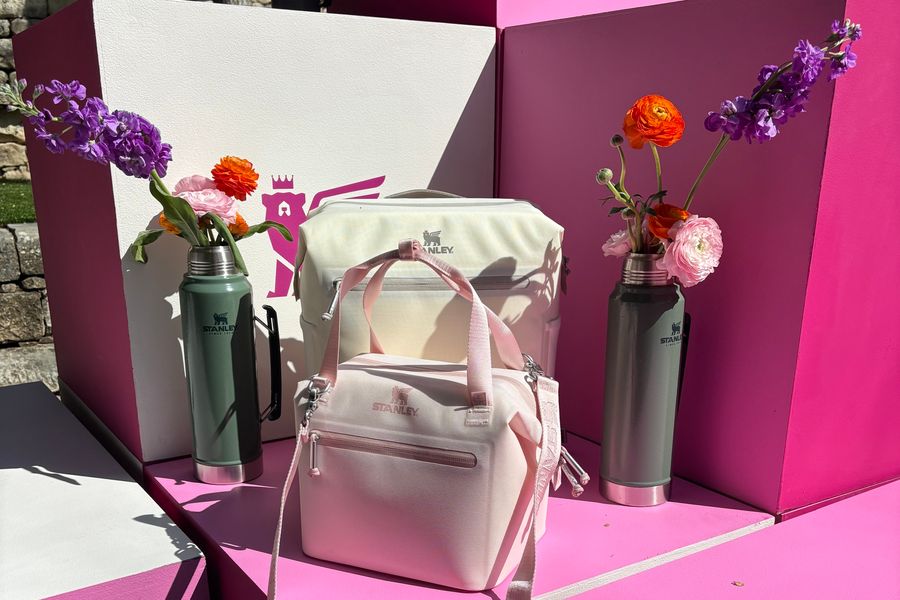
Stanley’s latest release is a collection of cooler bags and a carryall holder for its 40-ounce Quencher bottle, slated for release in April. The wearable coolers were developed in response to women’s complaints that the market’s existing offerings were too heavy, too clunky and too ugly, and the crossbody was designed to ease the burden of carrying a water bottle and a purse around all day.

Beyond hammertone green 

The Stanley customer only became known internally as a “she” in 2020, when Terence Reilly, the former chief marketing officer of Crocs , joined as president. Reilly, who liked to say his team had turned Crocs’ divisive shoes “from a meme to a dream,” learned that the Quencher was becoming popular among a group of women in Utah, a few of whom ran a shopping blog called the Buy Guide , according to one of the blog’s co-founders.

The group, along with a female Stanley sales account manager, suggested that the company start selling its cups in colors outside of black, white and its signature hammertone green, and it did. Sales lifted, while the company began to lean more on real women to spread the word about its products.

The Stanley marketing team has grown slowly since Reilly’s arrival but is still tiny by industry standards: only seven full-time staff members across advertising, brand, marketing, media and social media, said Reeves, who joined in 2022. The company spends money on traditional direct marketing, such as email campaigns, but its biggest focus is social media and working with real women and influencers who promote Stanley to their followers.

Stanley got a big, unexpected break in November, when a TikTok user named Danielle Lettering posted a video claiming that the only item to survive her car fire was her Stanley Quencher. The clip went viral, and Stanley bought her a new car and covered related costs including taxes.

Influencing men

Many of Stanley’s male consumers are already Quencher fans, Stanley said, and guys sometimes feature in its ads. The company heading into 2025 has to translate its social-media momentum among women into a marketing strategy designed to attract more men with the planned sleeker range.

The typical male consumer is also swayed by the recommendations of influencers, but he often spends time on different platforms than his female counterpart, said Chris Anthony, the chief revenue officer of media company Gallery Media Group, which works with social-media content creators. He is likely to track interests, teams and channels, as opposed to following specific influencers across all platforms the way some women do, he said.

“Guys rely more on their feed versus the people,” Anthony said. “And letting the influencers tell their stories, and not being so prescriptive, will especially resonate with guys in the right way.”

Some of those influencers might be Stanley’s current best customers, Reeves said. “We have the women, and they love us,” she said.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Lifestyle
AI Agents Are a Threat to Travel Businesses. Airbnb Could Still Be a Winner.
By David Wainer 13/10/2026
Lifestyle
Amazon in Talks to Buy AI Startup Decart for Around $7 Billion
By Kate Clark and Lauren Thomas 12/10/2026
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026

Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.

By Laura Saunders
Fri, Oct 9, 2026 4 min

Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.

This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.

Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.

Here are three strategies useful for functional families.

Intrafamily loans

It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.

But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.

If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.

To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.

In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.

If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.

Asset gifts

Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.

The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.

Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.

However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.

These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.

But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.

Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.

The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.

Sellner doesn’t worry about his children using the funds for another purpose.

“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.

Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.

Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.

Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”

Disclaimers

A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.

Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.

Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.

Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.