
Investors Have Cooled on Hydrogen. A Second Wave Is Coming.

By PATTI DOMM
Fri, Apr 12, 2024 9:43am 5 min
5 min

 5 min
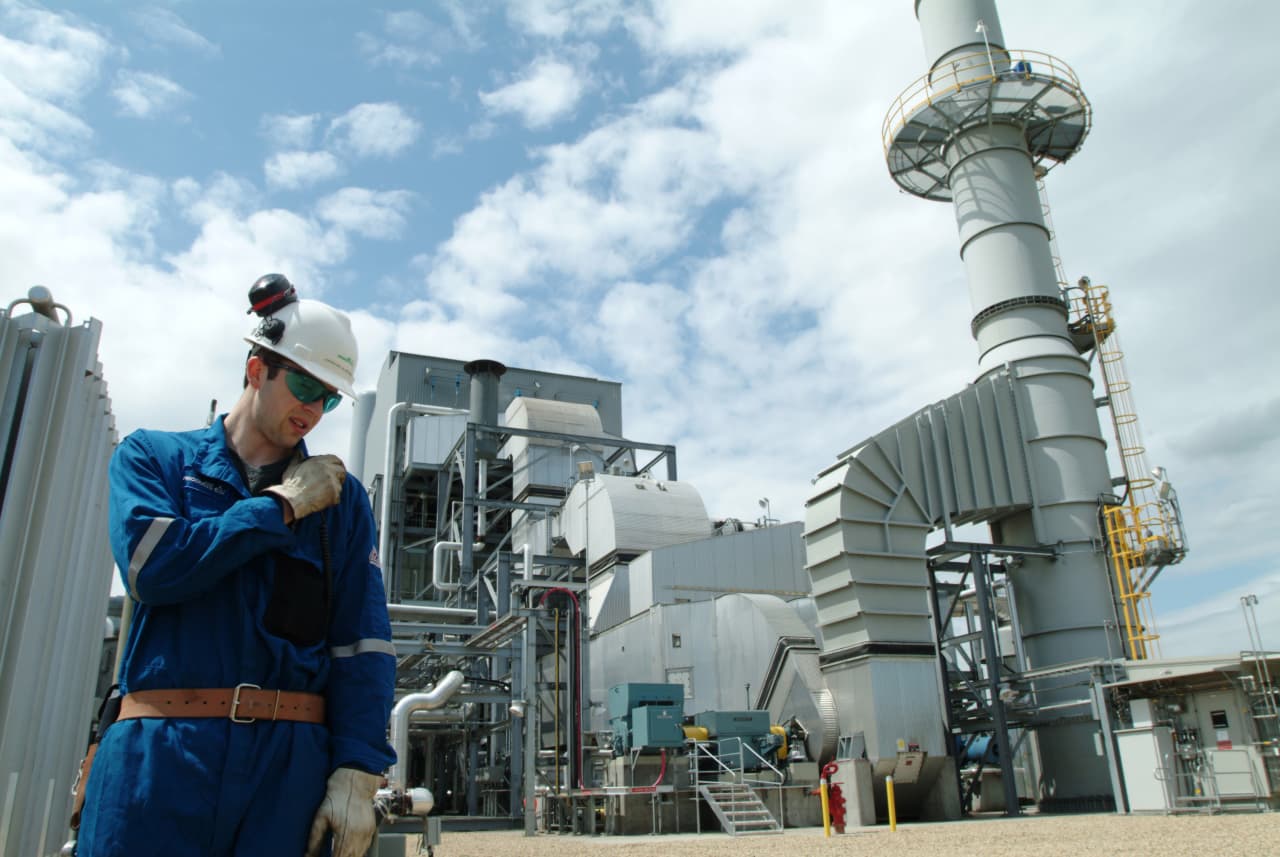
Investors may want to give hydrogen a second look, but they’ll need to be patient.
There’s not a lot of love for the fuel on Wall Street. The Global X Hydrogen ETF is down 81% from its high in 2021, and other hydrogen stocks are well below their peaks.
Skeptics say the cleanest hydrogen is too pricey and still far away from becoming part of a viable marketplace. The government is still sorting out regulation and industry incentives. New infrastructure will be required, and it isn’t clear there will be enough customers once it’s built.
But even as investor enthusiasm faded, a raft of companies have been quietly exploring hydrogen as a clean-burning fuel that can be a building block in the energy transition. There are numerous corporate projects in development that could help propel the growth of a hydrogen economy and drive profits in the future. The Department of Energy is investing $8 billion in promoting clean hydrogen, with the creation of seven hydrogen hubs around the U.S. within the decade.
Many energy and petrochemical companies are studying or have hydrogen projects in the works as a way to decarbonise. One reason is that hydrogen is used in the refining process, and cleaner hydrogen could be used in industrial processes. Hydrogen can be turned into ammonia and is used in fertiliser. In its next wave, hydrogen could be widely used in industrial applications like steel making and for fuel in ships and aircraft.
Supporters believe all the money pouring in now will help bring costs down as hydrogen projects scale. Investors may want to look at traditional energy and industrial companies that are currently working on hydrogen projects as a way to play the long-term growth of a hydrogen market.
“All these companies…have decarbonisation aspirations,” said Marc Bianchi, managing director at TD Cowen. There’s a meaningful opportunity for companies that are already using thousands of tons of hydrogen a day to switch from dirtier to cleaner sources.
The U.S. uses about 10 million tons of hydrogen a year for applications such as refining and fertilizer. Hydrogen demand was about 2% of global energy consumption in 2020 and could grow to 20% to 30% in a net-zero economy, according to S&P Global Commodity Insights.
Hydrogen gas is colourless, but industry shorthand assigns colours based on how the fuel is produced. Green hydrogen is the most desirable. Electricity generated from solar or wind is used to split hydrogen from water molecules and produces no carbon byproducts. Blue hydrogen is made by using natural gas along with capture and storage technologies to limit CO2. Grey hydrogen is made with natural gas or methane and generates carbon dioxide.
S&P Global Commodity Insights projects the cleanest hydrogen, even with incentives, would be about three times more costly in parts of the country where renewable energy is more expensive, like the Northeast. In the best case, green hydrogen produced in Texas, using proposed tax incentives and credits, could be as low as $1 per kilogram, slightly less than the $1.3 per kilogram cost of grey hydrogen. In Europe, green hydrogen is $6 to $9 per kilogram.
The energy industry, however, is waiting to see the final structure of U.S. tax credits granted to clean hydrogen under the Inflation Reduction Act. The Internal Revenue Service issued a draft guidance on implementation.
It was viewed as too restrictive by many in the industry, and some industry executives say it put a chill on activity while they wait to see how deep incentives will be for their proposed processes. The comment period has just ended.
“Anyone in power generation wants to talk about hydrogen,” said Richard Voorberg, president of North America for Siemens Energy . “Now, we’ve seen that plateau over the last little while, meaning months. Everyone was excited about [the Inflation Reduction Act], but the guidance that came out Dec. 22 had people scratching their heads.”
Ernest Moniz, a former energy secretary, heads the consortium formed to organise a market for clean hydrogen, called the Hydrogen Demand Initiative. Moniz said recently that the guidance presented by the IRS was too narrow and could slow the industry’s growth if not changed.
“The philosophy has been to require upfront decarbonisation of the electrons that you’re supposed to be using for the electrolysis of water, and the fear—and I certainly fear it—is this will significantly inhibit the near-term demand creation,” Moniz said. “We might end up with a very low carbon grid, but a hydrogen market that’s way behind where it should be at that time.” He added that he’s watching for how the IRS adjusts its plans for the tax credits.
Investors looking at companies with hydrogen projects need to be sure the value is there for the company’s traditional businesses. Analysts say valuations don’t appear to reflect potential for hydrogen, even if some had in the past.
Hydrogen was once the “shiniest new toy” for investors, but disillusionment has set in, said Timm Schneider, CEO of Schneider Capital Group. “Not one investor has asked me about hydrogen at any company, like Chevron or Exxon, that has a hydrogen project, over the past 12 months,” he said.
One way to invest in the transition is through industrial gas companies. S&P Global is projecting that Air Products and Chemicals will be the leading industrial gas producer of hydrogen, in the amount of 5.2 million metric tons by 2030. Exxon Mobil is positioned to be the largest producer among oil-and-gas companies, with 1.5 MMT, S&P Global said.
Air Products CEO Seifi Ghasemi, speaking at the CERAWeek by S&P Global conference last month, said his company is currently the largest producer of grey hydrogen globally. He wants to be the leader in green and blue. The company began producing grey hydrogen at the request of the U.S. government in the 1950s for use in the space program.
Ghasemi said the company has two major projects in development. One is in northern Saudi Arabia, where the company will use wind and solar with its partners to create 650 tons of hydrogen a day. That project, he said, IS “30 times bigger than anything that exists today.”
Air Products has been collaborating with Baker Hughes , an energy services and technology company that has developed turbines and compressors. Baker is working on the hydrogen project in Saudi Arabia and the two have another project under way in Alberta, Canada that is expected to be operational next year. “Baker Hughes is interesting. It is supplying a turbine to that project in Alberta that’s going to run on 100% hydrogen. That’s been a bit of a challenge for the industry, to burn hydrogen in a turbine,” said Bianchi. Baker Hughes, he said, was the first to succeed.
The demand for hydrogen is still uncertain and the market is nascent. The anticipated supply of hydrogen is well ahead of demand, Enverus Intelligence Research said in a report last week. Only 30% of the U.S. projects expected by 2030 have disclosed customers.
But there was a bright note in the Enverus report. European Union decarbonisation targets could mean U.S. producers could find a significant export market.
Exports are what helped turn the U.S. into the leading producer of oil and gas. The energy industry might follow that playbook again with hydrogen.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
