Endless videos about the economy and consumerism are giving 20-somethings a case of ‘money dysmorphia’
By JULIE JARGON, ANN-MARIE ALCÁNTARA
Mon, May 6, 2024 3:49pm 5min
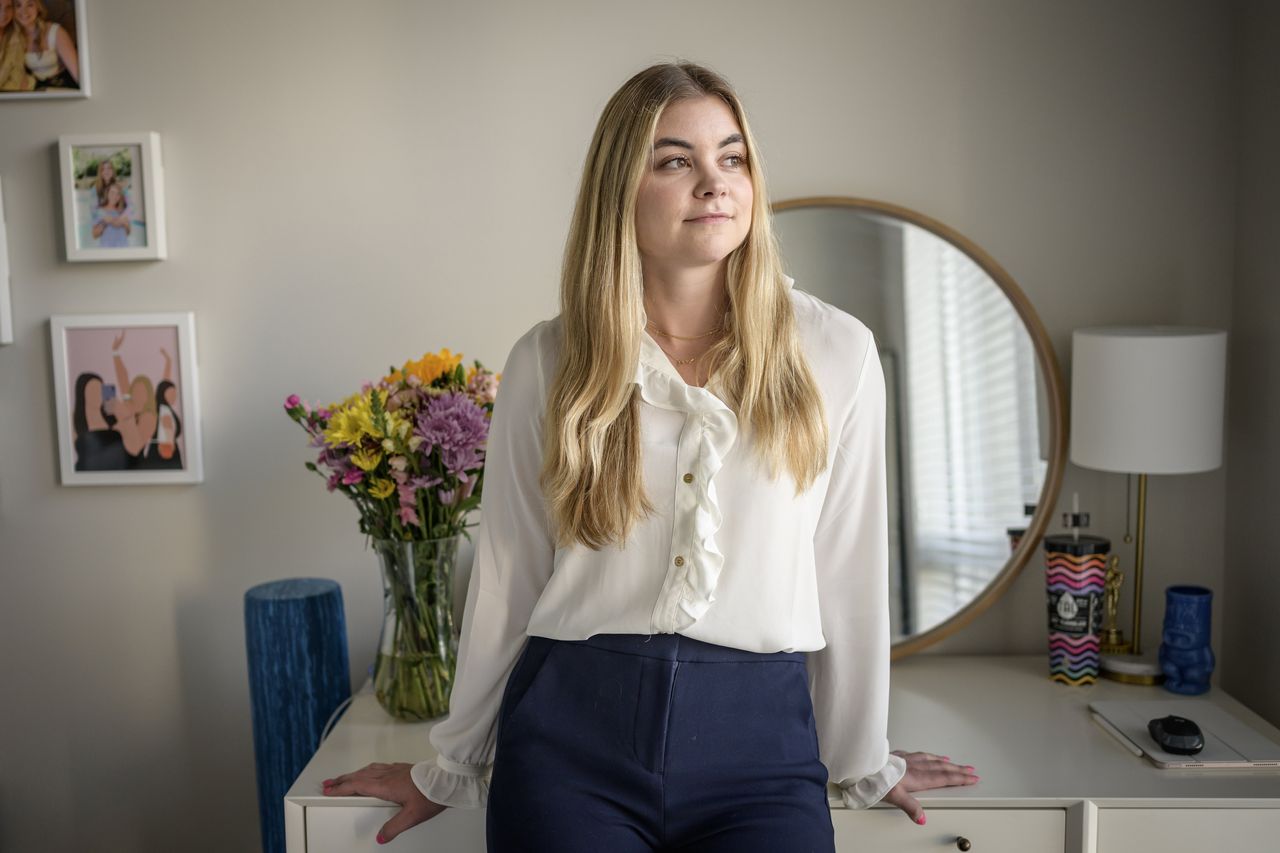
Caitlyn Sprinkle, 27 years old, says it has gotten more expensive to keep up with TikTok trends.
Americans under 30 get much of their news on TikTok. They hear about money there, too, and that’s shaping the way they save, spend and view their financial prospects, young adults and economists say.
Caitlyn Sprinkle, 27 years old, describes her TikTok feed as a mix of economic gloom and consumerism gone wild. There are Dave Ramsey TikToks that warn of the evils of debt , followed by influencers showing off their shopping hauls of skin-care products and handbags.
Sprinkle, a financial analyst at an asset-management firm in Nashville, Tenn., uses a budgeting app and has been cooking at home lately to save money—and to be able to afford the things she feels she has to buy, like Lululemon leggings. “Between TikTok and having your friends around you, you’re pressured to buy the things because you want to fit in,” she says. “That’s always been the case, but with TikTok it’s more prominent.”
Rallying stocks, rising wages and a tight labor market suggest the economy is stronger than it has been in years. The youngest, lowest-earning professionals don’t feel that way—partly because a large share are carrying consumer debt, and partly because of what they’re seeing on TikTok.
Even as the platform faces a potential ban in the U.S. , it remains a massive cultural force that shapes young adults’ decisions and views. More than half of all U.S. adults ages 18 to 34 use it, according to Pew Research Center, while about a third of those 29 and under say they regularly get news on TikTok , up from less than 10% in 2020.
So, what happens when your main source of news tells you that no one in your generation will be able to buy a house , food prices are spinning out of control and credit-card debt is unavoidable—but also that $2,500 Louis Vuitton bags and $70 moisturisers are, as many videos say, “a must”?
Interviews with finance experts and more than a dozen young adults suggest that the result is confusion, with a side of gloom. Under-30s are taking on debt as they embrace an old idea: If the outlook is bad, why not enjoy life now?
Their own money behaviour
TikTok is creating a disconnect between how well off young adults actually are and how they think they’re doing, according to economists and 20-somethings themselves. That disconnect has given rise to a term financial advisers use to describe young adults’ distorted view of their financial well-being: “money dysmorphia.”
Evelyn Hidalgo, 29, makes her living as a full-time content creator after being laid off from a social-strategist job about a year ago. While she posts about being a mum on a budget, her TikTok feed often shows her trendy items she wishes she had, or a life that seems impossibly far from her own, such as owning a large, beautiful home.
“It doesn’t feel like the norm is your normal,” says Hidalgo, who lives in Nashville with her husband and 20-month-old son. As she looks at the economy on TikTok and other social media, her feed feels “split in half,” between those living an enviable life and those who are struggling.
Sprinkle walks to the gym so she doesn’t have to pay for parking. PHOTO: WILLIAM DESHAZER FOR THE WALL STREET JOURNAL
Gen Z’s mixed economic feelings could have an effect on the outcome of the elections this fall, but the greater impact could be on their long-term financial health, economists say. Feeling financially uncertain can lead to poor choices, such as credit-card debt that eats into retirement funds and necessities such as food and housing, says Jacob Channel, senior economist at LendingTree, an online lending marketplace.
Over the past two years, members of Gen Z—those born between 1997 and 2012—effectively doubled their non mortgage debt, taking on roughly an additional $11,000 on average, according to LendingTree.
Still, younger American adults—those born in the 1990s—saw their median wealth more than quadruple to more than $40,000 between 2019 and 2022, according to the Federal Reserve Bank of St. Louis. That has outpaced the growth rates for previous generations at a similar age, says Lowell Ricketts, a data scientist there.
While many markers of adulthood such as homeownership feel out of reach, young adults are reaping the benefits from the current economic climate, says Monique Morrissey , senior economist at the Economic Policy Institute, a nonprofit economic-research and policy organisation.
“Gen Z and younger millennials are experiencing tailwinds and may not realise that they’re benefiting from a tight labor market that has led to an unusually rapid increase in real wages for younger and lower-wage workers,” she says.
Adding to the confusion is the economy itself. After a string of data showed strength in the labor market, growth is beginning to slow. U.S. employers added a seasonally adjusted 175,000 jobs in April, less than March and below the 240,000 economists anticipated, and unemployment rose to 3.9%, according to the Labor Department.
Keeping up with the Joneses
Many TikTok users say their feeds have become a loop of get-ready-with-me posts, ads, influencer partnerships and videos that encourage them to buy stuff from TikTok’s virtual shop . Some 91% of Gen Zers say they have purchased something they saw on social media, according to a survey from Citizens Pay, a buy-now-pay-later service from Citizens.
BreAunna Rodriguez, a 23-year-old mom of two in Houston, likes to buy TikTok-popular baby clothes and other small things for herself, including eyelash extensions, coconut-oil mouthwash and a pumice stone that influencers said reduces stretch marks.
“It’s hard not to buy things if they say it’s good for me,” she says.
TikTok has influenced bigger decisions, too, she says. Her For You page is filled with young entrepreneurs who snub the idea of a 9-to-5 job. This inspired her to quit her job as an assistant property manager in late 2022 and take a remote, commission-based job for an internet-and-cable company.
“You see a 19-year-old trader on TikTok who only has to work two hours a day, and I was like, ‘How do I do that?’”
Rodriguez says she makes more money now, contributes to a 401(k), pays off her credit card bills each month and puts her annual tax refund into a savings account to help with expenses throughout the year. Her biggest monthly expense is the $2,000 she pays for daycare for her two kids.
The constant videos of consumption—whether it’s a Stanley cup , a Jellycat plush or makeup —are hard to resist. TikTok last year created its own e-commerce engine , TikTok Shop, to compete with online retailers.
About six months ago, Sprinkle bought a Stanley tumbler. “I held out as long as I could,” she says, adding that she had bought several other water bottles that were trending on TikTok.
“There’s an internal pressure among my age range to constantly have these experiences and share them,” says Evan Naar, a 28-year-old lawyer in New York who posts TikToks about Broadway shows he’s seen and a Taylor Swift concert he attended.
Naar, who has several thousand dollars in student debt, says at some point he wants to save more money and buy a house. “A lot of my paycheck goes toward living expenses, travel and Broadway shows,” he says.
OK, doomer
Encountering post after post about the downsides of the economy contributes to “doomerism”—an overwhelming feeling of despair. This has made some young adults thrifty.
“I’m not going to spend my last dollar to keep up with the Joneses,” says Tanayah Thomas, a 23-year-old clothing designer and licensed financial adviser in Staten Island, N.Y. “We have to prepare for what’s to come.”
She’s currently living with her mom to save money.
Tommy Chanthavong, a 27-year-old in Houston who manages social-media accounts for small, local businesses, also moved back home. He says it’s hard to parse the information shown on TikTok: One minute he sees videos saying the U.S. is on the brink of a recession and the next he sees that inflation is easing.
In The Wall Street Journal’s latest quarterly survey of business and academic economists , respondents lowered the chances of a recession within the next year to 29% from 39% in January—the lowest probability since April 2022.
Sprinkle, who shares an apartment with a roommate, says she’d love to own a house one day, but it feels like a distant dream.
“You have to have a level of happiness, and being able to do the things you want and buy the things you want is part of it,” she says. “Do I save all of my money for the future? No. I try to live more in the moment.”
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
By Laura Saunders
Fri, Oct 9, 2026 4min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.


 5 min

 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



