Do you get unsolicited text messages from people you don’t know? Be forewarned: If you respond, you could be falling for a particularly dangerous online scam that has found victims around the world. Some unfortunate individuals have lost millions of dollars.
There is even a name for it. Pig butchering. Victims are fattened up, made to trust the scammer and think they are making tons of money, until they are mercilessly taken—sometimes for everything they have.
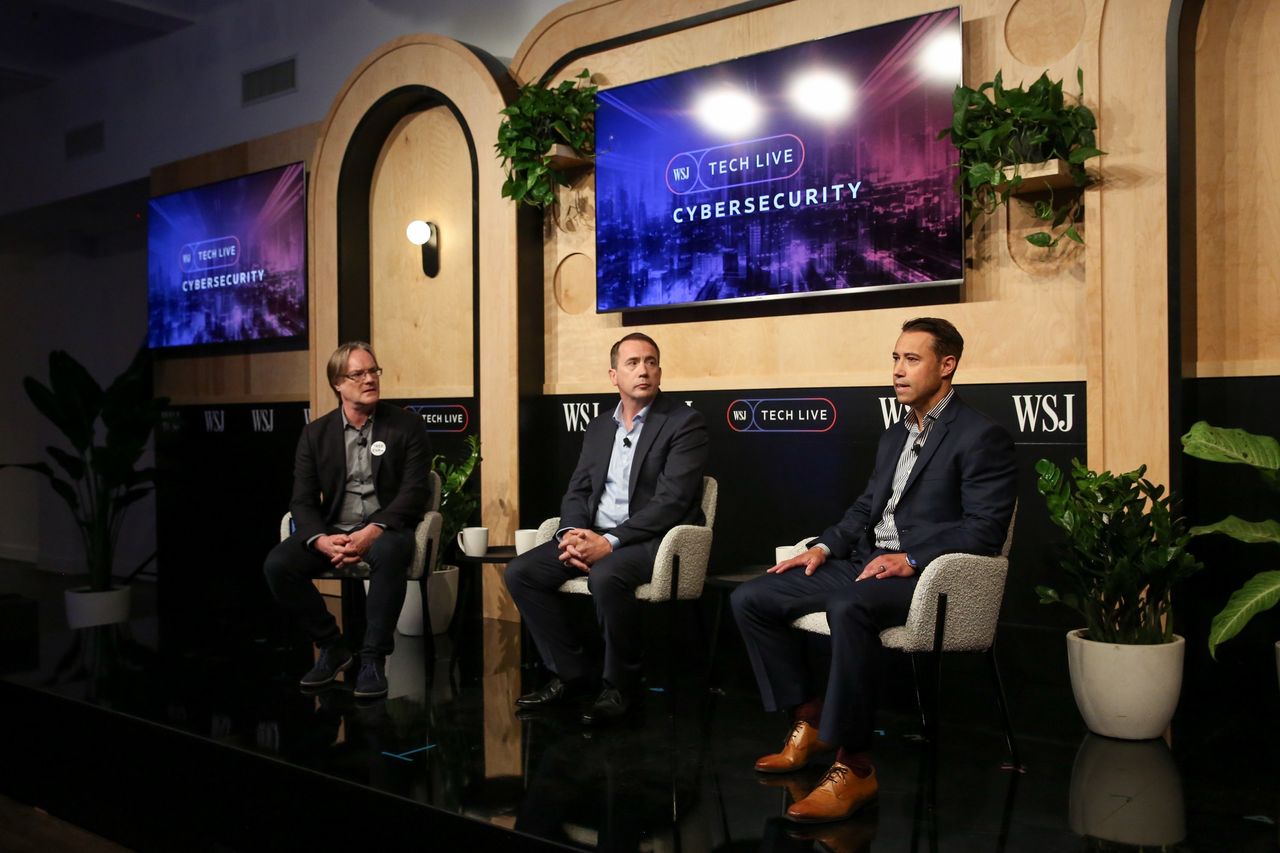
On June 6, at the WSJ Tech Live: Cybersecurity conference in New York City, two cybercrime experts sat down with Wall Street Journal reporter Robert McMillan to discuss how pig butchering works and what is being done about it. The participants were Troy Gochenour, an investigator with the Global Anti-Scam Organization, a nonprofit that helps victims and raises public awareness of scams, and Jamil Hassani, a supervisory special agent with the Federal Bureau of Investigation. An edited transcript of their conversation follows.
How the scam works
WSJ: Why “pig butchering”?
GOCHENOUR: It’s not our term. In Chinese, it is shā zū pán , or pig-killing plate. What makes this scam so effective is they want to build trust so that you might think they could be a potential love interest or a business partner. Once they built that trust, then they will start talking about how they’ve made a lot of money in cryptocurrencies and how the victim could, too.
WSJ: It’s a variation on the romance scam. Instead of asking for money to buy a plane ticket, they propose to make money together?
HASSANI: Absolutely. The rise in cryptocurrency has opened the door for these scammers to take your money instantaneously. There are no third parties doing the reconciliation. If you do a regular wire transfer and you contact the FBI within 72 hours, chances are we can get that money back for you. But with crypto, it’s almost immediate and it’s gone.
WSJ: Are you seeing more pig butchering because of the rise of crypto?
HASSANI: Absolutely. The rise since 2019 for victimisation is almost 2,000%.
WSJ: Why does it work?
GOCHENOUR: The social-engineering aspect is very powerful. I have stories that are very sad: folks who have been warned that they’re getting scammed, and yet, because they’ve been socially engineered so much, they actually continue to invest.
They’re looking for everybody, but they prefer people with titles—doctor, dentist, IT professional, CEO. I follow them on the communications platform Telegram, so I have a lot of their training documents, manuals on how they build those relationships. This is an entire industry tied to largely Chinese organised crime.
The victim’s psychology
WSJ: Jamie, psychologically speaking, why does this work?
HASSANI: I remember arresting a hacker out of Tunisia. A 19-year-old kid that was able to bypass levels of security within the Department of Defense, took down a few banks and was wreaking havoc across the world. He explained to me: “Hackers are stupid. They go after the systems, when human beings have way more vulnerabilities. They have the keys to the treasure chest. And it’s so easy to turn off their mental firewall.”
Try to think of a time you were in a relationship where the threat of your spouse or significant other leaving caused you to do pretty much anything to keep them around. Every scam evokes an emotion. It could be love, fear, panic. Your ability to critically think is shut off.
WSJ: Sometimes when I’ve talked to scam victims, it’s like the more they have invested, the harder it is for them to believe they have been taken.
HASSANI: It’s the stigma. The victims can’t fathom that they could have been so stupid, quote unquote. So they hold on to this hope that it had to have been real, the love had to have been there, or the trust, because they’re texting every day, 30 to 100 times. The scammers use information they glean from your communications and social media to validate you in a way that no one else can.
WSJ: If you suspect or know somebody is a victim, is there something you can say that will snap them out of it?
GOCHENOUR: Unfortunately, people are people. We’ve had victims we’ve warned more than once, and they continued to give.
The United Nations Office on Drugs and Crime says there could be as many as a couple hundred thousand of these scammers operating throughout Southeast Asia.
HASSANI: A lot of these scammers are trafficked human beings. When a human being is subjected to that kind of circumstance, their will to succeed is intense, because their life, or their family’s life, depends on it. They are constantly fine-tuning strategies, and trying to stay one step ahead of whoever is closest on their tail. These scammers contribute something like half of their country’s GDP, so the local government’s not going to do much.
WSJ: The FBI knows who’s running these scams, largely?
HASSANI: Yes, absolutely.
WSJ: Can you get them?
HASSANI: There are no treaties between those specific countries and the U.S. We’ve taken steps. We work with multiple organizations, including the Secret Service, Department of Homeland Security, and we’re applying pressure on these countries to start to take action.
The first approach
WSJ: There are different layers of operators; some do the texting, others do the talking and then there are the video calls.
GOCHENOUR: Sure. So if you get that wrong number, the text to your phone, you respond, saying wrong number. I’m not Paul. Jane. Whoever. They say, oh, so sorry. Uh, my assistant gave me your number. I hope I’m not bothering you.
Sometimes they even send you a picture. That sounds interesting. So you continue to talk. Oh, what’s your name? Where do you live? What do you do?
They’re looking for a weakness. Are you single? Oh, weakness might be romance. Oh, you’re in business. I could be your business partner. But they also want to know what kind of assets they can take from you.
On their Telegram pages, I’ve seen screenshots of their chats. They can chat in Chinese, and it shows up to you as your native language. And when you chat back it shows up to them in Chinese. At the top, it would say your first name, maybe your age, two homes, 401(k).
As you continue to chat, you’re actually being sent to multiple people chatting with you on this one account. You may not even recognize it. They are all in the compound. Everything they do is monitored. So if that person is there against their will, if they don’t chat with you to lure you in, they could get beaten.
What can be done?
WSJ: This scam involves legitimate organizations as well, right? Cryptocurrency companies, the messages come on legitimate apps. What can be done to mitigate this?
HASSANI: Until a collective strategy is put together, you need to be aware of the red flags. And the first one is unsolicited contact. We’ve all gotten that text message, “hi.” That message has a fundamentally different feeling to somebody who is elderly and widowed and lonely. When they see “hi,” that has a profound impact on them.
If you get an unsolicited contact, ask questions. If they want you to invest in cryptocurrency, do a little research on the site. Is this website legit? Some are legitimate and registered with, say, the Treasury Department’s Financial Crimes Enforcement Network or the Securities and Exchange Commission.
WSJ: Some of the scam sites actually register.
HASSANI: True. Most of them aren’t registered with the SEC, but a lot are.
GOCHENOUR: In 2021, 2022, they were using apps like MetaTrader 5 or 4, a foreign-exchange trading app. It’s legitimate. You could go on this app and think you’re doing something legitimate, but you’re sending money to their scam broker website.
WSJ: Why can’t you stop these guys?
HASSANI: They’ll have one major domain with multiple subdomains, so to speak. So as soon as we take that website down, another one pops up. Our strategy is to go after the kingpin.
WSJ: Have you hit any kingpins yet?
HASSANI: We have. The indictments, a lot of them are still under seal. But tech-support scams are a big part of this. We took down three tech-support buildings near Kolkata less than a year ago.
WSJ: All connected to pig butchering?
HASSANI: Yes, and they do the same thing—traffic human beings to scam.
WSJ: Scammers use services like WhatsApp, and the money gets sent to them often through a legit crypto company. Could the tech companies be doing more here?
GOCHENOUR: The tech companies and the exchanges are doing more. And I know that because when I follow the scammers on their chats, they talk about, “Why can’t I get this money? The victim put it in the account, but I can’t get it. What’s going on?”


 5 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



