
Bitcoin Mining Is Big in China. Why Investors Should Worry.
Why the digital currency’s dependence on China, specifically Xinjiang, is concerning.

By Isaac Stone Fish
Wed, Feb 24, 2021 1:27am 3 min
3 min


Why the digital currency’s dependence on China, specifically Xinjiang, is concerning.
3 min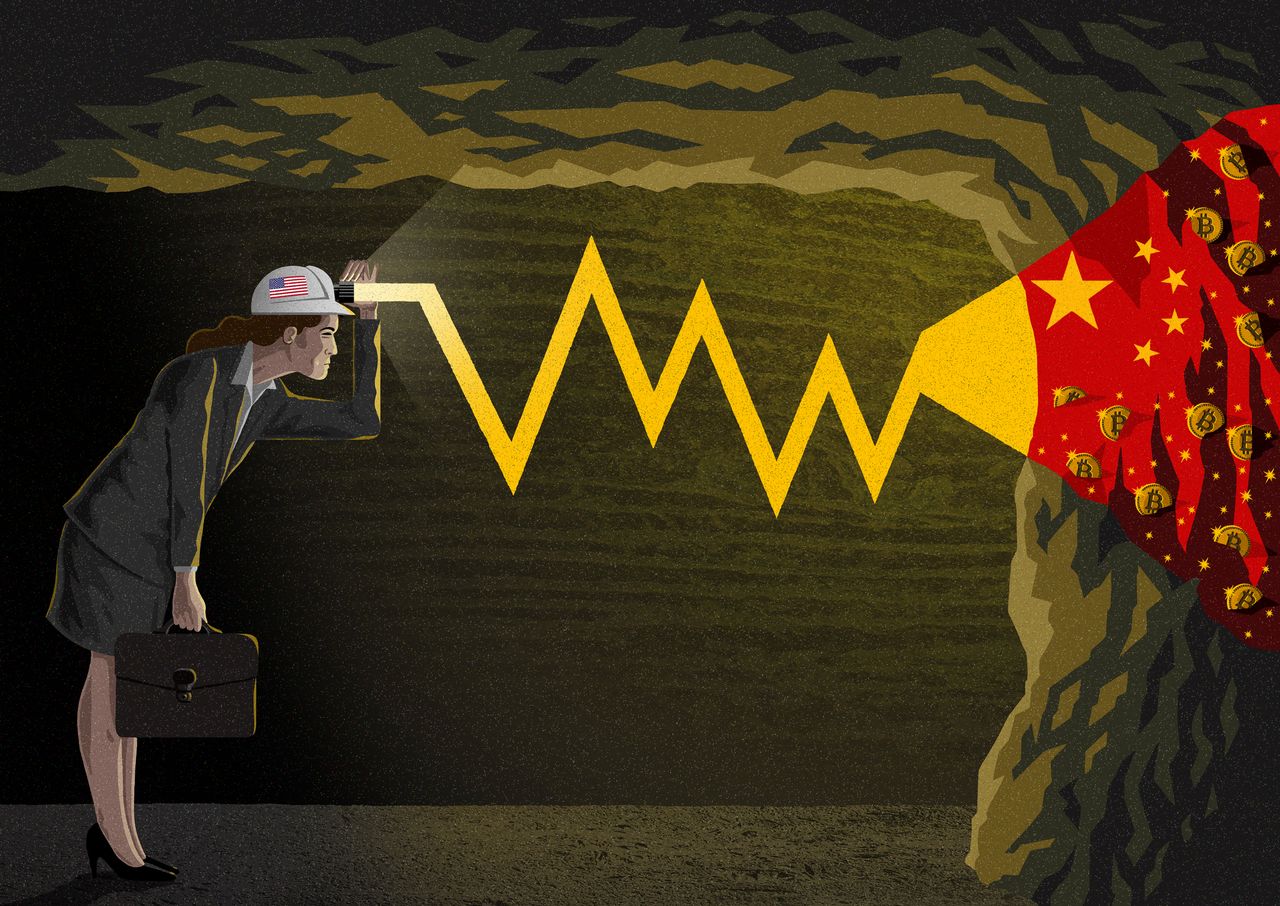
Critics of the nearly ubiquitous digital currency Bitcoin often focus on its environmental consequences. After Tesla announced recently that it had bought roughly US$1.5 billion in Bitcoin, sending the cryptocurrency’s value skyrocketing, sustainability investors decried the “level of carbon dioxide emissions generated from Bitcoin mining.” Certainly, “mining”—the energy-intensive process by which computers solve complex algorithmic problems to verify blockchain transactions, for which they’re rewarded in digital currency—is an undeniable environmental offender.
But there is another worrying aspect of Bitcoin, one that should make investors think twice about including it as part of an ethical investing strategy.
A large amount of new Bitcoin comes from Xinjiang, the region in northwest China where more than a million Uighur Muslims and other minorities have been imprisoned in concentration camps. According to the Cambridge Bitcoin Electricity Consumption Index, as of April 2020, China was responsible for 65% of all Bitcoin mining. And of that, 36% takes place in Xinjiang, the largest regional component. Why? Cheap coal means cheap energy to power the machines that mine Bitcoin. Xinjiang has an abundant supply of coal, and the region’s relative remoteness means that it’s far cheaper to use the resource locally than move it to other parts of China. The issue is not that the Chinese government uses forced labour in Xinjiang coal mines—the reporting on that is inconclusive. Rather, because of the atrocities occurring in Xinjiang, any product produced there brings with it high ethical and regulatory risk.
In the camps—which Beijing calls “vocational educational and training centres”—guards try to “deradicalise” Uighurs for crimes such as wearing long dresses, abstaining from pork or alcohol, or praying. While the difficulty of reporting in the region means that concrete evidence is scarce, camp survivors have described systemic torture, forced sterilization, and rape. (Beijing denies committing atrocities.) In January, right before leaving office, Secretary of State Mike Pompeo declared that Beijing was committing “genocide” in the region. His successor, Antony Blinken, agrees.
To summarize: Roughly 20% of new Bitcoin is mined in Xinjiang, the site of some of the world’s most egregious human-rights abuses.
Today, Bitcoin’s association with Xinjiang is barely discussed. But that may change. For public-facing funds considering investing in the notoriously volatile asset, there are two other risks to consider. The first is that because of the concern among the American public about human-rights abuses in Xinjiang, holding assets tied to the region comes at the risk of a public relations disaster.
Already, activists have criticised Olympic sponsors for participating in the “genocide Olympics”—the 2022 Beijing Winter Games. Multiyear campaigns to hive Xinjiang off from the global supply chain are already well under way.
In July, more than 190 organizations, including the AFL-CIO, called for clothing brands to end all sourcing from Xinjiang within the next 12 months. (In 2020, roughly 20% of the world’s cotton came from Xinjiang.) It’s not hard to imagine Bitcoin becoming another frontier in their campaigns.
Investors should be alert for regulatory action. Bitcoin’s Xinjiang relationship gives ammunition to those in the U.S. government who may want to further monitor or restrict the transactions. Analysts expect the Biden administration to pay close attention to Bitcoin. In mid-February, Treasury Secretary Janet Yellen criticised the “misuse” of cryptocurrencies in laundering money or funding terrorism. At the same time, Bitcoin’s Xinjiang connection could put it on the radar of the various arms of the Commerce, State, and Defense departments that are seeking to reduce U.S. dependence on physical and digital Chinese goods. If this trend intensifies, the Treasury Department could sanction the Bitcoin mining firms that have large operations in Xinjiang, or issue advisories that it is “studying” Bitcoin’s links to the region—signalling to global financial institutions another risk of holding the cryptocurrency.
In January, U.S. Customs banned the imports of Xinjiang cotton and tomato products and told U.S. companies to get forced labour out of their supply chains. Extricating Bitcoin from Xinjiang could be far more difficult. Unlike, say, blood diamonds or Iranian crude oil, Bitcoins exist only digitally. While there is a public record of the billions of Bitcoin transactions, it’s exceedingly complicated to determine the geographic origin of a particular Bitcoin. That means all Bitcoin holders can deny any connection to human-rights abuses—but also risk being tarnished by the association.
It has long been ironic that Bitcoin, developed to decentralize power, is so dependent on China, a country ruled by a government obsessed with centralizing it. But depending on China is one thing. Depending on Xinjiang is another. There are many excellent ethical and regulatory reasons not to buy Bitcoin. Add Xinjiang to that list.
Isaac Stone Fish is the CEO and founder of Strategy Risks, a firm that quantifies corporate exposure to China.>
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
China’s trade surplus surpassed $1 trillion in the first 10 months of 2026, driven by a 35% annual surge in exports in October. However, the export boom contrasts with weakening domestic demand, as retail sales growth slowed to 0.4%, fixed-asset investment fell 8.1% and property investment dropped nearly 22%, highlighting growing challenges for the world’s second-largest economy.
2 min
China’s trade surplus surged past $1 trillion last month, but at home, its economy is losing steam.
The world’s second-largest economy weakened on several fronts in October, reflecting the country’s split-screen growth. Soaring exports mask tepid consumer spending, falling investment and a real estate slump with no end in sight.
Retail sales, a gauge of household consumption, rose 0.4% last month from a year ago, slowing from 1.1% in September, according to government data released Monday. Fixed-asset investment fell 8.1% in the first 10 months of the year. Property investment alone dropped nearly 22% during the same period.
“The data continue to depict a two-speed economy,” Société Générale economists Michelle Lam and Wei Yao wrote in a report Monday.
External demand has driven much of China’s economic growth this year. Exports rose 35% from a year earlier in October in dollar-denominated terms, according to official data released last week. The country’s trade surplus for the first 10 months of the year reached $1.04 trillion.
The deluge of exports risks further stoking tensions with Beijing’s trade partners, particularly in Europe, where officials increasingly say that competition from China is hollowing out their local industrial sectors. The European Union and Beijing last month agreed to cap shipments of Chinese hybrid vehicles.
Still, global demand for Chinese goods—especially for tech products that power artificial intelligence—appears to show no signs of slowing. China’s exports of integrated circuits more than doubled in value in the first 10 months of the year, government data show.
That reduces the pressure on Beijing to step up support for the economy. China remains on track to hit its growth target for the year of between 4.5% and 5% gross domestic product growth, making it unlikely Beijing would rush to unleash new stimulus.
“Policymakers are likely to continue doing just enough to meet the growth target,” Macquarie economists Larry Hu and Yuxiao Zhang wrote in a report Monday.
Despite the export momentum, China’s industrial production growth decreased to 4.8% last month, from 5.5% growth in September.
The property market remains a drag on the economy. Home sales fell 14.1% in the January to October period from a year ago, widening from a 13.7% decline in the first nine months.
Meanwhile, China’s headline surveyed urban unemployment rate stood at 5.1% last month, roughly in line with September’s 5.2%.
