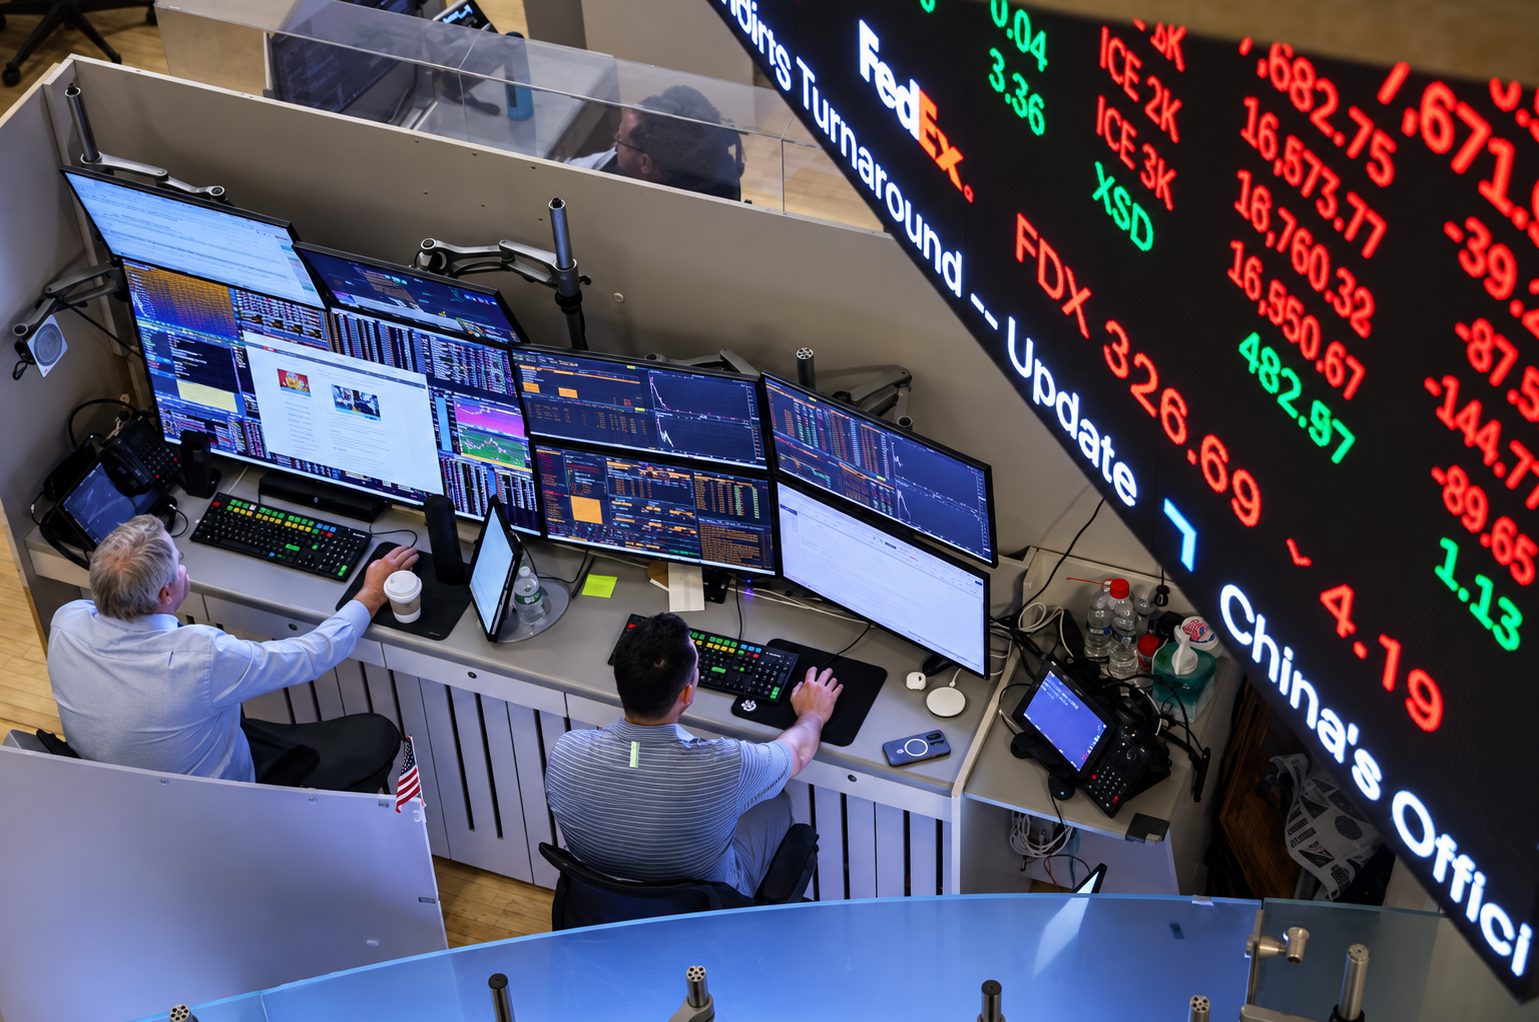
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”


 2 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.