
America’s Billionaires Love Japanese Stocks. Why Don’t the Japanese?
Japan’s government wants cash-hoarding households to invest more

By AKANE OTANI
Mon, Sep 25, 2023 8:56am 3 min
3 min


Japan’s government wants cash-hoarding households to invest more
3 min
TOKYO—Japan’s government is on a mission to make buying stocks hot again.
Many of America’s biggest investors are bullish on Japan. Warren Buffett shared that he increased his investments in Japanese companies during an April visit to the country. Ken Griffin is preparing to reopen an office in Tokyo for his hedge fund, Citadel, and investment banks Goldman Sachs and Morgan Stanley have issued optimistic outlooks for Japan’s stock market.
Japan’s problem is this: There are few signs its estimated 125 million residents share in the excitement.
Burned by dismal returns since the bursting of Japan’s asset bubble in the late 1980s and early 1990s, generations of families here have stashed most of their money in low-yielding savings accounts rather than trying to increase their wealth through the stock market.
Japanese households put an average of just 11% of their savings into stocks and 54% in cash and bank deposits, according to Bank of Japan data released last month. That trails well behind the U.S., where households have about 39% of their money tied up in the market and only 13% in cash and bank deposits, according to Federal Reserve data.
Haruyo Arai, a 62-year-old office worker, began investing in the stock market just last month.
“I was brought up by parents who would say, ‘Don’t dabble in stocks,’ ” she said.
Japanese Prime Minister Fumio Kishida has pledged to double households’ asset incomes, in part by encouraging people to invest in risky assets like stocks. The government is raising caps for Japan’s tax-exempt investment system for small investors, the Nippon Individual Savings Account, with changes set to take effect in January. The Tokyo Stock Exchange has been urging companies to boost their valuations and increase shareholder returns.
Arai cited the upcoming expansion to NISA, along with a desire to save more money for the future, as some of the reasons she decided to begin taking investing more seriously. She has been taking weekend classes at Tokyo-based Financial Academy to learn more about stocks and waking up early every morning to watch a TV news program focused on the economy.
Some believe investors like Arai will prove to be the exception, not the rule. Stocks here haven’t hit a record in decades. There isn’t much buzz among ordinary people about investing in Japanese markets.
“I’ve got the impression that Japanese people don’t really think positively about the desire to make money,” said Takashi Kawaguchi, a 48-year-old office worker who, like Arai, has been learning about investing at Financial Academy.
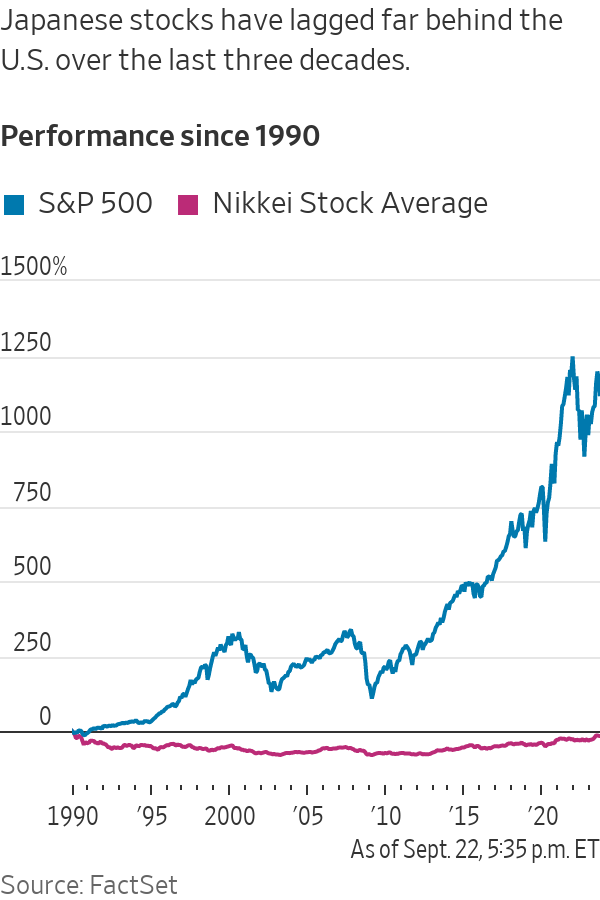
While the 2023 rally has helped lift Japanese stock indexes to 33-year highs, long-term returns pale in comparison to what an investor would have gotten by investing in U.S. stocks. The Nikkei closed at 32,402 on Friday, still 17% below its record hit in 1989. The S&P 500 has grown more than twelvefold over that time. That has made many investors here turn to foreign markets instead of focusing their bets within Japan.
“The Nikkei might hit 40,000, god knows when,” said Heihachiro “Hutch” Okamoto, foreign equity consultant at retail brokerage Monex. “But most of our investors prefer U.S. stocks.”
To Okamoto’s point, the most popular names traded on Monex daily aren’t Japanese stock indexes like the Topix or Nikkei, brand-name companies like Sony or even the “sogo shosha”—the trading houses that Buffett has invested in. Instead, they are all American names: companies like Nvidia, Tesla, Apple and Amazon.com, as well as funds tracking the S&P 500 and the Nasdaq-100.
And that is just among those interested in investing in the first place. While in past years, everyday investors in Japan made a name for themselves with their forays into the foreign exchange market, the overall trading culture here has been one of hesitation.
“Most people here think investing is very risky,” said Hidekazu Ishida, a special adviser at FinCity.Tokyo, which works with the government and the financial industry to try to boost investment in Tokyo. Being into finance comes off as “kakkowarui,” he added, referencing a word for uncool.
Even some heads of companies are lukewarm about the idea of encouraging more individual investors to buy Japanese stocks.
“I’m neutral about that,” said Takeshi Niinami, chief executive officer of whisky and beverage giant Suntory, when asked if he thought it would be a good idea for more Japanese people to invest in the market. Stock investing is risky, he said. And many Japanese people remain wary of participating in the market, because of the severity of prior downturns.
“I think perhaps increasing interest rates is better for people,” he said.
—Chieko Tsuneoka and Alastair Gale contributed to this article
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
