
Bitcoin Mining Is Big in China. Why Investors Should Worry.
Why the digital currency’s dependence on China, specifically Xinjiang, is concerning.

By Isaac Stone Fish
Wed, Feb 24, 2021 1:27am 3 min
3 min


Why the digital currency’s dependence on China, specifically Xinjiang, is concerning.
3 min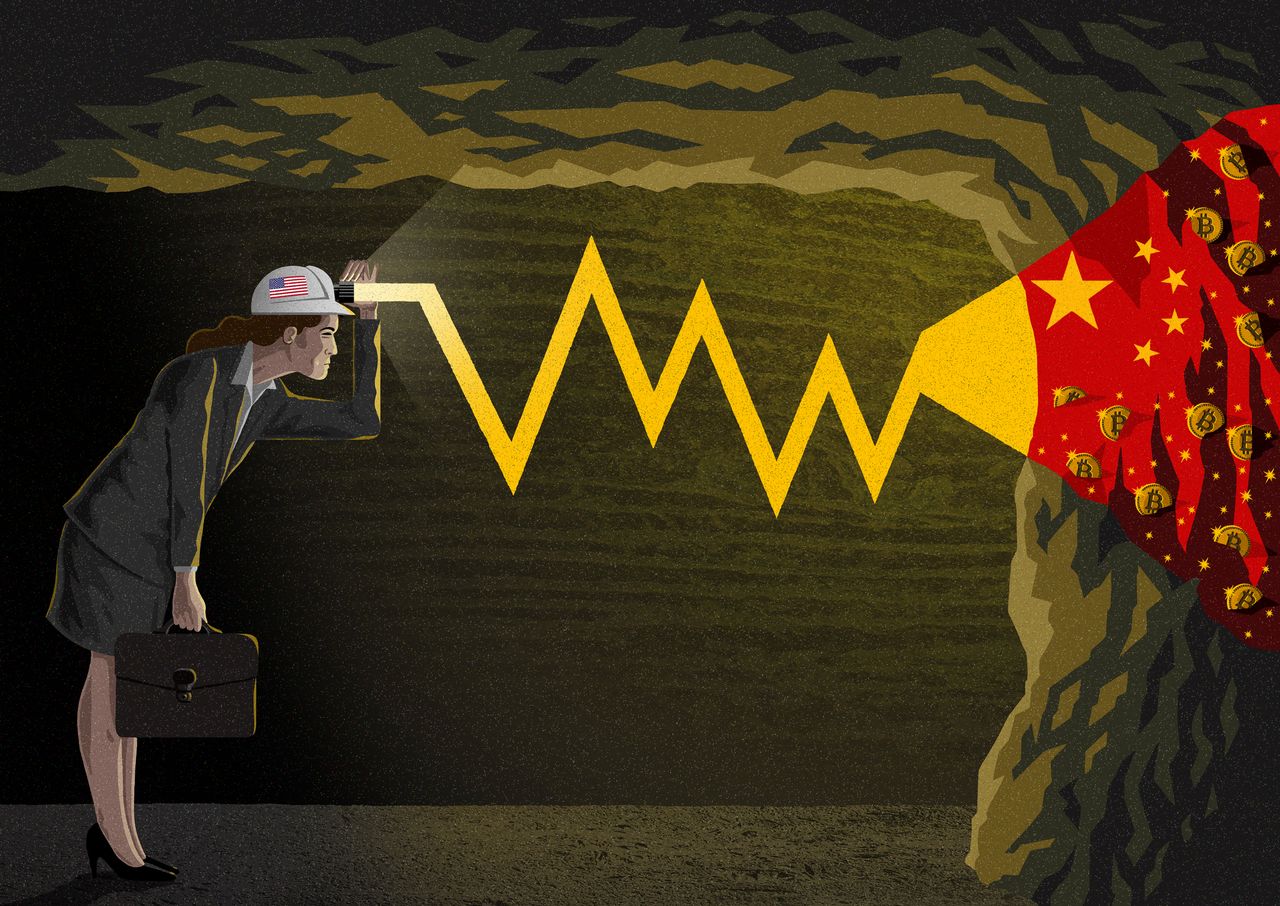
Critics of the nearly ubiquitous digital currency Bitcoin often focus on its environmental consequences. After Tesla announced recently that it had bought roughly US$1.5 billion in Bitcoin, sending the cryptocurrency’s value skyrocketing, sustainability investors decried the “level of carbon dioxide emissions generated from Bitcoin mining.” Certainly, “mining”—the energy-intensive process by which computers solve complex algorithmic problems to verify blockchain transactions, for which they’re rewarded in digital currency—is an undeniable environmental offender.
But there is another worrying aspect of Bitcoin, one that should make investors think twice about including it as part of an ethical investing strategy.
A large amount of new Bitcoin comes from Xinjiang, the region in northwest China where more than a million Uighur Muslims and other minorities have been imprisoned in concentration camps. According to the Cambridge Bitcoin Electricity Consumption Index, as of April 2020, China was responsible for 65% of all Bitcoin mining. And of that, 36% takes place in Xinjiang, the largest regional component. Why? Cheap coal means cheap energy to power the machines that mine Bitcoin. Xinjiang has an abundant supply of coal, and the region’s relative remoteness means that it’s far cheaper to use the resource locally than move it to other parts of China. The issue is not that the Chinese government uses forced labour in Xinjiang coal mines—the reporting on that is inconclusive. Rather, because of the atrocities occurring in Xinjiang, any product produced there brings with it high ethical and regulatory risk.
In the camps—which Beijing calls “vocational educational and training centres”—guards try to “deradicalise” Uighurs for crimes such as wearing long dresses, abstaining from pork or alcohol, or praying. While the difficulty of reporting in the region means that concrete evidence is scarce, camp survivors have described systemic torture, forced sterilization, and rape. (Beijing denies committing atrocities.) In January, right before leaving office, Secretary of State Mike Pompeo declared that Beijing was committing “genocide” in the region. His successor, Antony Blinken, agrees.
To summarize: Roughly 20% of new Bitcoin is mined in Xinjiang, the site of some of the world’s most egregious human-rights abuses.
Today, Bitcoin’s association with Xinjiang is barely discussed. But that may change. For public-facing funds considering investing in the notoriously volatile asset, there are two other risks to consider. The first is that because of the concern among the American public about human-rights abuses in Xinjiang, holding assets tied to the region comes at the risk of a public relations disaster.
Already, activists have criticised Olympic sponsors for participating in the “genocide Olympics”—the 2022 Beijing Winter Games. Multiyear campaigns to hive Xinjiang off from the global supply chain are already well under way.
In July, more than 190 organizations, including the AFL-CIO, called for clothing brands to end all sourcing from Xinjiang within the next 12 months. (In 2020, roughly 20% of the world’s cotton came from Xinjiang.) It’s not hard to imagine Bitcoin becoming another frontier in their campaigns.
Investors should be alert for regulatory action. Bitcoin’s Xinjiang relationship gives ammunition to those in the U.S. government who may want to further monitor or restrict the transactions. Analysts expect the Biden administration to pay close attention to Bitcoin. In mid-February, Treasury Secretary Janet Yellen criticised the “misuse” of cryptocurrencies in laundering money or funding terrorism. At the same time, Bitcoin’s Xinjiang connection could put it on the radar of the various arms of the Commerce, State, and Defense departments that are seeking to reduce U.S. dependence on physical and digital Chinese goods. If this trend intensifies, the Treasury Department could sanction the Bitcoin mining firms that have large operations in Xinjiang, or issue advisories that it is “studying” Bitcoin’s links to the region—signalling to global financial institutions another risk of holding the cryptocurrency.
In January, U.S. Customs banned the imports of Xinjiang cotton and tomato products and told U.S. companies to get forced labour out of their supply chains. Extricating Bitcoin from Xinjiang could be far more difficult. Unlike, say, blood diamonds or Iranian crude oil, Bitcoins exist only digitally. While there is a public record of the billions of Bitcoin transactions, it’s exceedingly complicated to determine the geographic origin of a particular Bitcoin. That means all Bitcoin holders can deny any connection to human-rights abuses—but also risk being tarnished by the association.
It has long been ironic that Bitcoin, developed to decentralize power, is so dependent on China, a country ruled by a government obsessed with centralizing it. But depending on China is one thing. Depending on Xinjiang is another. There are many excellent ethical and regulatory reasons not to buy Bitcoin. Add Xinjiang to that list.
Isaac Stone Fish is the CEO and founder of Strategy Risks, a firm that quantifies corporate exposure to China.>
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
