
Chasing Passive Income, Americans Turn to Vending Machines
How candy and soda machines became an unlikely trending investment idea of the 2020s

By JOE PINSKER
Mon, Mar 11, 2024 9:08am 5 min
5 min


How candy and soda machines became an unlikely trending investment idea of the 2020s
5 min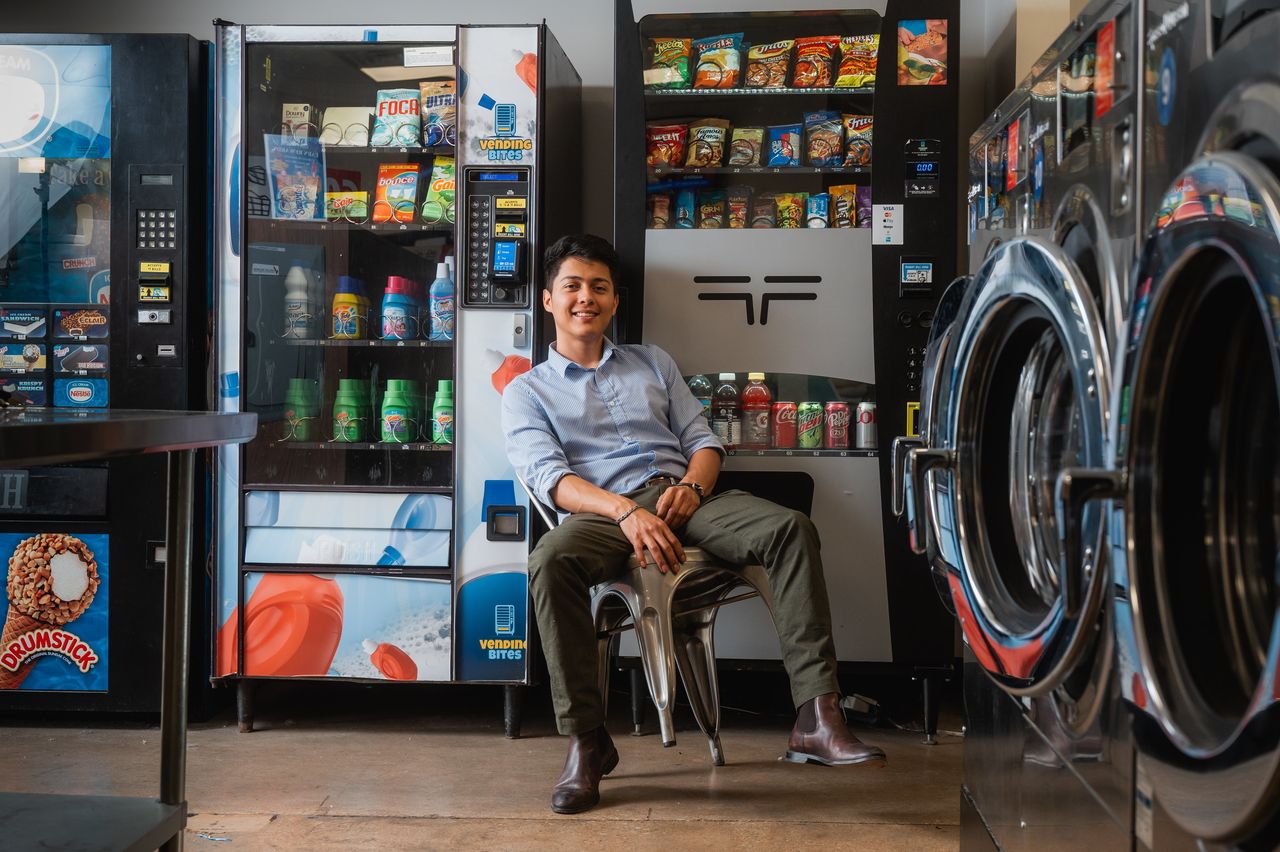
With a brick of cash in his hand and a grin on his face, Jaime Ibanez shows his half-million YouTube subscribers a path to earning money without burning many calories: Vending machines.
In videos with titles such as “This Is HOW MUCH My Vending Machines Made IN 7 DAYS!!” the swoopy-haired 23-year-old Texan makes the rounds to his 51 machines, stocking them and taking the profits.
His channel promotes the idea that with diligence and luck, anyone can go from snacks to riches.
Vending machines might seem an unlikely candidate for trending investment of the 2020s, but the idea has captured the imagination of Americans dreaming of easier money. Some pursue chips and soda as a side hustle because their regular paychecks aren’t enough for them to get by. Others bet on vending machines as a ticket to upward mobility, to quitting their jobs and becoming their own boss.
The startup cost is low and the formula simple. Buy a used machine for $1,500, load it up with products from Costco , charge a 100% markup and let the crinkled dollars roll in. But turning a profit takes real work, and the machines can be a losing proposition when stuck in locations without enough hungry foot traffic.
There is a fair amount of competition, too. America has three million vending machines, an $18.2 billion industry, with the average machine generating about $525 in monthly revenue, according to the National Automatic Merchandising Association.
More than half of operators bring in less than $1 million a year, according to trade publication Automatic Merchandiser. Many are individuals who have other jobs.
Social media has fuelled the notion of finding financial freedom in vending machines. Between 2019 and 2023, the number of posts or comments mentioning passive income and vending machines more than tripled on X and increased by a factor of six on Instagram, according to Sprinklr, a social-media management platform. Google search interest in passive income increased some 75% during that same period.
“There’s a real sense that doing things the so-called right way won’t necessarily land you in the middle class,” said Lana Swartz, a media-studies professor at the University of Virginia who researches financial technologies. “If the old rules no longer apply, then there’s a searching for new rules to get ahead or to get by.”
Some vending-machine newbies say they are on their way to building an automated empire. Others’ dreams get snagged like a bag of Funyuns on a faulty coil.
Last spring Rob Smith, a 30-year-old truck driver in Orlando, Fla., spent $4,000 on his first machine, a credit-card reader and a load of snacks and drinks.
He recently acquired his fourth machine, which is at an industrial bakery. His first three machines take up three to five hours of his week and bring in about $1,500 a month in revenue, which works out to roughly $750 in profit.
“I’ve made sales at four o’clock in the morning, when I was sleeping,” he said. “That machine is still working whether I’m there or not.”
He hopes to scale up to 30 machines and quit his job.
Smith started looking for extra income because his goal of buying a house felt out of reach with only his day job’s pay. He chose vending specifically after he witnessed a colleague complain about a malfunctioning machine at work and then use it anyway.
“He still put his $2 in,” Smith said. “I was like, ‘I need to get a vending machine as soon as possible.’ ”
Some budding vendors pay $300 or more for online courses to learn the trade. Smith relied on YouTube, Instagram and Reddit to get going.
At one point, he stocked a machine with orange soda against the advice he got in an online forum. When it didn’t sell, he and his family had to drink three dozen cans themselves.
Tom and Missi Hakes of Midway, Ala., started vending after Missi, 40, saw videos on YouTube about the business. The idea seemed more appealing than their stints driving for Uber, shopping for Instacart and trying to make it as YouTubers.
The Hakes, who both have full-time jobs in health insurance, scouted out locations in Atlanta, the closest big city and two hours away. After their best lead fell through, they paid a woman they found on Facebook Marketplace $500 to find a location for them.
She sent them to two spots that didn’t work out, including a cheerleading gym. The manager there was on board until she learned that the Hakes hadn’t operated a vending machine before.
Tom, 48, posted on a forum wondering how to address questions about their industry experience. At their next meeting, with the owner of a gym, they reluctantly followed some of the forum’s advice: They lied and said they had a few machines.
“We didn’t want to get another no,” said Tom.
He then spent a month repairing a used machine they bought for $1,400, staying up on some nights until 2 a.m.
When it was ready, Tom and Missi struggled to wrangle it into the 15-foot U-Haul truck they rented.
“Two people is not enough to move an 800-pound machine,” she said.
The Hakes spent about $2,500 on their vending business, as well as 20 to 30 hours a week for much of last fall.
They pay $50 a month to park it in the gym and it costs about $330 to fill up. It is currently grossing about $30 a week.
If anything, the income has been too passive, Tom said, “because it’s not really doing a lot of sales.”
If the machine isn’t selling more by summer, the Hakes will consider leaving the location, or perhaps vending machines overall.
Used vending machines of questionable quality sell online for as little as $500. More reliable ones cost in the range of $1,000 to $2,000, according to veteran vendors. A new machine with a touch screen and a robotic arm could cost upward of $7,000.
Many used machines have a maintenance issue about once a year, and they need to be cleaned. Cash is dirty, said Ben Gaskill of Everest Ice and Water Systems, a vending-machine maker. “Somebody digs around for coins in the bottom of their purse and it’s got grape jelly on it.”
Vendors shop warehouse stores like Costco and Sam’s Club to stock up. One machine’s worth of snacks or drinks can cost $200 to $300 a month. Owners then charge about twice what they paid for each product, or more. Prices of food from vending machines were up 10.6% year over year in January, according to Labor Department data.
The top-selling items in vending machines are cold drinks, snacks and candy, according to the latest data from Automatic Merchandiser magazine.
“No matter how healthy you try to make the machines, people are going to buy that Snickers bar,” said Lory Strickland, who sells courses and one-on-one coaching with her husband, Barry, under the name The Vending Mentors.
Selling online classes and coaching can sometimes be more lucrative than a given moneymaking idea itself, said Swartz, the University of Virginia professor.
In online forums, she said, “there’s the joke that if there are people making courses about it, then it’s already oversaturated as a side hustle.”
To capitalise on interest in vending, some experienced operators started selling their expertise to supplement the income coming in from their machines. Some transitioned primarily to training.
Hyping the vending-machine dream predates the internet, though. The first machines in the U.S. sold gum and appeared on train platforms in 1888.
In the 1940s, media outlets cautioned about “get-rich-quick schemes” promoted by “unscrupulous agents involving vending machines.” In 1960, the magazine now known as Kiplinger Personal Finance warned of “vultures in the business” who promised “that an $800 investment may produce $200 a month, and that only a few hours of work a week are required to enjoy such rich pickings.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
