
Cheap Chinese Goods Are Becoming a Costly Problem. Exhibit A: Hong Kong.
Shoppers are hopping across the border after a prolonged decline in prices

By CLARENCE LEONG
Thu, Feb 22, 2024 9:05am 3 min
3 min


Shoppers are hopping across the border after a prolonged decline in prices
3 min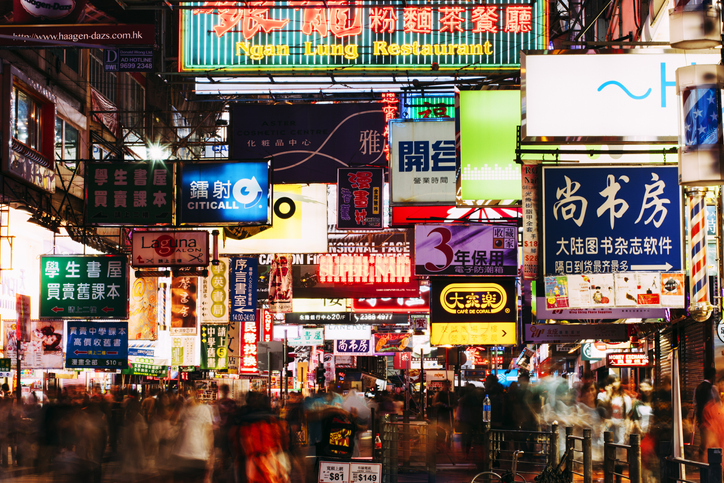
Prices are falling in mainland China. That’s a boon for people living in Hong Kong, but a big problem for the city’s businesses.
Consumer prices in China fell 0.8% in January compared with a year earlier, the country’s biggest deflation reading in more than a decade. That is a sign of the tepid state of the world’s second-largest economy, where a sputtering recovery has knocked confidence and encouraged Beijing to censor some economic research .
Hong Kong residents are increasingly hopping across the border to the city of Shenzhen, where they load up on frozen food and cheap furniture at big-box stores such as Costco and Sam’s Club. Hong Kong business owners, unable to compete with their Chinese counterparts on price, are feeling the squeeze.
“Walking on the streets these days, you’ll feel that Hong Kong retailers are in big trouble,” said the city’s former financial secretary, John Tsang, in a recent social-media post.
The pain being felt by businesses in Hong Kong offers a partial answer to a question that has been debated by economists for much of the past year: How will deflation in China affect the rest of the world?
Chinese export prices have dropped steadily since late 2022 and were 8.4% lower in December than they were a year earlier, according to customs data. Economists think that’s probably a good thing for Europe and the U.S., where central banks have been forced to embark on an aggressive series of interest-rate increases to keep rising prices in check. But the impact on smaller countries could be more troublesome.
China is the biggest trading partner for many countries across the world, and is particularly influential for countries in Asia. The risk for them is that Chinese companies dump their goods overseas in response to weak demand at home. They can also undercut manufacturers in countries such as Vietnam and Malaysia, which have slowly been muscling in on China’s status as the world’s factory.
“This Hong Kong story is applicable to countries that are near the neighbourhood of China because the supply chain is much smaller,” said William Lee , chief economist at the Milken Institute, an economic think tank. The shorter supply chain for China’s trade with its neighbours means changes in price pass through more directly, rather than being swallowed up by the various companies that get involved in shipping goods over longer distances.
China’s neighbours in East Asia don’t have the option to impose protectionist policies against it, analysts at Citigroup wrote in a January note. China is simply too big a force in global trade for them to risk its ire.
But if it is hard for China’s neighbours to push back against falling prices, it is even tougher for Hong Kong—which is run by a pro-Beijing government that wants closer integration with the superpower next door.
Hong Kong residents are partly benefiting from the strength of the U.S. dollar. The Hong Kong dollar is pegged to the U.S. dollar, and the city’s de facto central bank has copied the Federal Reserve’s series of interest-rate increases over the past two years. China’s central bank has gone in the opposite direction, cutting rates in an attempt to boost the moribund economy.
Since the end of 2021, the Chinese yuan has lost more than 11% of its value against the Hong Kong dollar.
Hong Kong’s economy grew 3.2% last year, clawing back some lost ground after a 3.7% contraction in 2022. But the numbers mask a host of difficult problems, including an exit of foreign businesses , a prolonged slump in the real-estate sector and the lowest fertility rate in the world .
The apparent embrace of what mainland China had to offer would have appeared unthinkable five years ago, when the city was swept up in antigovernment protests. Back then, shoppers and diners looked up color-coded maps to help them identify businesses that shared their political stance to patronize—and avoided those perceived as having links to mainland China.
But years spent cooped up in Hong Kong during the pandemic and penny-pinching by anxious residents have helped boost Shenzhen’s appeal.
“We’re seeing a readjustment of our way of life that suggests economic interdependency between Hong Kong and Shenzhen,” said Edmund Cheng, a political sociology professor at the City University of Hong Kong.
Last year, Hong Kong residents made more than 50 million trips up north following the lifting of all pandemic-related travel restrictions in February, according to Hong Kong Immigration Department data. That’s still below pre pandemic levels, but the Hong Kong residents’ spending power helped boost retail sales in Shenzhen, which rose by 7.8% in 2023, recording one of the biggest jumps at any mainland city last year.
In a survey by a business lobby last year, just 37% of Hong Kong businesses said they expected revenue to grow in 2024. Less than a third thought they were on track to beat pre pandemic levels.
Korsy Lee, 39 years old, is one of many Hong Kong residents who make a regular pilgrimage to Shenzhen—and earns a profit from it. He began shuttling goods back from Shenzhen last August as a side hustle, and now goes there four times a week, loading up his Toyota minivan with frozen hamburgers, fish maw soup, Panasonic dishwashing machines and even toilet-paper rolls. He takes orders from customers and charges a flat fee.
“Eighty percent of my customers are housewives who want to make every penny count,” he said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
