
China Creates Its Own Digital Currency, a First for Major Economy
A cyber yuan stands to give Beijing power to track spending in real-time.

By James. T. Areddy
Tue, Apr 6, 2021 11:08am 8 min
8 min


A cyber yuan stands to give Beijing power to track spending in real-time.
8 min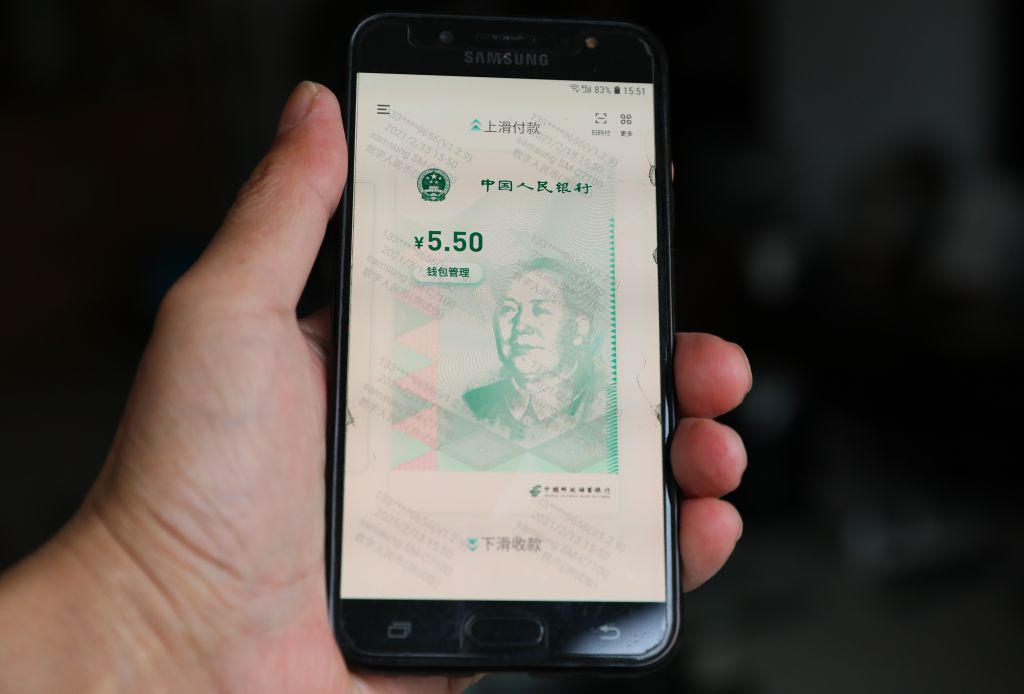
A thousand years ago, when money meant coins, China invented paper currency. Now the Chinese government is minting cash digitally, in a re-imagination of money that could shake a pillar of American power.
It might seem money is already virtual, as credit cards and payment apps such as Apple Pay in the U.S. and WeChat in China eliminate the need for bills or coins. But those are just ways to move money electronically. China is turning legal tender itself into computer code.
Cryptocurrencies such as bitcoin have foreshadowed a potential digital future for money, though they exist outside the traditional global financial system and aren’t legal tender like cash issued by governments.
China’s version of a digital currency is controlled by its central bank, which will issue the new electronic money. It is expected to give China’s government vast new tools to monitor both its economy and its people. By design, the digital yuan will negate one of bitcoin’s major draws: anonymity for the user.
Beijing is also positioning the digital yuan for international use and designing it to be untethered to the global financial system, where the U.S. dollar has been king since World War II. China is embracing digitization in many forms, including money, in a bid to gain more centralized control while getting a head start on technologies of the future that it regards as up for grabs.
“In order to protect our currency sovereignty and legal currency status, we have to plan ahead,” said Mu Changchun, who is shepherding the project at the People’s Bank of China.
Digitized money could reorder the fundamentals of finance the way Amazon.com Inc. disrupted retailing and Uber Technologies Inc. rattled taxi systems.
That an authoritarian state and U.S. rival has taken the lead to introduce a national digital currency is propelling what was once a wonky topic for cryptocurrency theorists into a point of anxiety in Washington.
Asked in recent weeks how digitized national currencies such as China’s might affect the dollar, Treasury Secretary Janet Yellen and Federal Reserve Chairman Jerome Powell have said the issue is being studied in earnest, including whether a digital dollar makes sense someday.
The dollar has faced challengers before—the euro, to name one—only to grow more important when rivals’ shortcomings became apparent. The dollar far outstrips all other currencies for use in international foreign-exchange trades, at 88% in the latest rankings from the Bank for International Settlements. The yuan was used in just 4%.
Digitization wouldn’t by itself make the yuan a rival for the dollar in bank-to-bank wire transfers, analysts and economists say. But in its new incarnation, the yuan, also known as the renminbi, could gain traction on the margins of the international financial system.
It would provide options for people in poor countries to transfer money internationally. Even limited international usage could soften the bite of U.S. sanctions, which increasingly are used against Chinese companies or individuals.
Josh Lipsky, a former International Monetary Fund staffer now at the Atlantic Council think tank, said, “Anything that threatens the dollar is a national-security issue. This threatens the dollar over the long term.”
The digital yuan resides in cyberspace, available on the owner’s mobile phone—or on a card for the less tech-savvy—and spending it doesn’t strictly require an online connection. It appears on a screen with a silhouette of Mao Zedong, looking just like the paper money.
In tests in recent months, more than 100,000 people in China have downloaded a mobile-phone app from the central bank enabling them to spend small government handouts of digital cash with merchants, including Chinese outlets of Starbucks and McDonald’s.
“It’s pretty good,” said Tao Wei, a young woman in Beijing, after spending a test allotment. It took her just an instant to pay for her two-year-old daughter’s birthday portrait by pointing her iPhone toward a scanner. The Chinese Communist Party has also let members settle monthly dues with digital yuan.
China has indicated the digital yuan will circulate alongside bills and coins for some time. Bankers and other analysts say Beijing aims to digitize all of its money eventually. Beijing hasn’t addressed that.
Digitized money looks like a potential macroeconomic dream tool for the issuing government, usable to track people’s spending in real time, speed relief to disaster victims or flag criminal activity. With it, Beijing stands to gain vast new powers to tighten President Xi Jinping’s authoritarian rule.
Elements of this kind of control already exist in China, as digital payments have become the norm. Mr. Mu has said the central bank will limit how it tracks individuals, in what he calls “controllable anonymity.”
The money itself is programmable. Beijing has tested expiration dates to encourage users to spend it quickly, for times when the economy needs a jump start.
It’s also trackable, adding another tool to China’s heavy state surveillance. The government deploys hundreds of millions of facial-recognition cameras to monitor its population, sometimes using them to levy fines for activities such as jaywalking. A digital currency would make it possible to both mete out and collect fines as soon as an infraction was detected.
A burst of cash-accumulation in China last year indicates residents’ concern about the central bank’s eye on every transaction. Song Ke, a finance professor at Renmin University in Beijing, told a recent conference that China’s measure of yuan in circulation, or cash, popped up 10% in 2020.
What about volatility? Cryptocurrencies such as bitcoin are famous for that. But the People’s Bank of China will strictly control the digital yuan to ensure there aren’t valuation differences between it and the paper bills and coins.
That means it won’t make sense for investors and traders to speculate in the digital yuan as some do with cryptocurrencies. Anti-counterfeiting measures will be designed to make it impossible for anyone besides the People’s Bank of China to create new digital yuan.
While China hasn’t published final legislation for the program, the central bank says it may initially impose limits on how much digital yuan individuals can keep on their person, as a way to control how it circulates and provide users a dose of security and privacy.
China’s central bank won’t use the new technology as a way to get more money into circulation, since every yuan issued digitally will essentially cancel one yuan circulating in physical form.
When bitcoin launched in 2009, most nations’ policy makers largely played down its significance. China paid attention.
Always hypervigilant to threats, the leadership feared that a cryptocurrency could undermine government power if people began using it in earnest. Zhou Xiaochuan, China’s top central banker from 2002 to 2018, has said bitcoin both dazzled and frightened him. In 2014, he launched a formal study for a possible Chinese digital currency.
China hardly looked like a currency pioneer. Its strict government control of the yuan, for instance, ran counter to the rip-roaring trade in other major currencies.
At the same time, a financial-technology revolution was under way in China, with the frenetic adoption of the AliPay and WeChat apps making cash mostly unneeded, and turbocharging startup companies with ways to pay on the go.
Then, in mid-2019, Facebook Inc. said it would pursue its own cryptocurrency. The realization this could circulate in a user base far bigger than any national population brought immediate recognition that technology could upend traditional currencies.
While U.S. regulators focused on stopping Facebook, ultimately succeeding, China accelerated its pursuit of a digitized yuan, launching trials in April 2020.
Suddenly, China’s money moves bore watching. Central bankers from the U.S. and other Western economies fret that what Facebook planned with a digital currency could now be done by China, a powerful government.
“There is a sort of Uber fear,” said a senior European central banker who has spoken to Western counterparts, referring to stress on taxi systems when the ride-hailing company arrived in cities around the world. “You don’t want another country’s currency circulating among your citizens,” the banker said.
The U.S., as the issuer of dollars that the world’s more than 21,000 banks need to do business, has long demanded insight into major cross-border currency movements. This gives Washington the ability to freeze individuals and institutions out of the global financial system by barring banks from doing transactions with them, a practice criticized as “dollar weaponization.”
American sanctions on North Korea and Iran for nuclear programs hobble their economies. Swiss banks abandoned their famous secrecy eight years ago to avoid Washington’s wrath in a showdown over taxes. After the February coup in Myanmar, the U.S. used sanctions to block the movement of top military officials’ financial assets through banks. The Treasury’s database of sanctioned individuals and firms—the “Specially Designated Nationals and Blocked Persons List”—touches virtually every nation on earth.
Beijing is especially discomfited by a fast-expanding part of the sanctions register: more than 250 Chinese names, including politicians the U.S. accuses of atrocities against ethnic minorities or of curtailing freedoms in Hong Kong. Sanctions left Carrie Lam, China’s top official in Hong Kong, with a stockpile of cash in her home because banks feared that accepting her business would risk exposing them, too, to an American freeze.
The digital yuan could give those the U.S. seeks to penalize a way to exchange money without U.S. knowledge. Exchanges wouldn’t need to use SWIFT, the messaging network that is used in money transfers between commercial banks and that can be monitored by the U.S. government.
The chance to weaken the power of American sanctions is central to Beijing’s marketing of the digital yuan and to its efforts to internationalize the yuan more generally. Speaking at a forum last month, China’s Mr. Mu, the central bank official, repeatedly said the digital yuan is aimed at protecting China’s “monetary sovereignty,” including by offsetting global use of the dollar.
In a 2019 war game at Harvard University, veteran U.S. policy makers scrambled to craft a response to a nuclear-missile development by North Korea secretly funded with digital yuan. Because of the currency’s power to undercut sanctions, the participants, including several who are now in the Biden administration, deemed it more threatening than the warhead.
Nicholas Burns, a longtime American diplomat and favorite to be ambassador in Beijing, told the group, “The Chinese have created a problem for us by taking away our sanctions leverage.”
As China’s marketing for the digital yuan kicks into high gear, an English-language animation circulated online by state broadcaster CGTN shows a man in an American-flag shirt knocked out by a golden coin depicting digital yuan.
“This is one of the building blocks of China’s move toward world market status and greater involvement in setting the framework of the global economy,” the narrator says.
Initially, the digital yuan won’t change significantly how money circulates through China’s financial system. Under the central bank’s direction, the six biggest commercial banks—all government-owned—will distribute digital yuan to smaller banks and to app providers AliPay and WeChat, which are expected to manage sender-recipient interactions.
Unlike electronic transactions today, the digital yuan is designed to move from A to B instantaneously, at least in theory removing a way banks and financial apps profit off fees and brief built-in delays in such handoffs. The only necessary middleman is the central bank. Mr. Mu has said the digital yuan, because it is state-backed, will reduce risks to the financial system posed by China’s dominant payment platforms that are private companies.
When a global TV audience turns its attention to skaters and bobsledders in Beijing’s Winter Olympics next February, authorities are expected to give visiting athletes digital yuan to spend while they are in the spotlight, an indication of ambitions that stretch beyond China’s shores.
Beijing has joined an initiative to develop protocols for the cross-border use of digital currencies, working with the Bank for International Settlements and the central banks of Hong Kong, Thailand and the United Arab Emirates.
China’s digital strides draw attention to how the U.S. needs to modernize its own financial infrastructure, according to Kevin Warsh, a former Fed governor now at Stanford University’s Hoover Institution. “If we wait 5 or 10 years, we may well end up with some very bad policy choices,” he said.
More than 60 countries are at some stage of studying or developing a digital currency, according to research group CBDC Tracker. Digital currencies hold some of their biggest potential for the 1.7 billion people globally who the World Bank says lack a bank account. The Bahamas has already issued a digital currency to address financially underserved populations. Some central banks say such currencies would come in handy for families of migrant laborers who make tiny fund transfers that are cumbersome and expensive.
The senior European central banker noted that international person-to-person money transfers can take days and worried that speed and efficiency could eventually make the digital yuan a preferred currency for remittances as countries deepen financial ties with China.
China, with a working model, is offering a ready way for managing digital cash. President Xi last year called for China to seize opportunities to set international rules for digital currencies, much as Beijing has sought to influence and dominate an array of advanced-technology standards such as for 5G telecommunications, driverless cars and facial recognition.
Asked during a recent Senate appearance whether the dollar could be digitized to help the U.S. defend its supremacy, the Fed’s Mr. Powell said researching that question is a “very high-priority project.”
“We don’t need to be the first,” he said. “We need to get it right.”
Reprinted by permission of The Wall Street Journal, Copyright 2021 Dow Jones & Company. Inc. All Rights Reserved Worldwide. Original date of publication: April 5, 2021.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
