
China Starts Raising Prices for the World
Chinese manufacturers are increasing prices, adding to inflation fears.

By Stella Yifan Xie
Tue, Mar 30, 2021 1:04pm 4 min
4 min


Chinese manufacturers are increasing prices, adding to inflation fears.
4 min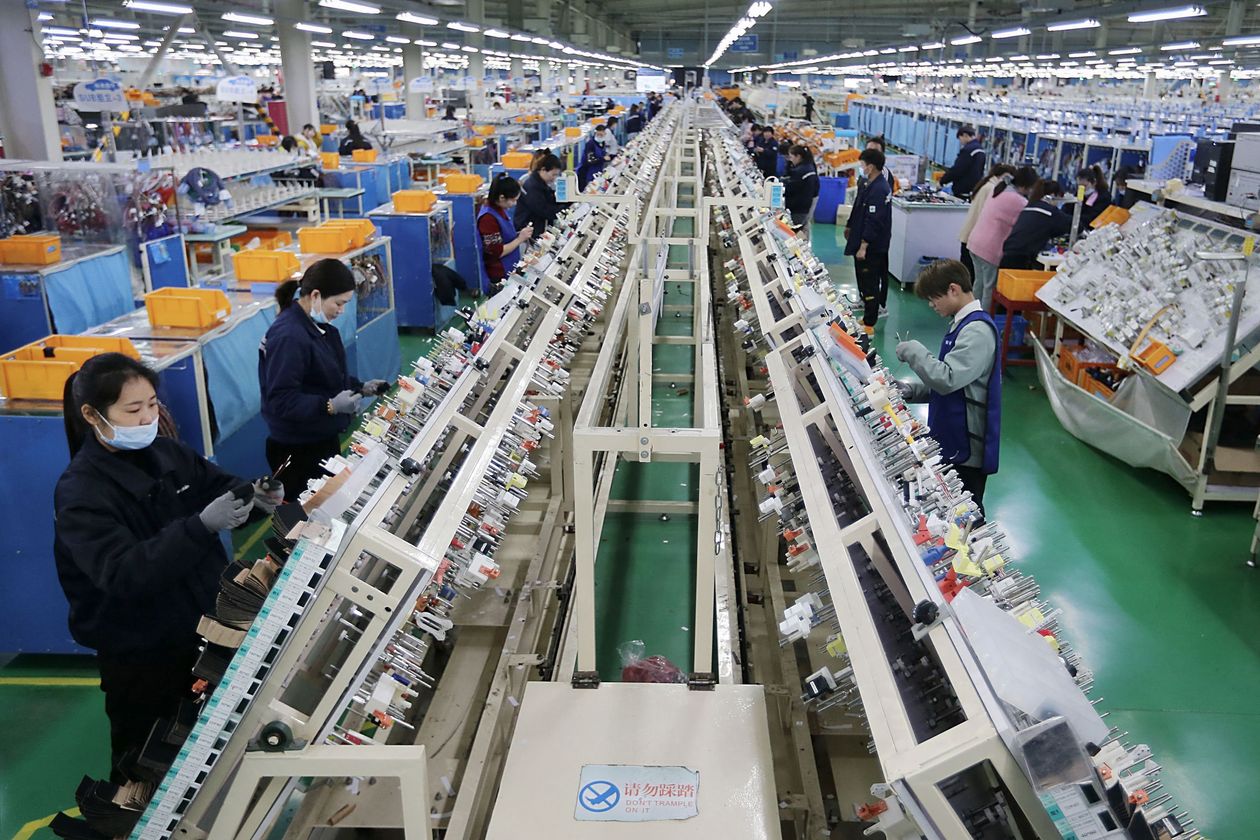
HONG KONG – Rising raw-materials costs and unrelenting supply-chain constraints are prompting many Chinese exporters to increase prices for the goods they sell abroad, raising fears it may add to global inflationary pressures.
The fears have deepened in recent days, after a grounded container ship blocked the Suez Canal, further straining global supply lines stretched by the coronavirus pandemic and stronger-than-expected demand for computer chips and other goods.
Rene de Jong, director of Resysta AV, an outdoor furniture manufacturer based in the southern Chinese city of Foshan, said he plans to raise prices by around 7% on new orders this summer.
That’s largely because prices of chemicals and metals that are used to produce cushions, foams and frames in the company’s factories in China and Indonesia have climbed rapidly in recent months. Shipping freight rates have also climbed roughly 90% since last June, though they are often paid by clients.
“In my nearly 25 years in China, I’ve never seen anything like this. I’ve never seen shipping costs like this before while steel and aluminium prices shot through the roof,” he said, adding that the company’s profit margins are under pressure.
Other Chinese exporters raising prices include apparel businesses and a toy wholesaler who told The Wall Street Journal his company has raised prices for new orders across the board by 10% to 15% since the beginning of March.
Price increases from Chinese factories alone aren’t necessarily enough to push inflation higher in the U.S. and elsewhere. Much of the sting could be absorbed if Western retailers choose to eat the cost increases themselves without passing them on to consumers, though doing so would squeeze retailers’ profit margins.
Also, official inflation calculations in the U.S. encompass far more than just the consumer goods people buy from abroad. Before the pandemic, more than 60% of consumer spending in the U.S. was on services like dining out or travelling, rather than on consumer goods.
Still, price increases by Chinese factories add yet another source of upward pressure on global prices at a time when the cost of everything from lumber to steel and cotton is higher. Some economists and investors worry that the trillions of dollars of stimulus unleashed worldwide will ultimately lead to more inflation than policy makers anticipate, especially if recent bottlenecks in global supply chains persist, though there are fierce debates over how bad the problem could become.
“There’s definitely a risk [that inflation will increase]. It’s not just the position of exporters. It’s everything, from the bottlenecks caused in global shipping to the idea that the stimulus might unleash more demand than supply can keep up with,” said Nick Marro, lead analyst for global trade at the Economist Intelligence Unit. Even so, “it’s somewhat premature to assume that we are going to see runaway inflation at this point.”
What’s clear is that Chinese manufacturers making products for the rest of the world are finding it increasingly hard to hold the line on costs, especially after the pandemic and lockdowns hurt their profits last year. In the past, Chinese factories with cheap labour were often a force for keeping global prices for everything from jeans to sofas lower, but that’s becoming less true as the factories’ own costs climb.
Shipping rates, which soared in recent months amid port bottlenecks and container shortages, are part of the problem. In some cases, clients ask Chinese suppliers to share the burden. In other cases, Chinese factories themselves are having to pay more to ship in imported raw materials, like lumber.
Meanwhile, prices for many commodities have stayed high or kept climbing, and some businesses are choosing to pass those costs on to customers.
Prices for imports from China to the U.S. rose 1.2% over the past year, the fastest increase since 2012, with most of the increase coming in the three months ending in February, according to data from the U.S. Bureau of Labor Statistics.
One positive for American consumers is that the U.S. dollar has remained stronger than many economists expected, which gives its shoppers more buying power when paying for imported goods. Many families accumulated savings during the pandemic, making it easier for them to pay a little more.
Prices are moving higher “primarily on stronger demand,” said Robin Xing, chief China economist at Morgan Stanley. “Manufacturers will find ways to pass on costs in this circumstance. This will not derail the global recovery.”
Some Chinese manufacturers, meanwhile, have said they have been reluctant to increase prices for fear of losing market share, and expect raw materials costs to cool off.
However, there is little sign at the moment that the forces pushing costs higher in China will ease soon.
Ni Fang, manager of Ji’an Huaerxin Shoes Co., a producer of work boots in Jiangxi province that mostly sells to Europe and Southeast Asia, said that after China’s Lunar New Year in February, the company started receiving notices from suppliers of price increases ranging from 10% to 30% for raw materials used in boots and their packaging, including polyurethane, steel and paper.
The factory responded in late February by raising most product prices by around 5%.
“This round of spike in raw materials costs pushed us close to the point where we couldn’t bear it anymore,” said Ms. Ni, adding that the factory still absorbs parts of the cost increase for fear of turning away too many clients.
Other factors may be contributing to higher costs in China. Authorities are trying to limit fossil-fuel consumption to help China achieve its goal of reducing carbon emissions, which may be making it harder for steel and other sectors to increase production. Chinese officials in January reiterated their goal of ensuring that crude steel output will decline year-over-year in 2021, even as steel demand is projected to increase this year as the economy recovers.
Factory owners and economists say they also suspect some buyers are hoarding commodities, adding price pressure.
Chen Yang, a trader at a state-owned textile company in Jiangsu province, said some upstream suppliers began hoarding cotton before the Lunar New Year, telling him they expected the latest $1.9 trillion stimulus bill from the U.S. would buoy commodities prices across the board. Cotton prices jumped to around $2,600 a ton in early March, compared with around $1,990 a ton in mid-February, according to Mr Chen.
As a result, his company had to increase product prices accordingly, since raw materials account for about 70% to 80% of total costs.
“I got calls from clients almost every day asking about the prices, but very few actually placed orders,” he said. “They all want to wait for the prices to cool off. But they’ll have to order sooner or later.”
Reprinted by permission of The Wall Street Journal, Copyright 2021 Dow Jones & Company. Inc. All Rights Reserved Worldwide. Original date of publication: March 29, 2021
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
