Covid-19 Fuelled S&P 500 Selloff Last Year. Here Are Some Lessons Learned.
Share Button

Covid-19 Fuelled S&P 500 Selloff Last Year. Here Are Some Lessons Learned.

Money managers reflect on what the ups and downs of 2020-2021 have taught them.

By Akane Otani
Mon, Mar 8, 2021 1:22amGrey Clock 4 min

A year ago, the longest-ever bull market ended.

The comeback in the stock market since then has been nothing short of astounding.

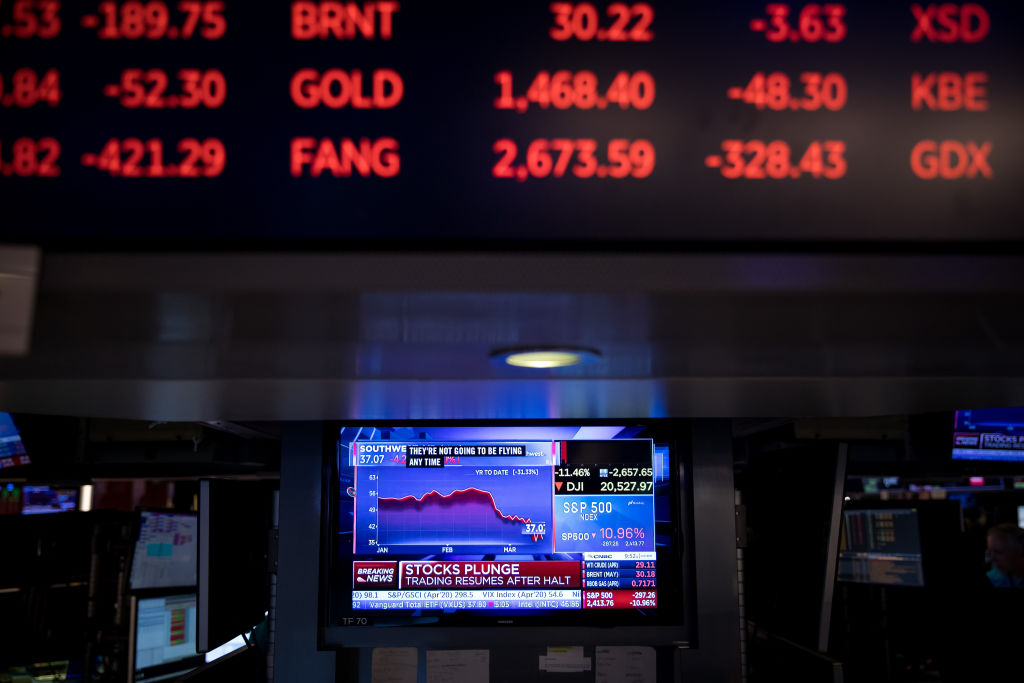
The S&P 500 took just 126 trading days to swing from a record to a bear market and back to a new high—marking the fastest such recovery in history. That was even as market prognosticators warned stocks were due for another bout of selling, based on the growing death toll and unprecedented job losses caused by the coronavirus pandemic.

The U.S. is still in the midst of the same pandemic that led to the spring selloff. And the market’s future remains mired in uncertainty. Just last week, surging bond yields sent many of the most popular technology stocks of the past decade sliding.

The stock market is now barely above the point where it began the year. This coming week, traders say they will be keenly focused on inflation data, which may add to the recent debate over whether inflationary pressures are picking up.

Whatever the data show, many investors say the ups and downs of the past year have reminded them that some investing truths are eternal. Among them:

The markets look way ahead of us

Stocks bottomed out March 23. The next day, a furious rally sent the Dow up more than 11% for its best session since 1933.

The pandemic was far from over. In the same week, politicians and health experts declared New York City the epicentre of the coronavirus pandemic, the U.K. went into lockdown and Japan postponed the Tokyo Olympics.

How was a market rally possible?

Investors like to cite the adage that markets are forward-looking. There is no clearer example of that in recent memory than what happened last year.

Those buying stocks last spring weren’t necessarily doing so out of a belief that the pandemic was close to an end. They were betting on the future turning out to be better. And they were right. Companies are expected to report a 3.9% increase in earnings for the fourth quarter of last year. That is a modest increase, but nevertheless would mark the first quarter of year-over-year growth since the end of 2019, according to FactSet.

An investor waiting for a clear turning point on the pandemic—say, the first vaccine approval—would have missed much of the market’s ride higher.

“It’s hard, it feels counterintuitive for a lot of investors, but if you only focus on buying things that were loved in the past, you’ll always be buying high and selling low,” said Don Calcagni, chief investment officer of Mercer Advisors.

The moment was also fleeting for stay-at-home stocks. Many of them soared in the first half of last year. But as scientists pushed closer to developing safe and effective vaccines, momentum for those trades faded. Domino’s Pizza Inc., Zoom Video Communications Inc. and McCormick & Co. have one thing in common: their shares peaked last fall.

What was bad news for stay-at-home stocks was good news for companies in the travel business, which began rallying in the final months of 2020. While the S&P 500 is essentially flat this year, Norwegian Cruise Line Holdings Ltd., American Airlines Group Ltd. and Delta Air Lines Inc. have notched double-digit increases on a percentage basis.

Cycles move quickly

If last year’s selloff felt like it happened with vicious speed, that is because it did. It took just 16 trading days for the S&P 500 to fall from its Feb. 19 record into a bear market, or a 20% drop from that high. That marked the index’s fastest-ever such descent, according to Dow Jones Market Data.

The comeback that followed was also historically swift. (Though it probably didn’t feel like it for weary traders.)

“You’re really going to either have to play the speed game all the way around, or you gotta grin and bear it, be patient and just hang on and really stick to your buy and hold strategy,” said Richard Grasfeder, senior portfolio manager at Boston Private.

The pace of the action in more speculative corners of the market—think bitcoin, dogecoin or any of the “meme stocks”—has been even wilder.

On Jan. 28, for instance, GameStop Corp. started the trading day at $265, down 24% from the prior afternoon. It swung as high as $483 and as low as $112.25 before ending the day somewhere in between at $193.60.

“The fact that with technology, information moves so fast…I think you can make the case that it has really sped up market cycles,” said Ben Carlson, director of institutional asset management at Ritholtz Wealth Management.

Stock pickers love volatility, but it doesn’t always love them back

The feeling that markets are moving faster than ever should be a boon to active managers. Analysts have long argued that the professionals have the best opportunity to prove themselves when there is plenty of dispersion: meaning the gap between the market’s losers and winners is wide.

But that didn’t pan out in the first half of 2020, a period rife with volatility. Just 37% of U.S. large-cap equity funds managed to beat the S&P 500 over the first six months of last year, according to S&P Dow Jones Indices. (The firm hasn’t yet released its full-year report on active managers.)

Will stock pickers buck the trend in 2021?

So far, they are off to a good start. Bank of America found 70% of U.S. large-cap mutual funds beat their benchmarks in February, the highest share since 2007.

Much of that outperformance appears to have been driven by the fact that technology stocks have underperformed lately. Technology has a big pull on market cap-weighted indexes like the S&P 500, so active managers who haven’t heavily weighted the sector in their own funds have historically struggled to beat the market. This year, it seems a number of fund managers got the timing right. Many are holding on to more shares of companies like banks, utilities and energy producers, which have held up better in the market pullback.

On the other hand, investors who have made a name for themselves betting big on technology have been stung by widening losses. Among the highest-profile casualties of the past few weeks: Cathie Wood’s ARK Investment Management LLC, whose funds have sizable holdings in companies like Tesla Inc., Roku Inc. and Square Inc.

The growth versus value debate has played out countless times over the past decade, with little reward for value investors. But with rising interest rates putting pressure on long-loved corners of the market, money managers like John Allen, chief investment officer of Aspiriant, are feeling hopeful.

“We believe this is going to be a decade where active investing prevails,” Mr Allen said.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026

Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.

By Laura Saunders
Fri, Oct 9, 2026 4 min

Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.

This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.

Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.

Here are three strategies useful for functional families.

Intrafamily loans

It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.

But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.

If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.

To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.

In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.

If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.

Asset gifts

Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.

The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.

Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.

However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.

These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.

But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.

Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.

The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.

Sellner doesn’t worry about his children using the funds for another purpose.

“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.

Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.

Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.

Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”

Disclaimers

A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.

Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.

Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.

Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.