Covid Slashed Consumer Choices. This Is Why They Aren’t Coming Back.
Retailers and suppliers say it didn’t pay to offer products for everyone, and customers didn’t care that much when they stopped
By PAUL BERGER
Tue, Jan 2, 2024 9:32am 4min
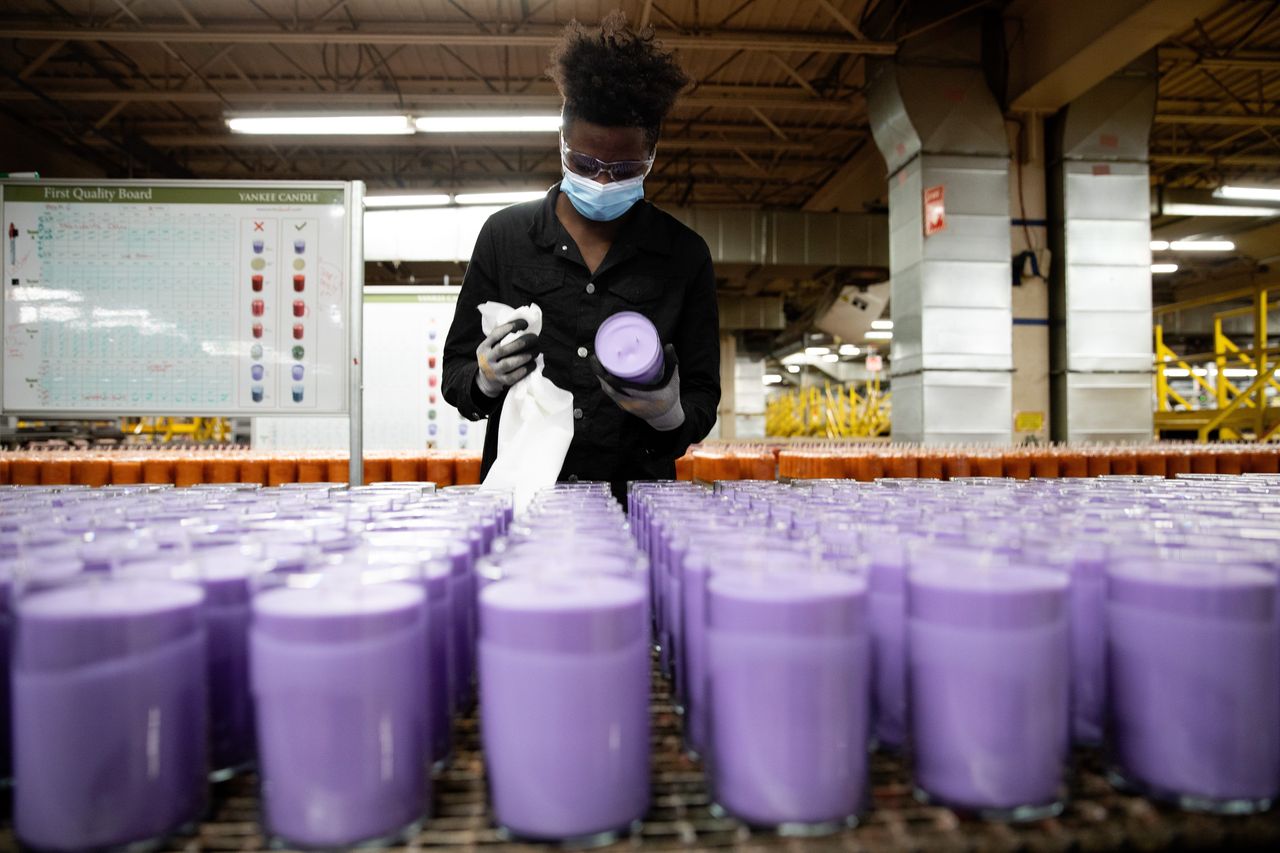
Yankee Candle pared its line of products but still has an extensive selection. KAYANA SZYMCZAK FOR THE WALL STREET JOURNAL
The furniture retailer Malouf sells beds and bedding in a fraction of the colours it did a few years ago. Newell Brands, the Sharpie maker, has retired 50 types of Yankee Candle. Coca-Cola offers half as many drinks.
Covid slashed consumer choices as companies pared their offerings to ease clogs in the supply chain. The logistical mess is behind them. But many of the choices aren’t coming back.
Retailers and suppliers across industries—from groceries to health, beauty and furniture—have said that it didn’t pay to offer products for everyone, and consumers didn’t care that much when they stopped.
“Today, people would rather lose a portion of consumer demand as opposed to spending extra on too much variety,” said Inna Kuznetsova, chief executive officer of ToolsGroup, a supply-chain planning and optimisation company.
Macy’s president and CEO-elect, Tony Spring, told analysts in November that “the customer today does not want an endless aisle.”
New items made up about 2% of products in stores in 2023 across categories such as beauty, footwear and toys, down from 5% of items in 2019, according to the market-research firm Circana. Shelf Engine, a technology company that automates ordering for grocery retailers, said large grocery stores have reduced fresh-food offerings such as fruit, dairy products and deli meats by 15% to 20%.
Large grocers cutting back on choice is a reversal from pre pandemic days, when they believed they had to carry everything to avoid losing customers to the store across the street, said Stefan Kalb, CEO of Shelf Engine.
Kalb said that grocers are now saving money because they have fewer items to manage and that the slimming of product options is reducing food waste.
Executives at consumer-product companies said the thinning of their product lines has been a relief for those struggling to improve profitability in the midst of higher interest rates and rising costs for raw materials and labor. They said many of the reductions have been in lines that consumers wouldn’t notice, such as items in special packaging and assortments for specific big-box retailers. The cutbacks are also to product lines that drown consumers in options.
“I don’t think any consumer would have noticed we went from 200 to 150” types of Yankee Candle, said Chris Peterson, chief executive of Newell Brands.
Some industry specialists said the new focus on bestselling items has reduced innovation and hurt smaller brands that rely on retailers’ desire to carry something for everyone.
“There has definitely been less innovation since the pandemic,” said Seth Goldman, a founder of the organic-beverage maker Honest Tea, which was bought by Coca-Cola in 2011 and discontinued in 2022.
Coca-Cola over the past few years reduced its brands to 200 from 400, cutting slow-growing as well as declining products, including small regional lines such as Northern Neck Ginger Ale and national brands such as its first diet cola, Tab.
“It was pruning the garden to let the better plants grow,” Coca-Cola Chief Executive James Quincey said in 2022.
Goldman said there was still demand for Honest Tea, even if it wasn’t big enough for Coca-Cola. In September 2022, four months after Coca-Cola’s announcement, he launched Just Ice Tea, a drink that he said is similar to Honest Tea and that is expected to have sales in 2023 of more than $16 million.
Companies began winnowing product lines in the years leading up to the pandemic as a corrective to previous decades when consumer choice ballooned. That was partly because of the internet, where online retailers weren’t constrained by the space limitations of physical stores, giving rise to the term “endless aisle.”
The cuts were turbocharged in 2020 and 2021, when product shortages and a surge in consumer spending led companies to give priority to the most in-demand items. They focused on products that ran fastest on production lines and, because of social distancing in factories, could be made with automated machinery.
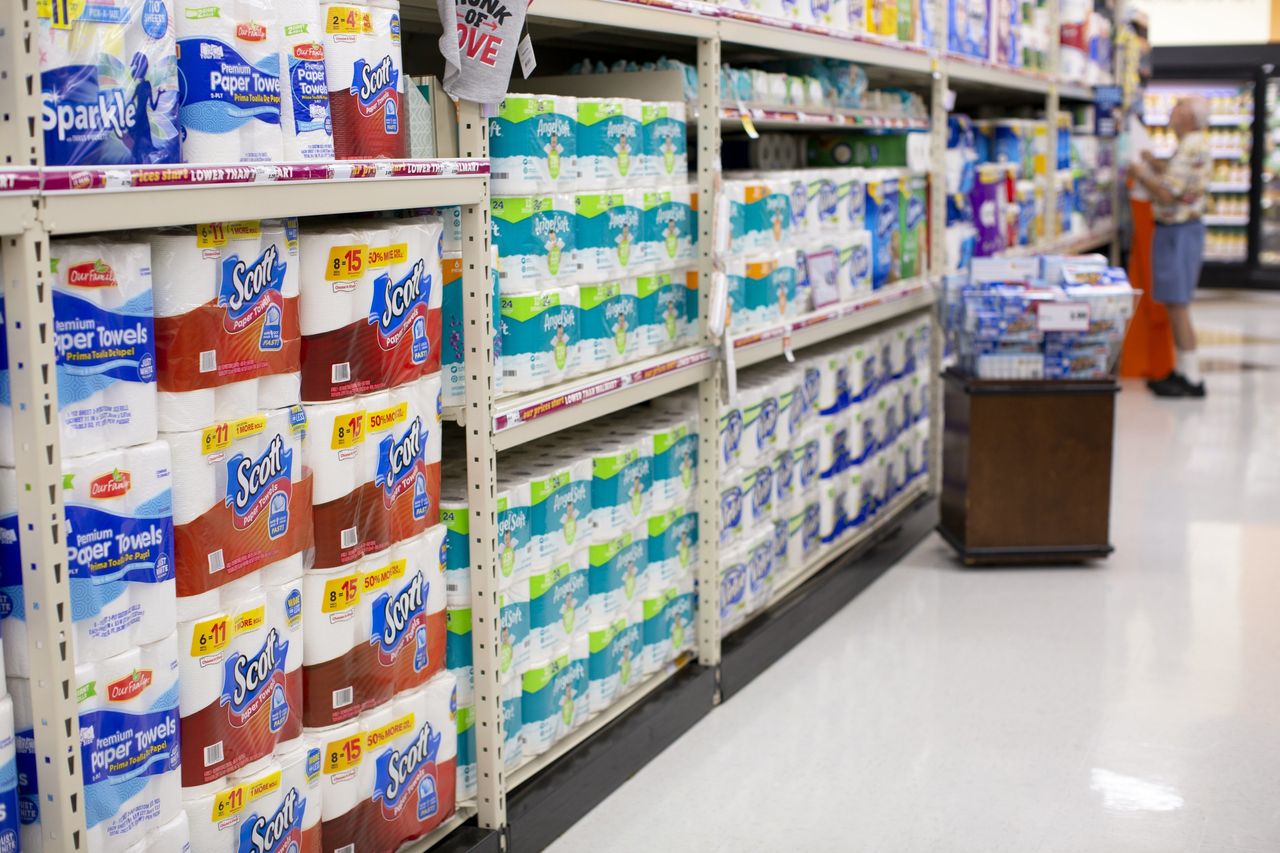
Kimberly-Clark cut more than 70% of its toilet paper and facial-tissue products over a single weekend in 2020 as it rushed to satisfy a fourfold increase in demand, said Tamera Fenske, the company’s chief supply chain officer.
Fenske said the company jettisoned slow-selling items as well as many of the special counts and custom sizes it made for individual retailers. Fenske said that, as pandemic restrictions eased, Kimberly-Clark was able to be more thoughtful about the items it brought back. She said the company carries about 30% fewer product lines in North America than it had at the start of 2020.
PVH, which owns Tommy Hilfiger and Calvin Klein, embarked in 2020 on a plan to cut more than a fifth of its offerings to focus on what it calls “hero” products—those that make up an essential part of someone’s wardrobe.
Kimberly-Clark, maker of Scott paper towels, has brought back some, but not all, of the products it stopped offering during the pandemic. PHOTO: KRISTEN NORMAN FOR THE WALL STREET JOURNAL
Some companies said the culling of less-popular products opened up space for new lines.
Georgia-Pacific stopped selling 164-sheet rolls of Quilted Northern toilet paper because its larger rolls were better for consumers who valued longer-lasting rolls, said Kim Burns, senior vice president of supply chain for Georgia-Pacific’s consumer products group. Burns said the company has subsequently invested more time and money in new product lines, such as toilet paper with a scented tube that acts as a bathroom air freshener.
For other companies, the supply-chain shock provided a real-life experiment in how trimming product lines could improve productivity without hurting customer satisfaction. “It was quite shocking as we parsed it out to see we were using a lot of our buying power to really not get much of a return on investment,” said Nick Jensen, vice president of product at Malouf.
The Logan, Utah-based furniture company has reduced its lines to about 3,500 product choices, down from almost 11,000 items before the pandemic. Jensen said the company is adding new items more carefully these days.
“If we have 15 different colours and three shades of grey, it’s a paralysing choice,” Jensen said. “It’s kind of forced us to be much more intentional versus throwing a lot of things at the wall and hoping that they stick.”
—Suzanne Kapner contributed to this article.
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
By Laura Saunders
Fri, Oct 9, 2026 4min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.


 4 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



