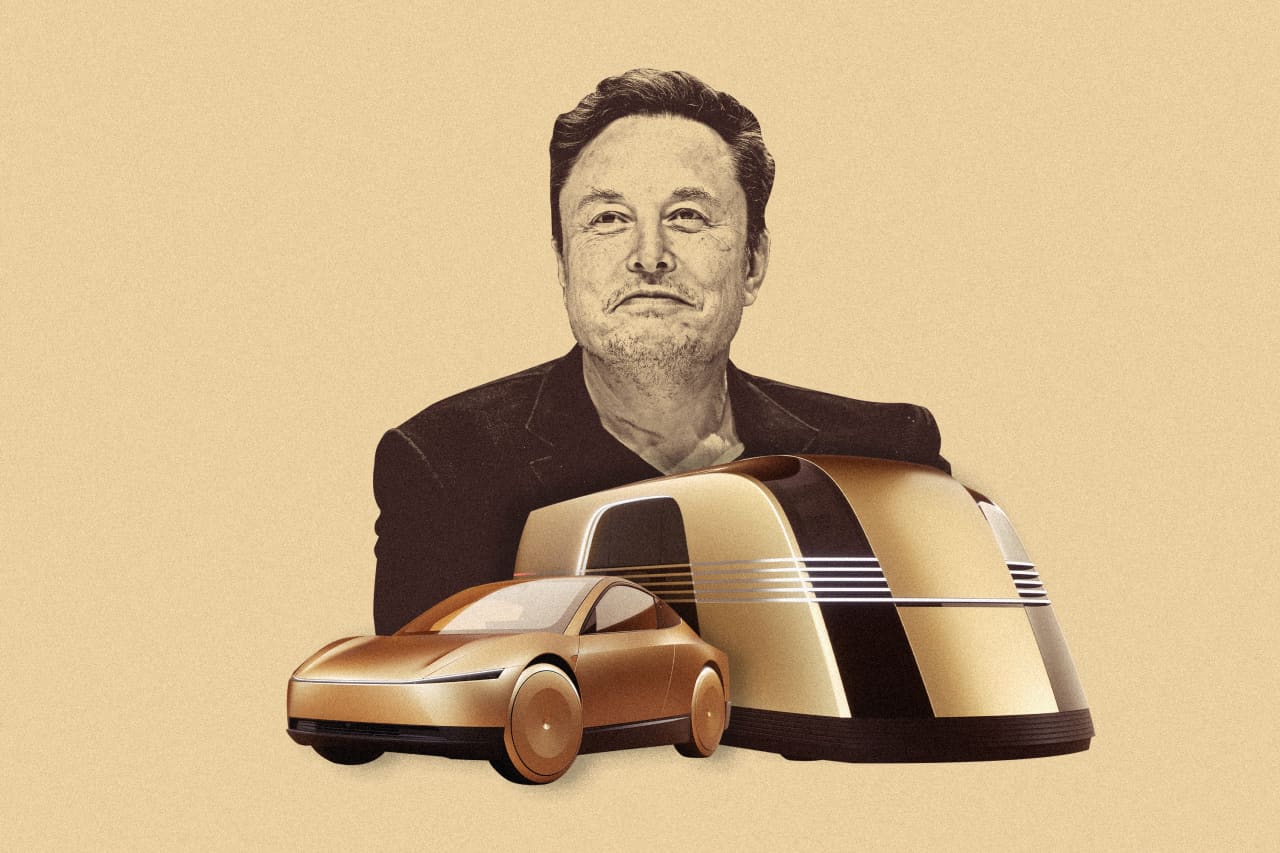
Elon Musk Plays a Familiar Song: Robot Cars Are Coming
Tesla’s Robotaxi event excites faithful betting on the company’s future in robotics, while underwhelming those watching from afar
Elon Musk , dressed in a leather jacket in front of adoring fans, looked like an ageing rock star on stage playing one of his greatest hits.
Robot cars are coming.
Those fans at Thursday’s event swooned as they always have as he pushed out timelines for delivering robot cars and showed what those vehicles could look like. But outside the Hollywood-area venue, it wasn’t exactly clear that everyone believed his vision for the future is as near as he says.
Tesla stock fell almost 9% Friday amid investors frustrated with the continued lack of details for how the company is going to make the very complicated transition from maker of cars to maker of robots.
In essence, Thursday night’s much-hyped product reveal became something of a Rorschach test: Supporters, who point to everything Musk has accomplished with electric cars and other industries, heard a glorious future with driverless cars and humanoid robots. Critics—mindful of previous missed goals and maybe peeved by his contentious politics —saw more smoke and mirrors.
“Let’s not get nuanced here,” the chief executive told the crowd as they peppered Musk with questions, a reminder that even among the faithful, time is ticking for him to play some new notes. And to deliver a big hit.
What he did show was cool. A two-seat car with doors that swung upward to open, inspired, in part, by the sci-fi movie “Demolition Man.”
Though as Musk talked about the vehicle, it wasn’t clear he had settled on a formal name. On stage, he called it the “Cybercab,” while the company released details on its website calling it the “Robotaxi.”
Whatever the name, the straight lines of the small car resembled what might be the offspring of the Cybertruck , the pickup the company brought out last year after some delays, and the new Roadster that was first revealed in 2017 and has yet to come to market. Those delays are examples of “ Elon Standard Time ,” or his practice of setting a target only to miss it.
Robot cars are coming.
The Cybercab/Robotaxi reveal also included what Musk says will be Tesla’s autonomous van, an art deco-inspired vehicle that resembled a giant toaster with an interior meant to feel like a spaceship and enough room for 20 passengers.
Like the small car, the van lacked a steering wheel—the sort of doodads currently required under regulations, though exceptions can be granted. The car could begin production “probably” in 2026, Musk said. He didn’t even suggest when the van might come.
The nearest timeline was deploying fully self-driving cars, through the company’s current offerings, next year in Texas and California.
Musk has been predicting driverless cars being just around the corner for several years, including in 2016 when he said Tesla would demonstrate a car driving itself from Los Angeles to New York City in 2017. That didn’t happen.
In 2019, he said he expected his robot taxis would arrive in 2020 . That didn’t happen.
But Tesla has pushed the envelope with its driver-assist system that is essentially a glorified cruise control—adjusting speed, keeping within a lane and other manoeuvres—but can’t technically drive the car itself. Tesla says the person behind the wheel is responsible for everything, though some drivers grow overconfident in its true abilities and act like the car is autonomous.
Musk likes to talk about how Tesla vehicles are collecting valuable real-world data that is used to train its AI systems.
After building Tesla into the world’s leading electric-car company, Musk in recent years has tried to position its future on robotics, saying it is focused on solving self-driving technology. “That’s really the difference between Tesla being worth a lot of money and being worth basically zero,” Musk said in 2022.
Despite that rhetoric, Tesla is behind in deploying cars on roadways without drivers. Alphabet ’s Waymo has deployed fully autonomous vehicles in places such as San Francisco, where paying customers can take its vehicles around the city without anyone sitting behind the wheel.
On Thursday night, Tesla demonstrated 50 vehicles, including the new two-seater, driving autonomously on private property of the Warner Bros. studios where Musk held his party for investors and supporters.
Detractors were quick to pounce.
“After over 10 years of Full Self-Driving development, Tesla is limited to a 20-30 acre geofenced 5mph 1950s Disneyland ride on a preprogrammed, premapped and heavily rehearsed route with no traffic and no pedestrians,” Dan O’Dowd , a critic of Tesla and founder of a rival software company, said in a statement. “Tesla robotaxi is nothing more than the latest work of fiction to come out of the Warner Bros. Studio.”
But Thursday night wasn’t about impressing the O’Dowds of the world. And maybe not even those watching on the livestreams through Musk’s social-media platform X—which counted more than 9 million views by Friday evening.
The real target were the hundreds of attendees at the event who spent the evening riding around in the cars and posting fawning videos of their experiences on social media, in turn, helping the event go even more viral and generating even more attention for the idea that Tesla is paving the way for a robot future.
Robot cars are coming.
Not only did party attendees enjoy rides, but they were entertained by the latest versions of Tesla’s humanoid robots Optimus, which Musk has said could one day add $25 trillion to the company’s market value.
Former Tesla board member Steve Jurvetson posted a video of himself playing rock, paper, scissors with one of the robots. “Optimus just beat me in rock paper scissors!” he tweeted .
Others shared videos of robots pouring drinks and dancing.
“The markets won’t get what happened last night at @tesla ,” Robert Scoble, a blogger and former Microsoft tech evangelist, posted on X. “I couldn’t be more impressed. @elonmusk laid out a bunch for next decade. I have been to a lot of product launches and never have been to one like this.”
Some even compared the evening to when the late Steve Jobs unveiled Apple ’s first iPhone, marking the beginning of a new technology era. It was an idea that Musk was quick to endorse.
“Yes, this marks a fork in the road,” he tweeted afterward.
Robot cars are coming.
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.