European Central Bank Raises Key Interest Rate to Record High - Kanebridge News
Share Button

European Central Bank Raises Key Interest Rate to Record High

Central bank signals this might be enough to combat inflation, but doesn’t rule out further increases

By TOM FAIRLESS
Fri, Sep 15, 2023 8:28amGrey Clock 4 min

FRANKFURT—The European Central Bank raised interest rates by a quarter percentage point to a record high but signalled that eurozone borrowing costs may have peaked, sending the euro tumbling.

In a split decision, ECB officials raised the bank’s deposit rate to 4%, the 10th increase in a row and a vertiginous rise from below zero last year.

At a news conference, ECB President Christine Lagarde signalled that Thursday’s rate increase might be the last, although she didn’t rule out further hikes if economic data disappoint.

ECB officials judge that rates “have reached levels that, maintained for a sufficiently long duration, will make a substantial contribution” to reducing inflation to their 2% target, Lagarde said, repeating language used in the bank’s policy statement.

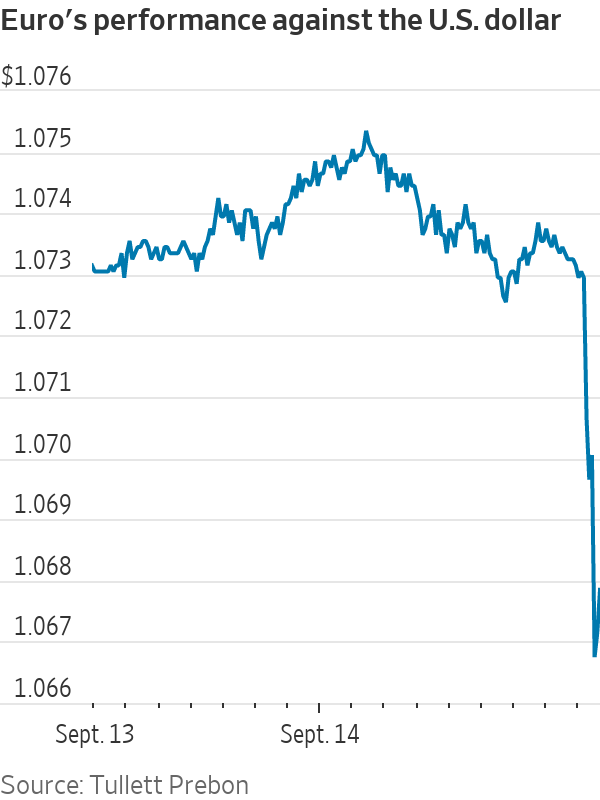
The comment prompted investors to downgrade their expectations for future ECB rates, sending the euro down by almost a cent against the dollar to below $1.07, its lowest level since March. Bond yields slid, with yields on the benchmark 10-year government bonds of Germany, France and Italy down between 0.05 and 0.10 percentage point. European stocks rallied, with the benchmark Stoxx Europe 600 index rising more than 1%.

The eurozone still has lower interest rates than the U.S., as well as higher inflation and a struggling economy that contrasts with relatively healthy economic growth in the U.S.—all factors that are weighing on the euro.

“In all likelihood the ECB is done,” said Frederik Ducrozet, head of macroeconomic research at Pictet Wealth Management in Geneva.
Major central banks including the Federal Reserve are signalling a possible halt to a historic series of interest-rate increases over the past 18 months aimed at tackling a surge in inflation unseen since the 1970s.

Ending rate increases would favour borrowers amid uncertainty in the global economy, declining international trade and faltering industrial output. However, signalling a peak in interest rates now risks letting excessive inflation on both sides of the Atlantic become entrenched. Some central banks, including those of Australia and Canada, signalled a pause in recent months, only to start raising rates again.

Recent market movements suggest investors are now betting that rates will peak and even start falling as early as next spring as inflation and economic growth both come down.

They expect the ECB to hold interest rates at about 4% through next summer before starting to cut them, according to data from Refinitiv. They think the Fed will hold rates steady in a range between 5.25% and 5.5% at its meeting next week, and to start cutting rates early next year. The Bank of England is expected to increase interest rates at least once more this year before cutting them later next year.

Investors had been unusually divided before Thursday’s decision over whether the ECB would pause already or unveil one last rate increase. That disagreement reflects uncertainty over how much a slowdown in eurozone growth, together with the ECB’s past rate increases, will cool the region’s inflation rate, which stood at 5.3% in August, unchanged from a month earlier.

Lagarde said some of the central bank’s governors would have preferred to hold rates steady at this month’s meeting. However, a “solid majority” of them agreed on the decision to take rates higher, she said.

New economic forecasts published by the ECB Thursday suggested that eurozone growth will slow significantly more than previously expected this year and next, while inflation will remain markedly above the ECB’s target of 2% through next year. The bank raised its forecast for inflation next year from 3% to 3.2%, mainly to reflect “a higher path for energy prices.”

Asked about the prospect of rate cuts, Lagarde replied that “is not even a word we have pronounced.”

“The longer they can keep interest rates at elevated levels, the more insurance they buy against a downturn down the road,” said Robert Dishner, a senior portfolio manager at Neuberger Berman. “If they end up cutting too soon, they risk reigniting inflation.”

Central banks in Europe face a particularly daunting challenge because while recent interest rate rises have weighed heavily on lending and probably lowered economic growth, they have yet to show a marked effect on underlying inflation. This contrasts with the U.S., where the Fed has taken interest rates higher than the ECB and underlying inflation has fallen significantly while the nation’s growth remains robust. Underlying inflation in August was 5.3% in the eurozone and 4.3% in the U.S.

Recent data and business surveys signal a darkening economic outlook for Europe amid weak growth in China and a decline in global manufacturing. The eurozone economy has largely stagnated since late last year, and industrial production declined in July, dragged down by weakness in Germany, the region’s largest economy.

Lagarde warned that Europe is currently going through a phase of very sluggish growth and suggested that the ECB’s rate hikes are filtering through to the economy. “We are beginning to see weakness in the volume of hires particularly in the services sector that is related to manufacturing,” she said.

Meanwhile, a recent increase in oil prices is pushing inflation in the wrong direction. The euro has slumped against the dollar in recent weeks, to around $1.07 from $1.12 in July, as the eurozone’s economic prospects have soured. That increases the cost of imported goods, making the ECB’s job harder.

Matthew Ryan, head of market strategy at financial-services firm Ebury, said the ECB would likely start cutting rates later, and possibly at a more gradual pace, than the Fed, which should support the euro.

Some of the economic weakening is as intended. The ECB expects its rate increases to slow the region’s economy by weighing on asset prices and demand for loans. However, it isn’t clear if inflation is starting to fall because of the ECB’s actions or because of other factors, such as the fact natural-gas prices are dramatically lower compared with last year, when Russia throttled Europe’s gas supplies. This makes it hard to predict if the region’s economic slowdown will push inflation all the way down to 2%.

Market confidence in the ECB’s ability to achieve its objectives is gradually eroding, with the closely watched five-year, five-year inflation swap—a gauge of expected inflation over a 10-year horizon—standing at 2.6%, according to Franck Dixmier, global chief investment officer for fixed income at Allianz Global Investors.

High current and expected future inflation could mean that investors are underestimating the potential for further ECB rate increases, Dixmier said.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026

Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.

By Laura Saunders
Fri, Oct 9, 2026 4 min

Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.

This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.

Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.

Here are three strategies useful for functional families.

Intrafamily loans

It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.

But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.

If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.

To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.

In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.

If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.

Asset gifts

Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.

The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.

Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.

However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.

These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.

But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.

Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.

The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.

Sellner doesn’t worry about his children using the funds for another purpose.

“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.

Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.

Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.

Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”

Disclaimers

A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.

Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.

Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.

Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.