Everyone’s Over ‘Quiet Luxury.’ Here’s What’s Next - Kanebridge News
Share Button

Everyone’s Over ‘Quiet Luxury.’ Here’s What’s Next

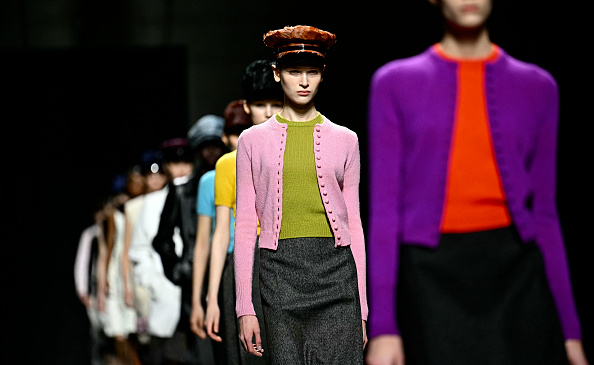
Cosy silhouettes and sumptuous fabrics were throughlines of the fashion collections shown last week in Milan

By RORY SATRAN
Tue, Feb 27, 2024 8:47amGrey Clock 3 min

“Quiet luxury” has become a bit of a dirty phrase in Milan. To some at the Italian brands that embody the term , it’s reductive—an overly TikTok-ified way of describing classic, refined clothing. Many fashion industry people roll their eyes when it comes up.

Brunello Cucinelli , one of the kings of natural textiles, prefers the term “gentle luxury.” At his fall presentation in Milan this past week, the (extremely expensive) clothing at which he excels looked especially touchable. Cashmere sweatsuits were layered with blanket-like scarves and silky suiting hung in loose pleats. Even an evening look, composed of a black sweater tucked into a feathered skirt, appeared comfy. Holding a pillowy bag, one Brunello disciple called it “accogliente”—Italian for “cozy.”

One step beyond coziness is protection, and there was plenty of that in Milan, too. Chalk it up to an uncertain luxury market , the roiling geopolitical climate or global warming, but using clothing as a sanctuary seemed to be on many designers’ minds. For some, like the excellent Brioni La Donna and Loro Piana collections, that means impeccable tailoring and forever-worthy double-breasted coats. Others, like Luke and Lucie Meier at Jil Sander, took the cocooning more literally, making succulent, quilted floor-length capes.

Not everyone is swaddling themselves in shearling. Architect Bianca Censori, who joined her companion, the rapper Ye, at the Marni show, wore a mere scrap of leather that failed to cover her buttocks among other body parts. No protection needed—except her bodyguard.

The Look of Love at Prada

Miuccia Prada and Raf Simons, the co-creative directors of Prada, are on quite a roll. If you were feeling hyperbolic, you might even say that they’re making fashion history. The duo’s fall collection started with thinking about love, explained Simons backstage, but “all the elements of love,” including loving your home, or even loving your sheets. There’s that theme of comfort again.

That manifested in a romance for different eras of fashion, remixed: A Jackie O. linen shift dress shot through with a streak of shearling. A leather bomber jacket embellished with “1913,” the year Prada was founded. A twin set in shocking red and ultraviolet. High-tech nylon jackets in midcentury couture shapes.

“There is no way to think about the future unless you have a good understanding of the past,” said Simons.

Everyday Allure at Bottega Veneta

In less than four years, Matthieu Blazy has completely renewed Bottega Veneta, making it a cult spot for creative types that want unique clothing and accessories with plenty of craftsmanship. Without succumbing to naked dresses and other revealing gimmicks, the brand appeals to a broad demographic, as shown by front-row neighbours Julianne Moore, 63, and A$AP Rocky, 35.

The fall collection, Blazy said backstage, was a “celebration of the everyday.” He found himself thinking about the allure of everyday clothing on his nightly dog walks. This meant recognizable pieces like peacoats, skirts and sweaters, reduced to their essential essence but rendered fabulous through textile innovation and fabrication. A simple yellow evening dress had a shirred-fabric fraying (not unlike recent work by Phoebe Philo ) and a long column skirt boasted leather plumes.

Blazy wanted to express resilience, he said, like flowers blooming in the desert. Fittingly, he designed giant Murano glass cactus flowers to decorate the show space.

Womblike Sumptuousness at Jil Sander

Real life crept into the fashion bubble on the day of Jil Sander’s show, when guests were confronted with a triple-whammy of rain, traffic and multiple public protests that closed the streets. Supermodel Mariacarla Boscono, like several models and editors, had a harrowing trip from Dolce & Gabbana to Jil Sander, and was swept right into hair and makeup and then onto the runway. Wearing the first look, a cocoon-like rounded red suit, Boscono was worth the wait.

Jil Sander put forward an extensive 68-look collection chock-full of satisfyingly sumptuous pieces. Chunky knitwear was sheathed in fine netting, tailored pieces were lined in silky quilting. Coats in deer leather and Himalayan goat fur looked like outerwear for an Icelandic wedding.

Androgynous Realism at Tod’s 

At conservative Italian stalwart Tod’s, Matteo Tamburini executed an impressive debut. Upon arriving from Bottega Veneta in December, the first thing Tamburini discussed with Tod’s group boss Diego Della Valle was the need to create “desirable objects.” “You don’t want to have a big fashion show and then find nothing in the store,” said Tamburini after the show.

So in just a few short months, Tamburini was able to create a tightly edited women’s collection full of androgynous separates and light, appealing accessories. Stylist Brian Molloy, who’s also worked with The Row and Hermès , worked magic with restraint. One supersoft foldable tote big enough for a laptop had a slit at the top so it could fit under your shoulder—easy stuff that merits a high price tag.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Lifestyle
AI Agents Are a Threat to Travel Businesses. Airbnb Could Still Be a Winner.
By David Wainer 13/10/2026
Lifestyle
Amazon in Talks to Buy AI Startup Decart for Around $7 Billion
By Kate Clark and Lauren Thomas 12/10/2026
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026

Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.

By Laura Saunders
Fri, Oct 9, 2026 4 min

Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.

This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.

Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.

Here are three strategies useful for functional families.

Intrafamily loans

It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.

But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.

If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.

To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.

In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.

If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.

Asset gifts

Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.

The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.

Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.

However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.

These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.

But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.

Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.

The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.

Sellner doesn’t worry about his children using the funds for another purpose.

“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.

Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.

Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.

Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”

Disclaimers

A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.

Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.

Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.

Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.