Keep the Ambition, Lower Your Ego. How to Thrive as a No. 2 Like Charlie Munger. - Kanebridge News
Share Button

Keep the Ambition, Lower Your Ego. How to Thrive as a No. 2 Like Charlie Munger.

Warren Buffett’s longtime deputy showed that rising to the top isn’t everything

By CALLUM BORCHERS
Fri, Dec 1, 2023 9:00amGrey Clock 3 min

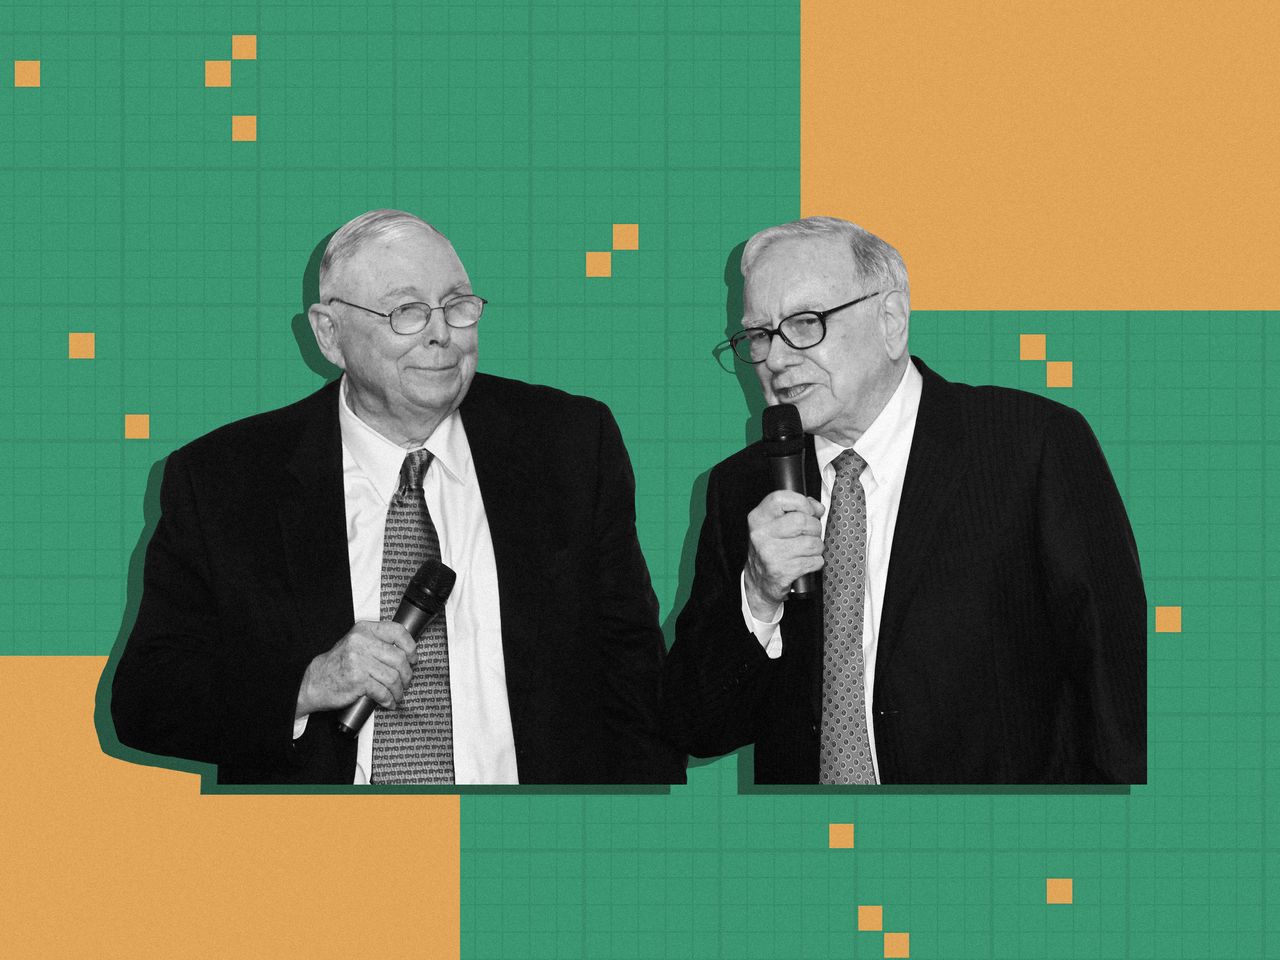
Charlie Munger was Robin to Warren Buffett’s Batman, a business equivalent of the Edge rocking with the Bono of investing.

Munger, who died Tuesday at age 99, played one of the toughest roles in the corporate (or any) world: No. 2.

Succeeding as second in command takes a rare blend of confidence and humility, say people who’ve done it. The consummate right-hand person must be devoted to organisational success while accepting that someone else’s star will always shine brighter.

At a time when many American workers are reconsidering whether the race to the top is worth running at all, Munger’s apparent satisfaction with being the ultimate sidekick could be a model.

It helped that Warren and Charlie, as the duo was known, shared a personal friendship. And being a wingman is presumably more fun when you’re a billionaire, as Munger was. Most important, say those who knew him: Munger knew he was respected and appreciated.

Buffett made sure of it.

Harry Kraemer, former chief executive of the healthcare company Baxter International, recalls a conversation with Buffett at a CEO gathering around the year 2000: “I said, ‘Boy, you’ve got an amazing track record.’ And he goes, ‘It isn’t just me. Never mention my name without Charlie’s.’”

In a recent annual letter, Buffett wrote: “I never have a phone call with Charlie without learning something.”

There aren’t many pairs like Buffett and Munger. An analog might be the late Canadian telecom mogul Ted Rogers and his longtime lieutenant, Phil Lind, who died in August at age 80. Robert Brehl, who co-wrote Lind’s 2018 memoir, “Right Hand Man,” says loyalty is essential to a relationship like Rogers-Lind or Buffett-Munger.

Having complementary strengths and interests helps ward off resentment, Brehl adds.

“You have to have the yin and yang,” he says. “Ted wouldn’t have been as effective without Phil, and the same thing with Warren and Charlie.”

Before meeting Buffett, Munger was already a professional success. He served in World War II, went to Harvard Law School and co-founded a law firm, Munger, Tolles & Olson, where his name was first on the door.

Even though his results as an investor were strong, over time, he realised he could be more successful—and happier—in a partnership. Understanding his own shortcomings contributed to his willingness to become Buffett’s running mate, he has said. He rejected Buffett’s initial overtures before agreeing to come aboard.

“It took me a long time to wise up that [Buffett] had a better way of making a living than I did,” Munger told CNBC in 2021. “But he finally convinced me that I was wasting my time.”

Not that it was easy to set aside his ego to take the No. 2 role and play to what his No. 1 needed. Buffett was Berkshire Hathaway’s public face and larger-than-life persona. Munger seemed to relish his freedom from talking to reporters and investors. In the background, he could be sharper, more direct and funnier.

The durability of the Buffett-and-Munger duo act stemmed, in part, from a shared intellectual curiosity, a measure of humility—for billionaires, anyway—and willingness to learn from their mistakes.

“I constantly see people rise in life who are not the smartest, sometimes not even the most diligent, but they are learning machines,” Munger said in his commencement address to the University of Southern California’s law school in 2007. “They go to bed every night a little wiser than they were when they got up and, boy, does that help, particularly when you have a long run ahead of you.”

Savvy runners also know it can be best to let someone else take the lead to break the wind. A certain type of person prefers to run second, says social psychologist Tessa West, who is studying people she calls “runners up” for a forthcoming book.

“Once you get to a certain level of power, you realize that that top position doesn’t necessarily come with more influence—it just comes with more publicity and a lot more reputational risk,” she says. “The way I see it, Munger got to have his cake and eat it too. He had status without all the headaches.”

He also had a life outside of Berkshire and Buffett. One of Munger’s pet projects was a quest to design the perfect college dormitory.

He’ll be remembered as the consummate consigliere, but that wasn’t his whole identity.

—Geoffrey Rogow contributed to this article.


MOST POPULAR

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.

Related Stories
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Money
Wall Street Is Counting on Nvidia to Keep the AI Party Going
By David Uberti and Krystal Hur 24/08/2026
Money
China Is Opening the First Regular Cargo Route Through the Arctic
By 18/08/2026

Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.

By Gregory Zuckerman and Gunjan Banerji
Mon, Aug 31, 2026 3 min

Wall Street’s hottest trade has gone ice cold.

For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron TechnologyNvidiaAdvanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.

The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.

Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.

“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.

Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.

Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.

Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.

“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.

Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.

“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”

Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.

Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”

The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.

The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.

These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.

Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.

The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.

Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.

Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.

And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.

“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”