Metals Markets Steel For Price Rises As Australia Pushes To Save Cultural Sites
Share Button

Metals Markets Steel For Price Rises As Australia Pushes To Save Cultural Sites

Delays to mining projects in Western Australia could push commodity prices higher and exacerbate shortages.

By RHIANNON HOYLE
Wed, Dec 16, 2020 3:42amGrey Clock 3 min

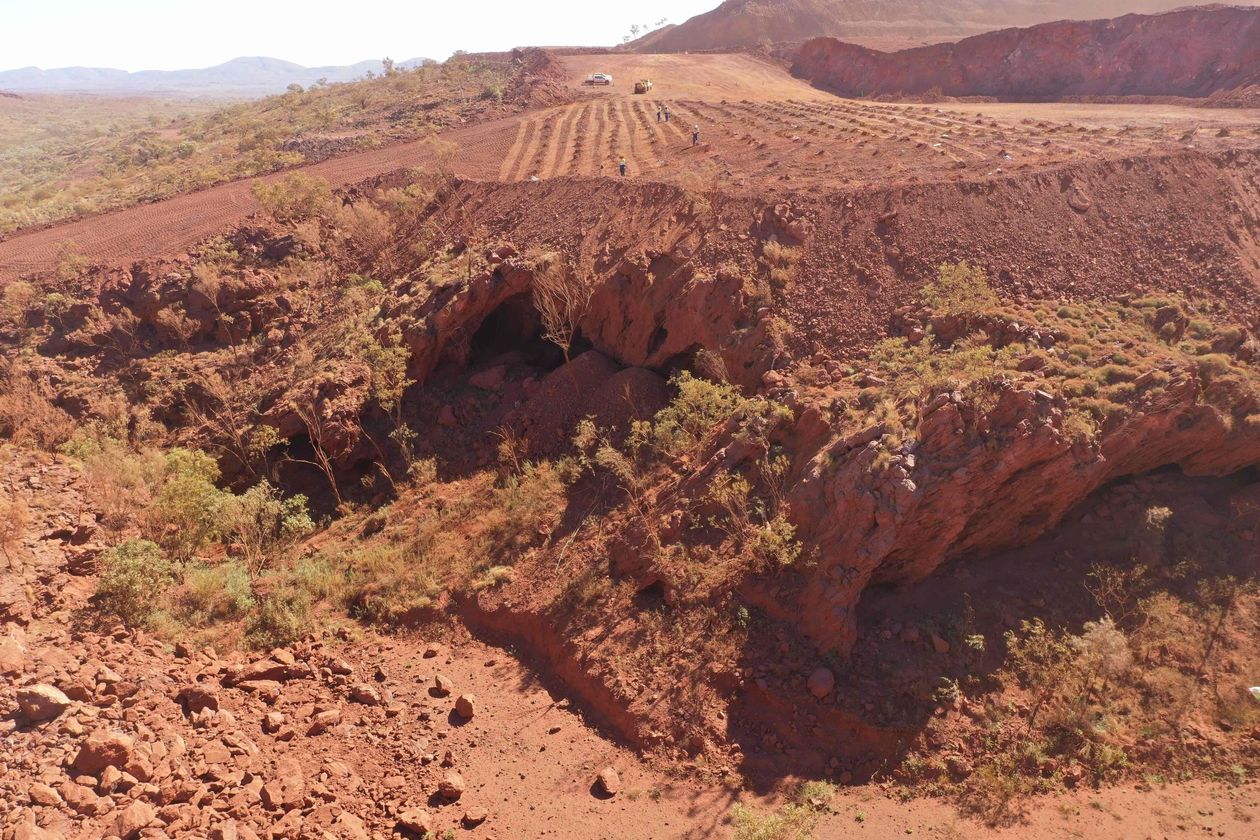
SYDNEY—Rio Tinto PLC’s destruction of two ancient caves in Australia to expand an iron-ore mine could have ramifications for global commodity markets if local lawmakers intensify scrutiny of mining activities that threaten heritage sites.

Among the most controversial recommendations made by a federal-government inquiry into the destruction of the rock shelters at Juukan Gorge in Western Australia in May is a moratorium on expansions of existing mines or new pits that encroach on sites of cultural or historical significance. Even if lawmakers opt for a less hard-line approach, experts warn of potential delays to production and higher costs that could affect supply of key raw materials such as iron ore, used to make steel.

None of the recommendations handed down by the inquiry in its interim report on Wednesday are binding, but miners risk inflaming tensions with some investors who feel the industry needs to show greater sensitivity to environmental and cultural issues if they don’t accept them. They also face sensitive negotiations with indigenous groups that are the traditional owners of the land.

Metals prices have been rallying as China’s economy bounces back strongly and other major markets recover from the coronavirus crisis. Copper prices have risen to their highest level in almost eight years. Iron ore is one of the best-performing assets this year, fetching $150.75 a metric ton on Wednesday, its highest price since early 2013.

China’s unexpectedly strong appetite for these commodities has raised concerns over whether there’s enough supply, with many analysts predicting market deficits for iron ore and copper through at least the middle of next year.

Delays to mining projects in Western Australia, where companies dig up metals including copper and gold, could push commodity prices higher and exacerbate shortages already worsened by pandemic-driven disruptions to operations elsewhere. Iron ore is considered to be most at risk because Australia accounts for more than half of the world’s trade in the commodity by sea.

“This could be a watershed moment for the Western Australia mining industry and could impact Western Australia iron-ore production, and possibly other commodities, in 2021 and beyond,” Goldman Sachs said.

Already there are tensions between miners and some investors following the report into the loss of the Juukan caves, which contained a trove of artifacts that indicated they had been occupied by humans more than 46,000 years ago.

Fortescue Metals Ltd., the world’s fourth-largest iron-ore exporter by volume, rejected the idea of a voluntary moratorium on new heritage consents. “We do not believe that this is either a feasible or practical solution,” Elizabeth Gaines, Fortescue’s chief executive, said.

Fortescue said it had worked with indigenous groups to protect and avoid nearly 6,000 heritage sites threatened by its mining activities.

Miners must balance the need to replace the ore that they unearth with respecting the interests of indigenous groups. Fortescue pointed out that the iron-ore industry has been a pillar of Australia’s economy as it emerges from a first recession in 29 years.

“A moratorium would unnecessarily stall mining, infrastructure and other activities for an unknown and possibly extended period,” said Tania Constable, chief executive of Minerals Council of Australia, an industry group.

Still, many investors feel the industry needs to do more, and have pushed for leadership changes when standards fall short. Rio Tinto Chief Executive Jean-Sébastien Jacques and two other executives were ousted after several investors criticized the company’s initial response to the caves’ destruction because no one had been held accountable.

Hesta, an Australian pension fund for health-care workers, said it strongly supports the recommendation that companies with existing heritage approvals, known as Section 18 permissions, suspend related works until they can verify consent by traditional landowners.

“The inescapable findings of the inquiry are that Aboriginal heritage sites remain vulnerable to destruction,” said Debby Blakey, Hesta’s chief executive. “It would be unacceptable to investors that boards of mining companies are not actively and transparently seeking to understand their exposure to this risk.”

Kim Christie, an iron-ore analyst at Wood Mackenzie, said a near-term squeeze on commodities supply from Australia isn’t likely. The final report from the inquiry won’t be finalized until next year. Still, there is a risk of higher mining costs and delays to expansions or new mines later as miners sharpen their focus on heritage issues and consultation with traditional owners, she said.

“Certainly moving forward if there is going to be that greater level of tightness [in supply] it could support prices higher than we otherwise would have thought,” Ms Christie said.

Scrutiny will especially fall on Rio Tinto. A moratorium on new heritage consents could affect up to 12 projects that Rio Tinto has planned over the next five or so years to maintain its iron-ore production at current rates, Goldman Sachs said. That means there is a risk that Rio Tinto won’t ship 327 million tons of iron ore next year as the bank had earlier forecast.

Rio Tinto said it is reassessing its mining operations in places with identified heritage sites that could be affected over the coming two years.

“I think Rio Tinto would rather forgo a few tons than their reputation,” said Ms Christie, of Wood Mackenzie.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026

Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.

By Laura Saunders
Fri, Oct 9, 2026 4 min

Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.

This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.

Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.

Here are three strategies useful for functional families.

Intrafamily loans

It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.

But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.

If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.

To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.

In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.

If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.

Asset gifts

Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.

The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.

Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.

However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.

These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.

But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.

Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.

The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.

Sellner doesn’t worry about his children using the funds for another purpose.

“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.

Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.

Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.

Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”

Disclaimers

A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.

Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.

Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.

Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.