Crypto is ailing. Sam Bankman-Fried is betting a billion dollars he can fix it.
The chief executive of cryptocurrency exchange FTX Trading Ltd. has appointed himself the industry’s saviour—and crypto investors are closely watching his moves after months of market carnage. This year, he bailed out a troubled digital-currency lender and tried to stabilize another. He acquired crypto exchanges in Canada and Japan. He appeared in magazine ads opposite supermodel Gisele Bündchen in a bid to keep mainstream investors enthusiastic about crypto despite the downturn.
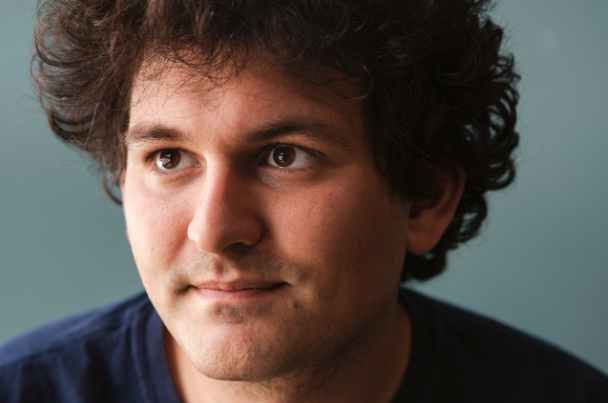
That kind of speed is routine for Mr. Bankman-Fried, a 30-year-old billionaire with a mop of curly hair who sleeps a few hours a night and toys with a fidget spinner during interviews. Last year, when regulatory scrutiny of crypto led Mr. Bankman-Fried to move FTX’s headquarters from Hong Kong to the Bahamas, dozens of employees relocated to the island nation within about a month.
Mr. Bankman-Fried says his ultimate goal is to bring crypto to the masses. He wants to make FTX a household name and use the technology behind bitcoin to reinvent traditional finance, including the stock market and ordinary consumer payments.
He has a lot of work to do. More than a decade after bitcoin’s birth, proponents still struggle to explain the value of digital currencies to a broad audience. Bitcoin has fallen nearly 70% from its November peak and the crash has erased $2 trillion of value from the crypto market, hurting millions of investors.
Not all of Mr. Bankman-Fried’s moves have paid off. An investment in Japan has proved rocky for FTX. And the trading firm he owns alongside FTX, Alameda Research, took losses when it tried to prop up troubled crypto lender Voyager Digital Ltd. Alameda lent Voyager $75 million and increased its stake in the company to 9.5%—only for Voyager to file for bankruptcy less than two weeks later.
“We want to do what we can to stem contagion, and sometimes that’s going to mean that we try to help out in cases where it’s not enough,” Mr. Bankman-Fried said. “If that never happened, I’d feel that we were being way too conservative.”
Like other crypto exchanges, FTX’s core business is to facilitate the buying and selling of digital currencies, and it takes a small cut of transactions. The firm has grown into a juggernaut since it was founded three years ago. With only about 300 employees, FTX is the world’s third-biggest crypto exchange by volume, doing US$9.4 billion worth of trades on an average day, according to data provider CoinGecko.
The firm made net income of US$388 million on $1.02 billion of revenue last year, according to a person familiar with the matter. It has stayed profitable in 2022 even as crypto prices slumped, Mr. Bankman-Fried said. FTX was valued at US$32 billion during its last funding round in January.
Now, with bitcoin hovering around $21,000—roughly in line with its level in late 2020, before last year’s big bull market—Mr. Bankman-Fried says the worst is over.
“Anything could happen, obviously, but as far as I know, we’ve seen most of the contagion already flushed out of the system,” he said.
Expanding an empire
The plea for help from the CEO of BlockFi Inc., a digital-currency lender, came on a Saturday evening in June. Mr. Bankman-Fried saw the message around 11 p.m. after playing padel, a tennis-like sport, with colleagues. He jumped into his Toyota Corolla with fellow FTX executive Ramnik Arora, turned on the air conditioning and returned the call.
BlockFi was essentially a crypto bank, taking deposits and lending them to borrowers that use the funds for trading purposes. In return, depositors earned interest on their digital money—usually at much higher rates than traditional banks offered on dollar deposits. BlockFi and other crypto lenders did brisk business until May, when the swift collapse of two cryptocurrencies called TerraUSD and Luna sent shock waves through the market and blew up hedge fund Three Arrows Capital Ltd., one of the biggest borrowers in crypto.
Fears of a 2008-style financial contagion spread. On June 12, a popular crypto lender called Celsius Network LLC suspended withdrawals. Other lenders, including BlockFi and Voyager, were threatened with the crypto equivalent of a run on the bank.
The crash set off rounds of calls into FTX’s headquarters in the Bahamas. Around 15 crypto firms sought money from FTX during a two-week stretch in June, including “miners” who run computer algorithms to generate bitcoin, as well as Celsius itself, Mr. Arora recalled.
Celsius, which has since filed for bankruptcy, didn’t respond to a request for comment.
FTX concluded that Celsius was beyond saving, FTX executives said, but that BlockFi was healthier. Following a Sunday morning Zoom meeting with BlockFi’s leadership on June 19, the day after the initial call from his car, Mr. Bankman-Fried decided to push for a deal.
By throwing BlockFi a lifeline, Mr. Bankman-Fried also seized the opportunity to expand his empire.
In the final deal unveiled on July 1, FTX agreed to loan BlockFi $400 million with an option to buy the firm for up to US$240 million. That price is a steal compared with the $4.75 billion valuation that BlockFi reached in July 2021, according to PitchBook data.
“It’s certainly not the outcome that we were expecting last summer,” BlockFi CEO Zac Prince said, but he called the FTX deal a win for the company and its clients. Unlike other offers BlockFi received, which could have forced BlockFi’s retail customers to lose part of their deposits, the FTX transaction was designed to keep depositors whole.
BlockFi says it has more than 650,000 funded accounts. If FTX ends up buying BlockFi, it will expand into the lending market, adding the crypto version of a big bank to Mr. Bankman-Fried’s portfolio.
Mr. Bankman-Fried says he wants to turn FTX into a sort of financial supermarket, offering everything from lending to stock trading to payments.
“The idea generating this is, ‘What do you actually want to do with your money, as the typical consumer? What are the things that are actually valuable for your day-to-day life?’” he said.
Mr. Bankman-Fried is a longtime vegan. He majored in physics at the Massachusetts Institute of Technology and worked for quantitative-trading giant Jane Street Capital for three years before diving into crypto. He is the son of two professors at Stanford Law School.
Bloomberg recently estimated his net worth at $11.9 billion, down from nearly $26 billion last year before the crypto crash. He is an adherent of effective altruism, a philosophical movement that says individuals should maximize their positive impact on society by making substantial money and giving it away. His favoured causes include pandemic prevention and preventing artificial intelligence from harming humanity.
People close to him express surprise at how naturally Mr. Bankman-Fried became a public figure. He has become a regular in Washington, testifying before Congress, promoting FTX’s agenda and lobbying for the crypto industry.
“He has had to transition from talking to a purely crypto audience to dealing with lawmakers, journalists and the public,” said Chris McCann, a partner at Race Capital, an early investor in FTX. “In 2019 he didn’t have a lot of those skill sets. He was much more of a shy, quirky, geeky person.”
Mr. Bankman-Fried’s first headquarters was a rented house in Berkeley, Calif., where he started Alameda Research in 2017—outfitted with desks and computers bought on Amazon. He later moved Alameda to Hong Kong, where crypto regulation was lighter than in the U.S.
Alameda sought to capture profits from the bitcoin market, where a mishmash of exchanges enabled arbitrage opportunities—the ability to buy a coin in one location and sell it elsewhere for more. One early strategy involved buying bitcoin in the U.S. and then selling it in Japan, where it commanded a premium.
He launched FTX in 2019, betting that his team could build a better exchange than the incumbents. Last year, amid mounting scrutiny of crypto by global regulators, Mr. Bankman-Fried decided to move FTX’s headquarters to the Bahamas, where the government had established a crypto-friendly regulatory regime.
Today FTX is based in an office park ringed by palm trees and dominated by a sun-baked parking lot. Mr. Bankman-Fried lives in a nearby luxury apartment complex. Although he has a reputation for living frugally—he has long lived with housemates and often sleeps on a beanbag at work—real-estate records show a unit of FTX paid $30 million for a five-bedroom penthouse there.
Mr. Bankman-Fried said he’s one of 10 FTX colleagues who share the apartment. “Obviously, it would be a ridiculous place for me to be living alone,” he said.
‘Salvage our business’
FTX expanded earlier this year by acquiring Japanese crypto exchange Liquid, which was hit by a $97 million hack in August 2021.
Shortly after the hack, Seth Melamed, then a Liquid executive, was getting on a plane to Tokyo. Liquid faced insolvency, customers were angry, and Mr. Melamed worried that Japanese police might arrest him at the airport. He wrote to Mr. Bankman-Fried on the Telegram messaging app.
His note read: “Fully understand this unusual, but if FTX would consider investing or acquiring Liquid it would salvage our business and benefit the crypto community more broadly.”
The plane had no Wi-Fi. When it landed, he was relieved to find no police waiting for him and a response from Mr. Bankman-Fried: “happy to take a look!”
A few days later, FTX agreed to loan Liquid $120 million, keeping it afloat and setting the stage for the takeover.
It wasn’t an entirely smooth acquisition. FTX ended up losing thousands of Japanese customers who were already using FTX and refused to move over to the local unit regulated by Japan’s Financial Services Agency, a person familiar with the matter said.
Mr. Melamed, now chief operating officer of FTX Japan, said, “We are confident we can return to previous levels of activity by Japanese users at FTX before the end of this year and surpass this by 2023.”
In June, FTX agreed to buy Canadian crypto exchange Bitvo Inc. FTX has also amassed licenses to provide financial services in Australia, Dubai and the European Union as part of an international push.
FTX’s ambitions extend to traditional markets. After buying a registered U.S. brokerage firm last year, it recently allowed American customers to trade stocks on its app alongside bitcoin. In May, Mr. Bankman-Fried spent $648 million of his personal fortune to buy a 7.6% stake in Robinhood Markets Inc., maker of the popular trading app. He revealed his purchase after Robinhood stock plunged nearly 80% from its initial public offering; the shares have edged slightly higher since then.
Mr. Bankman-Fried is the majority owner of both FTX and Alameda, an arrangement that has drawn criticism from crypto skeptics as well as some digital-currency traders. In traditional markets such as stocks and futures, exchanges are required to be neutral platforms that don’t benefit one trader over another. Regulators discourage them from being intertwined with trading firms, considering it a conflict of interest. No such restrictions exist in crypto.
Mr. Bankman-Fried said Alameda doesn’t get special privileges on FTX. While it was initially a major participant on FTX, helping to juice trading activity, it has since dropped to a small share of trading volumes, he said.
Last year Mr. Bankman-Fried resigned from his role as CEO of Alameda, saying he was spending most of his time on FTX. The firm continues to generate significant profits for him. One cryptocurrency wallet controlled by Alameda—where the firm holds some of its funds—has generated more than $550 million in trading profits since 2020, according to Nansen, a blockchain analytics firm.
FTX amassed a war chest of some $2 billion in a series of funding rounds in 2021 and early 2022, while crypto prices were still high. Investors in FTX included established asset managers such as Singapore state-owned investment company Temasek Holdings Pte. Ltd. and the Ontario Teachers’ Pension Plan. The funding allowed FTX to make acquisitions after crypto crashed.
Mr. Bankman-Fried said that FTX has a few billion in cash that it could use for other deals—money it keeps in dollars, not crypto.
Reprinted by permission of The Wall Street Journal, Copyright 2021 Dow Jones & Company. Inc. All Rights Reserved Worldwide. Original date of publication: August 23, 2022.


 7 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



