
Why Is Everyone So Unhappy at Work Right Now?
U.S. employees are more dissatisfied than they were in the thick of the pandemic

By VANESSA FUHRMANS
Wed, Nov 29, 2023 8:39am 5 min
5 min


U.S. employees are more dissatisfied than they were in the thick of the pandemic
5 min
Americans, by many measures, are unhappier at work than they have been in years.
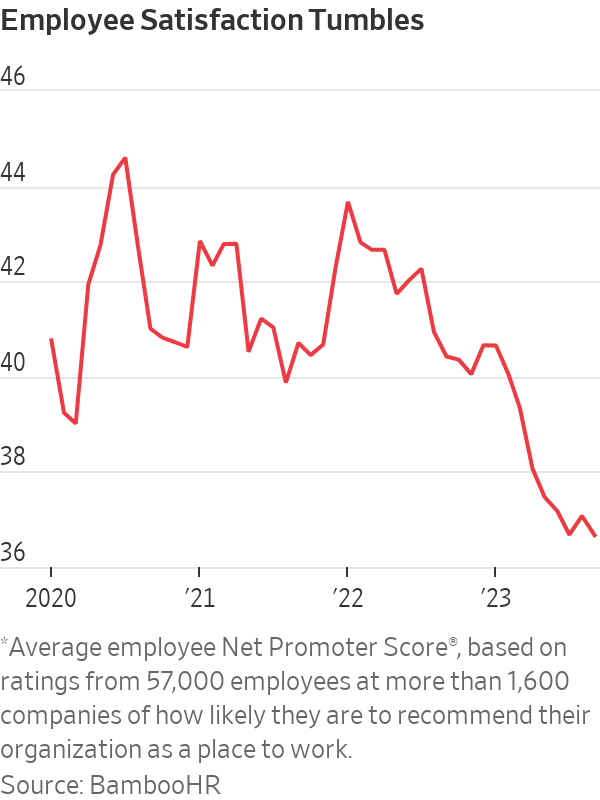
Despite wage increases, more paid time off and greater control over where they work, the number of U.S. workers who say they are angry, stressed and disengaged is climbing, according to Gallup’s 2023 workplace report. Meanwhile, a BambooHR analysis of data from more than 57,000 workers shows job-satisfaction scores have fallen to their lowest point since early 2020, after a 10% drop this year alone.
In interviews with workers around the country, it is clear the unhappiness is part of a rethinking of work life that began in 2020. The sources of workers’ discontent range from inflation, which is erasing much of recent pay gains, to the still-unsettled nature of the workday. People chafe against being micromanaged back to offices, yet they also find isolating aspects of hybrid and remote work. A cooling job market—especially in white-collar roles—is leaving many professionals feeling stuck.
Companies have largely moved on from pandemic operating mode, cutting costs and renewing a focus on productivity. The disconnect with workers has managers frustrated, and no quick fix seems to be at hand. Those in charge said they have given staff more money, flexibility and support, only to come up short.
The experiences of workers like Lindsey Leesmann suggest how expectations have shifted from just a few years ago. Leesmann, 38 years old, said she soured on a philanthropy job after having to return to the office two days a week earlier this year.
Prepandemic, she would have been happy working three days a week at home. “It would have been a dream come true.” Still, her team’s in-office requirements seemed like going backward, and made her feel that her professionalism and work quality were in doubt. Instead of collaborating more, she and others rarely left their desks, except for meetings or lunch, she said. Negative feelings followed her home on her hourlong commute, leaving her short-tempered with her kids.
“You try to keep work and home separate, but that sort of stuff is just impacting your mental health so much,” said Leesmann, who recently moved to a new job that requires five in-office days a month.
The discontent has business leaders struggling for answers, said Stephan Scholl, chief executive of Alight Solutions, a technology company focused on benefits and payroll administration. Many of the Fortune 100 companies on Alight’s client list boosted spending on employee benefits such as mental health, child care and well-being bonuses by 20% over the pandemic years.
“All that extra spend has not translated into happier employees,” Scholl said. In an Alight survey of 2,000 U.S. employees this year, 34% said they often dread starting their workday—an 11-percentage-point rise since 2020. Corporate clients have told him mental-health claims and costs from employee turnover are rising.
One factor is the share of workers who are relatively new to their roles after record levels of job-switching, said Benjamin Granger, chief workplace psychologist at software company Qualtrics. Many employers have focused more on hiring than situating new employees well, leaving many newbies feeling adrift. In other cases, workers discovered shiny-seeming new jobs weren’t a great fit.
The upshot is that the newest workers are among the least satisfied, Qualtrics data show—a reversal of the higher levels of enthusiasm that fresh hires typically voice. In its study of nearly 37,000 workers published last month, people less than six months into a job reported lower levels of engagement, feelings of inclusion and intent to stay than longer-tenured workers. They also scored lower on those metrics than new workers in 2022, suggesting the pay raises that lured many people to new jobs might not be as satisfying as they were a year or two ago.
“What happened to that honeymoon phase?” Granger said.
John Shurr, a 66-year-old former manufacturing engineer, took a job as an inventory manager at a heavy-equipment retailer in the spring in Missoula, Mont., after being laid off during the pandemic.
“It was a nice job title on a pretty rotten job,” said Shurr, who learned soon after starting that his duties would also include sales to walk-in customers.
When Shurr broached the subject, his boss asked him to give it a chance and said he was really needed on the showroom floor. Shurr, who describes himself as more of a computer guy, quit about a month later.
“I feel kind of trapped at the moment,” said Shurr, who has since taken a part-time job as a parts manager as he tries to find full-time work.
Long-distance relationships between bosses and staff might also be an issue. Nearly a third of workers at large firms don’t work in the same metro area as their managers, up from about 23% in February 2020, according to data from payroll provider ADP.
Distance has weakened ties among co-workers and heightened conflict, said Moshe Cohen, a mediator and negotiation coach who teaches conflict resolution at Boston University’s Questrom School of Business. He has noticed more employees calling co-workers or bosses toxic or impossible, signs that trust is thin.
Cohen’s corporate clients said their employees are increasingly transactional with one another. Some are coaching workers in the finer points of dialogue, such as saying hello first before jumping into the substance of a conversation.
“The idea of slowing down, taking the time, being genuine, trying to actually establish some sort of connection with the other person—that’s really missing,” Cohen said.
One Los Angeles-based consultant in his 20s, who asked to remain anonymous because he is seeking another job, said that when he started his job at a large company last year, his largely remote colleagues were focused on their own work, unwilling to show a new hire the ropes or invite him for coffee. Many leave cameras off for video calls and few people show up at the office, making it hard to build relationships.
“There’s zero humanity,” he said, noting that he is seeking another job with a strong office culture.
The share of U.S. companies mandating office attendance five days a week has fallen this year—to 38% in October from 49% at the start of the year—according to Scoop Technologies, a software firm that developed an index to monitor workplace policies of nearly 4,500 companies.
Some companies have reversed flexible remote-work policies—in large part, they said, to boost employee engagement and productivity—only to face worker backlash.
Not all the data point downward. A Conference Board survey in November 2022 of U.S. adults showed workers were more satisfied with their jobs than they had been in years. Key contingents among the happiest employees: people who voluntarily switched roles during the pandemic and those working a mix of in-person and remote days. But that poll was taken before a spate of layoffs at high-profile companies and big declines in the number of knowledge-worker and professional jobs advertised.
At Farmers Group, workers posted thousands of mostly negative comments on the insurer’s internal social-media platform after its new CEO nixed the company’s previous policy allowing most workers to be remote.
Employees like Kandy Mimande said they felt betrayed. “We couldn’t get the ‘why,’” said the 43-year-old, who had sold her car and spent thousands of dollars to redo her home office under the remote-work policy. She shelled out $10,000 for a used car for the commute. A company spokesperson said that not all employees will support every business decision and that Farmers hasn’t seen a significant impact on staff retention.
During a brief leave, Mimande realised she no longer felt a sense of purpose from her product-management job. She resigned last month after she and her wife decided they could live on one salary.
She now helps promote a band and pet-sits. “It’s so much easier for me to report to myself,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
