
Google Fails to ‘Wow’ as AI Bills Mount
Advertising business faces tough growth comparisons, while AI spending continues to surge

By DAN GALLAGHER
Thu, Jul 25, 2024 9:10am 3 min
3 min


Advertising business faces tough growth comparisons, while AI spending continues to surge
3 min
It’s good to be Google these days. But it isn’t easy, and it will keep getting harder.
Second-quarter results from parent company Alphabet on Tuesday afternoon showed strength in advertising and cloud revenue along with a record high in operating profit as the Silicon Valley titan, once known for lavish employee perks, continues to clamp down on most costs, save for those designed to build out generative artificial intelligence capabilities .
But the results also offered “no excitement,” in the words of Jefferies analyst Brent Thill . Overall revenue exceeded Wall Street’s consensus projection by just 0.6%—the lowest beat percentage in at least five years, according to FactSet. YouTube advertising revenue also came in lower than analysts expected. Alphabet’s previous report, three months ago , offered bigger positive surprises in both revenue and earnings growth, with the announcement of the company’s first-ever dividend thrown in for good measure. Alphabet’s stock had jumped nearly 17% since that report; the shares gave up about 4% in premarket trading on Wednesday.
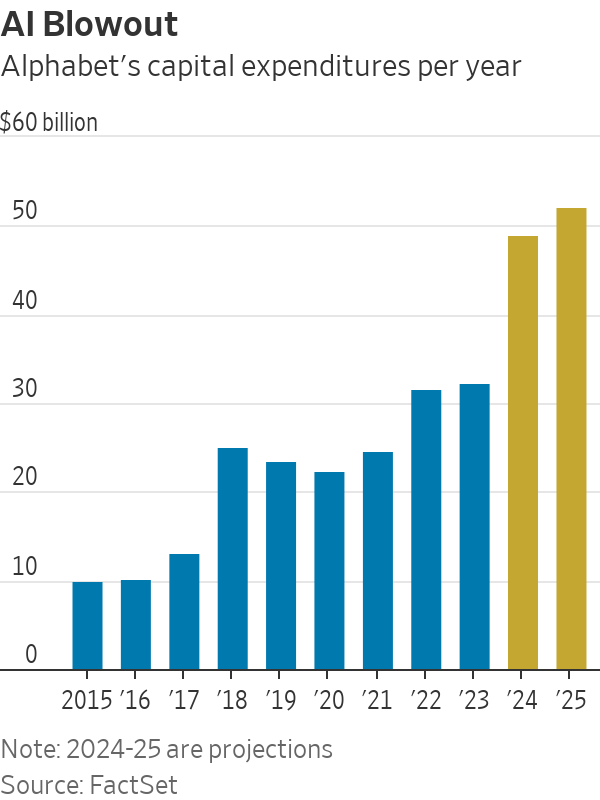
Tuesday’s results also set the stage for what might be a more challenging second half of the year. For one, comparisons will be tougher as the second half of last year had Google nearly recovered from an earlier advertising slump. Google also didn’t fully ramp up its spending on AI infrastructure until well into the second half of 2023; capital expenditures in the first half of 2023 were barely half of the $25.2 billion the company has spent in the first half of this year.
That spending won’t be taking a breather any time soon, even as Google has pared back other costs and even brought its head count down by more than 1,300 positions in the most recent quarter. Alphabet said Tuesday that capex will be at or above $12 billion a quarter for the second half of the year, likely leading to a total outlay of more than $49 billion for the year—84% higher than what the company has averaged annually over the past five years.
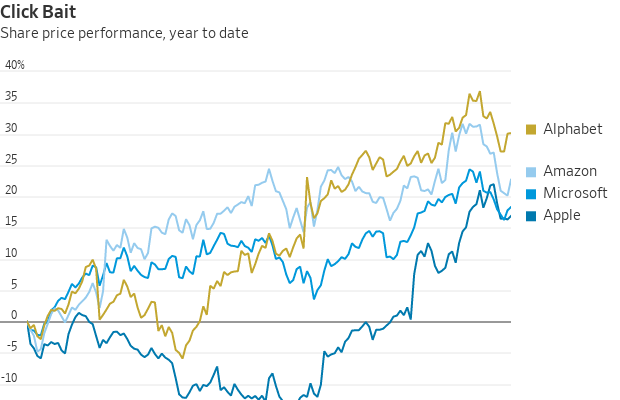
“Look, obviously we are at the early stage of what I view as a very transformative area,” Alphabet Chief Executive Sundar Pichai said during Tuesday’s earnings call when asked by an analyst about the company’s AI investments. He added that “the risk of underinvesting is dramatically greater than the risk of over investing for us here,” not mentioning the record amounts of capex that tech rivals Microsoft , Amazon.com and Meta Platforms are pouring into the same thing.
Google has the resources: Alphabet’s net cash pile of nearly $98 billion is substantially bigger than those of even its deep-pocketed peers. But putting that money to work is getting to be a challenge. The Wall Street Journal reported Monday that Google’s talks to acquire cybersecurity startup Wiz have fallen apart. The purported $23 billion deal would have been Google’s largest ever and most certainly would have drawn the type of close regulatory scrutiny that has lately been keeping tech mergers in limbo for 18 months or more. Such an uncertain payoff reportedly was a concern among Wiz and its investors; Google’s acquisition of Fitbit in 2021 for less than one-tenth that price took nearly 15 months to close.
Google is also going back to the drawing board on a long-running plan to phase out the use of internet tracking technology known as “cookies,” despised by privacy advocates but depended upon by advertisers. Google was building up an alternative technology called “privacy sandbox,” but that plan drew a lot of opposition from advertisers and regulators worried that it would further cement the company’s internet advertising dominance. Google said Monday it would instead offer users a prompt to allow them to opt out of cookie tracking.
That move is unlikely to dent Google’s powerful search ad business. But that and the failed Wiz talks show the growing constraints the company is operating under as regulators look even more closely at big tech’s position, and judges and juries start weighing in. A verdict in the federal government’s antitrust case against Google is expected before the end of the year and could result in a ruling that would seek a breakup of the $250-billion-a-year advertising juggernaut.
Google’s latest results were good, but good isn’t always enough.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
