
A Car That Costs as Much as a House Is the Latest ‘Dream’ of America’s Upper Middle Class

By Jim Motavalli
Tue, May 14, 2024 12:18pm 5 min
5 min

 5 min
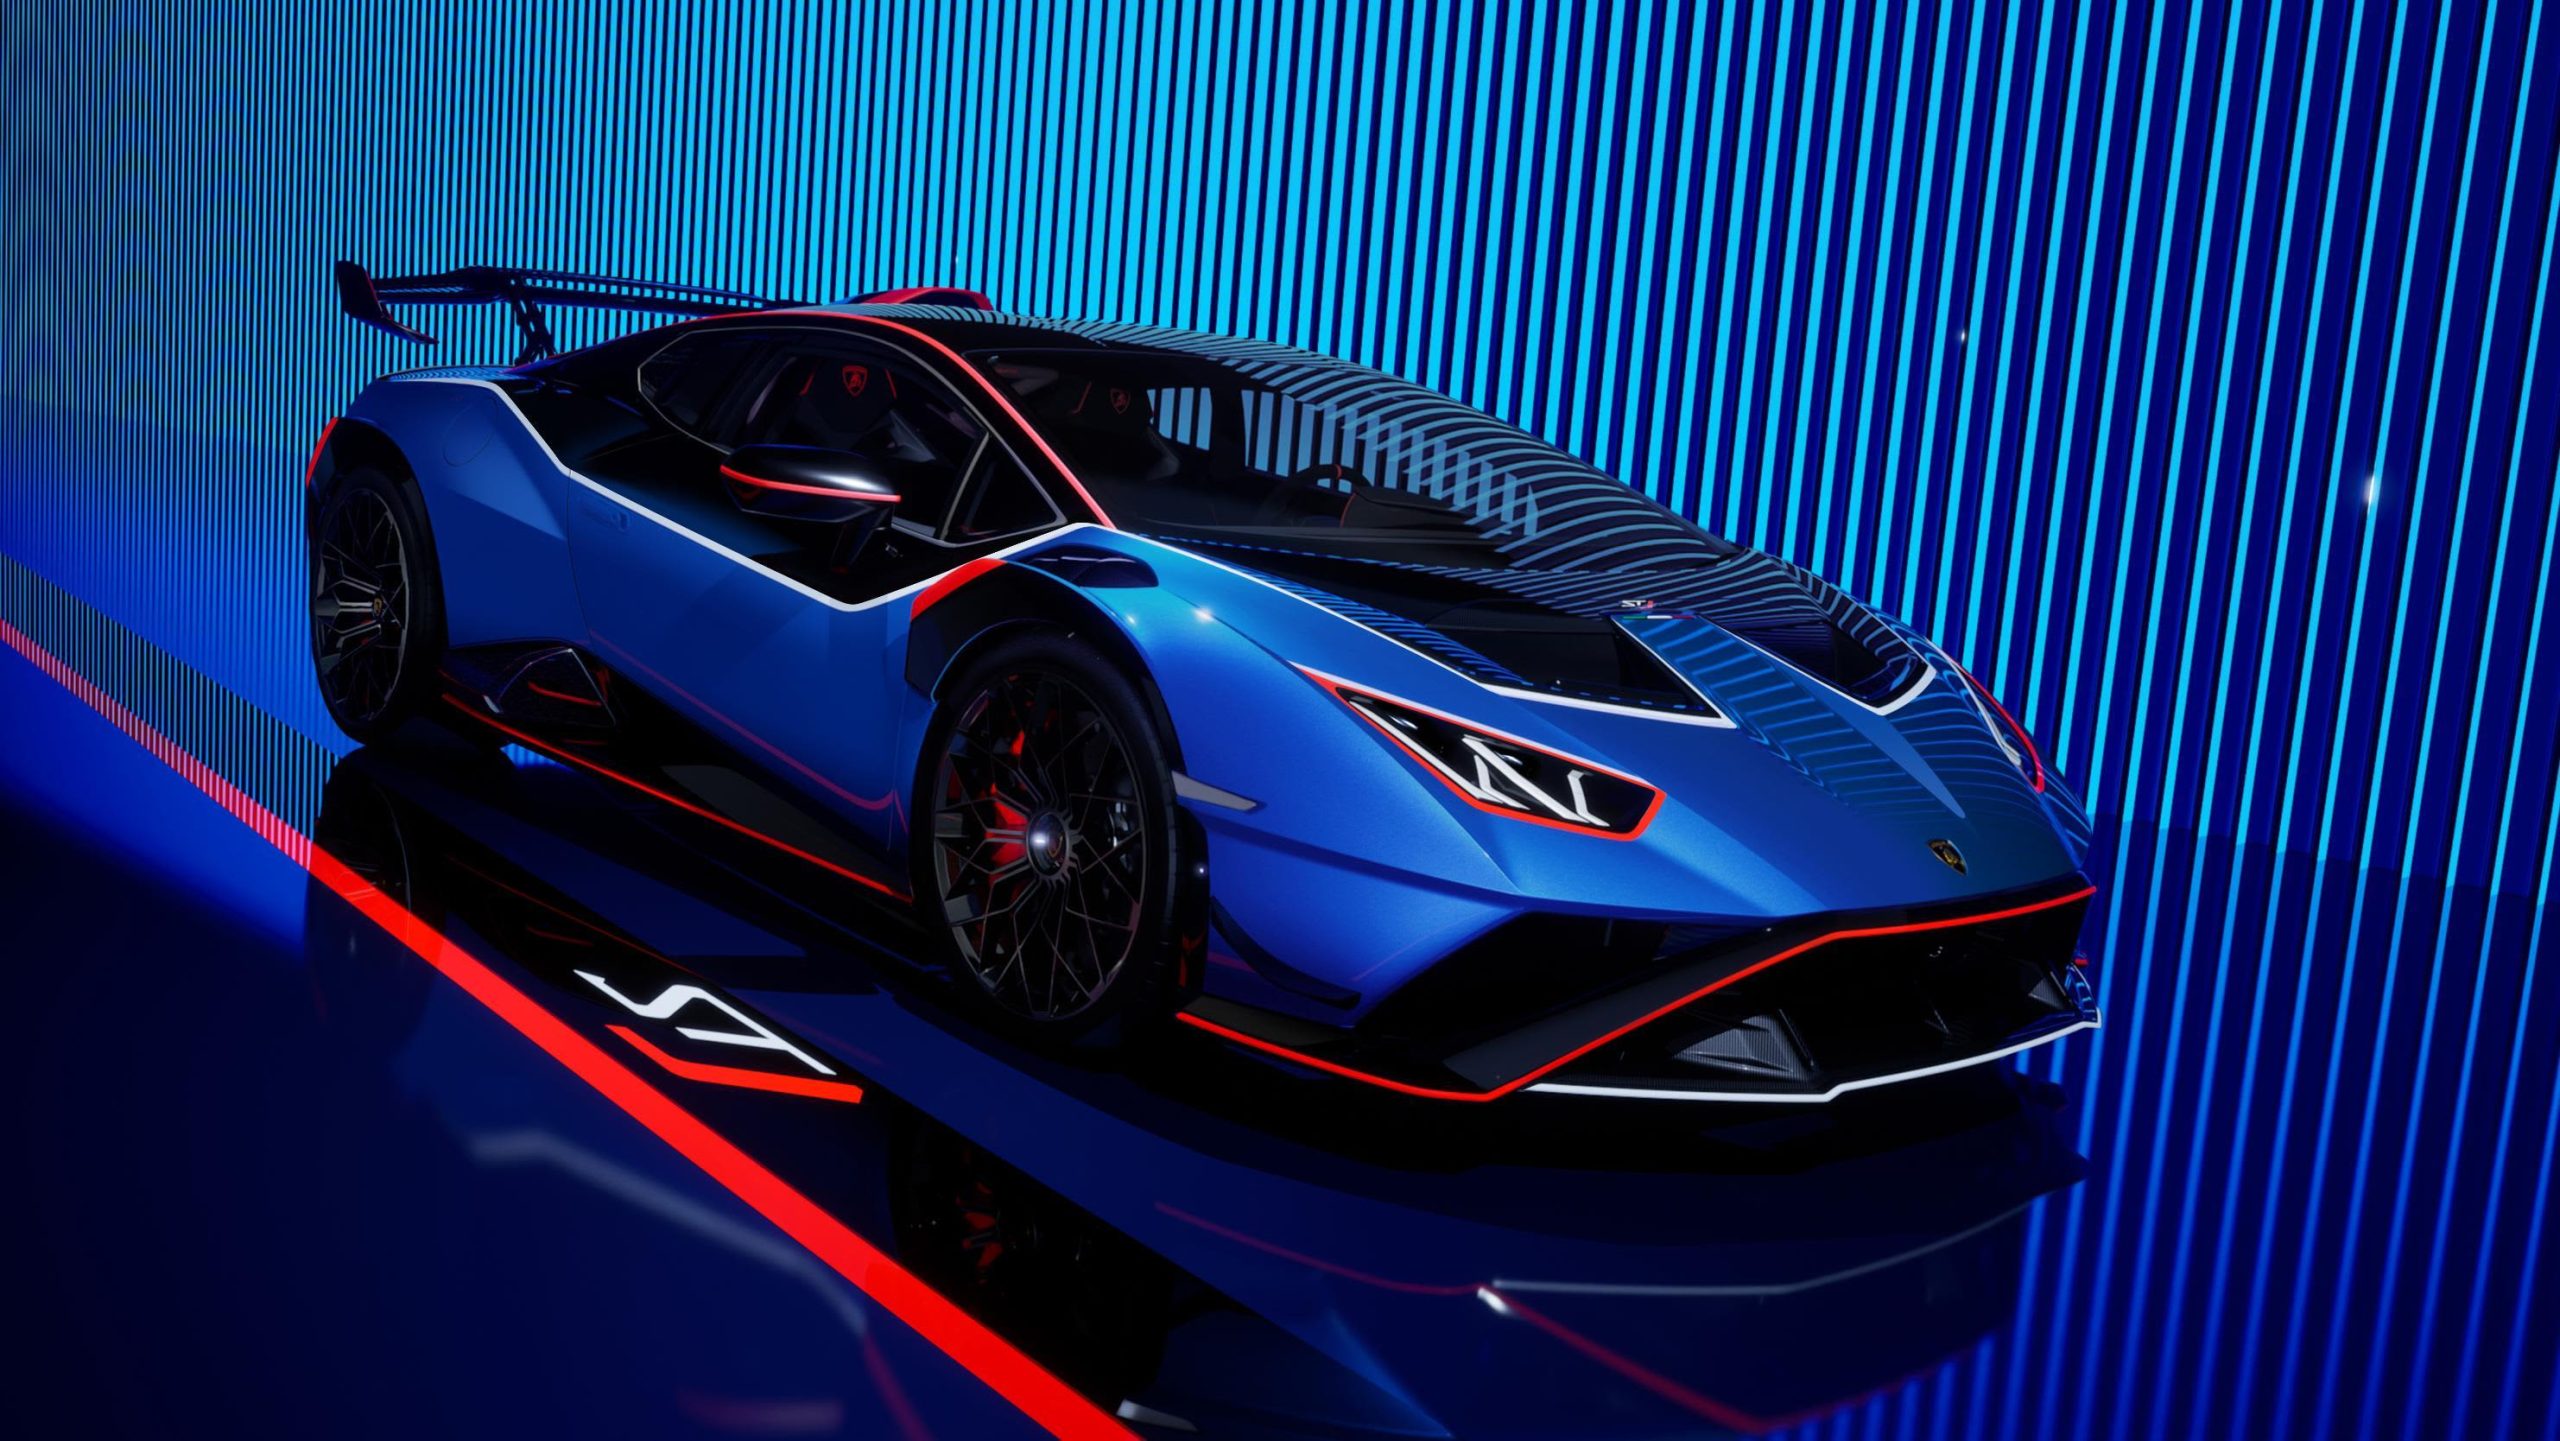
When Lamborghini announced its end-of-an-era Huracán Super Trofeo Jota last April, in an edition of just 10, it sold out immediately. No price was announced, though it was probably above US$400,000. That hardly deterred buyers eager to own one of the last Huracán supercars.
Ferrari’s limited-edition 812 Competizione and 812 Competizione A in 2021? The 999 hardtops (US$598,567) and 599 targas (US$694,549) were gone very quickly, though maybe not in 60 seconds.
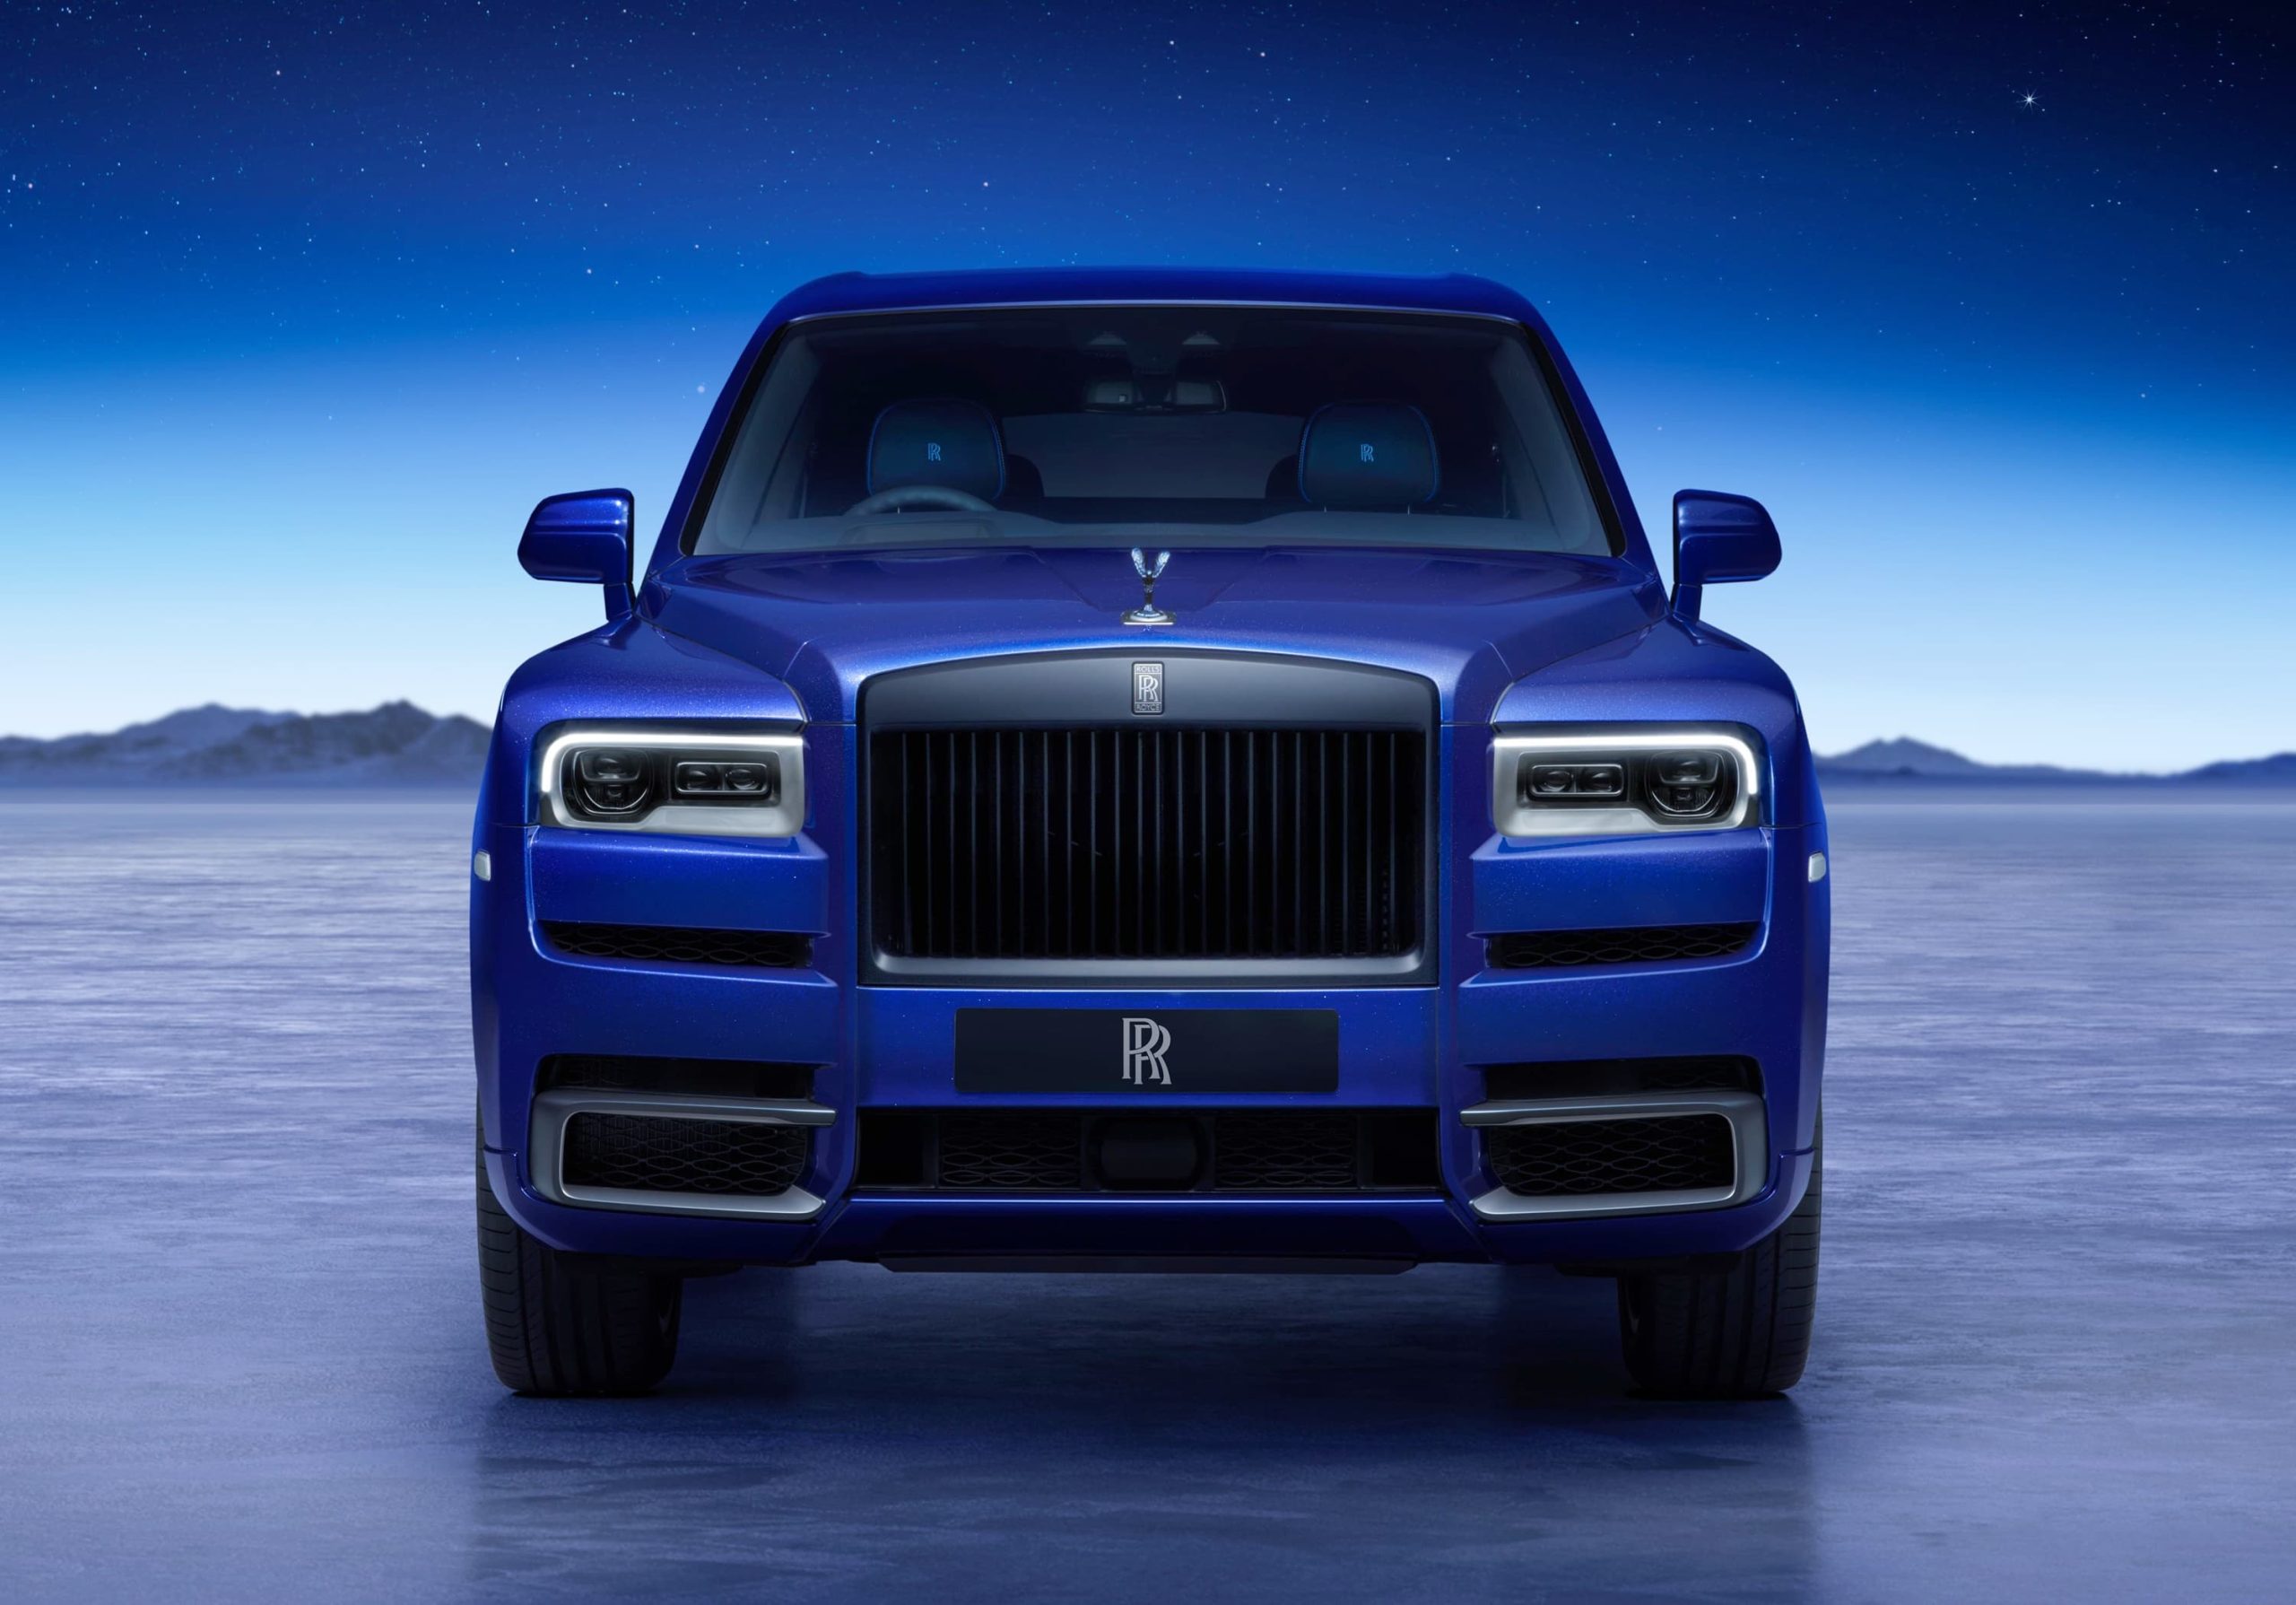
Meanwhile, the Rolls-Royce Black Badge Cullinan “Blue Shadow Private Collection” cars that appeared in 2023, just 62 in number, disappeared within two weeks. Black Badge Series II Cullinans start at US$470,000 for 2025, but these special editions are pricier—more than US$600,000.
“The primary driver for Rolls-Royce Cullinan clients is not price, but a combination of lifestyle and personalised exclusivity,” says Martin Fritsches, president and CEO of Rolls-Royce Motor Cars North America.
The global supercar market was US$17.5 billion in 2023, reports MarketResearch.biz, but it could soar to US$24.9 billion by 2033. Supercars, Business Research Insights says, “are a symbol of luxury, performance and status, appealing to affluent buyers who seek exclusivity and the thrill of driving a high-powered machine. … With a growing global economy and increasing wealth, the demand for supercars continues to rise.”
In the U.S., the American International Automobile Dealers Association reported that luxury brand deliveries in 2023 were more than 2.6 million, accounting for 17% of U.S. light-vehicle sales. That was up from 2.2 million sales in 2021 (and a 14.7% share).
Supercar sales represent small totals, but big potential profits. It’s a niche with an increasing number of startups, including battery cars from companies such as Lucid and Rimac. Ferrari, for instance, reported a US$1.36 billion profit in 2023, a yearly record. That’s despite producing only 13,221 units in the year. Ferrari has typically produced between 8,000 and 11,000 cars annually, but it’s one of the world’s most written-about, admired, and sought-after brands.
And Lamborghini had its best year in 2023, with an operating profit of US$777 million. That’s on sales of 10,100 globally. But each sale was a big ticket: The Huracán buyer in 2023 paid between US$212,090 and US$340,690. Volume didn’t help Tesla all that much. The company sold 1.8 million vehicles globally in 2023 (and had the world’s best-selling car in the Model Y), but has been experiencing declining profits.
This year, the supercar and luxury carmakers are revelling in the power of special editions and the one-of-one “bespoke” commission. Without having to make major changes to their existing models, the companies are able to greatly increase the price—via distinctive colours, interior appointments, and personalisation. Perhaps Tesla would do better if it too delved deeper into accommodating its eager customers with vast personalisation possibilities. Who wouldn’t want a one-of-10 SpaceX Edition of the Model Y?
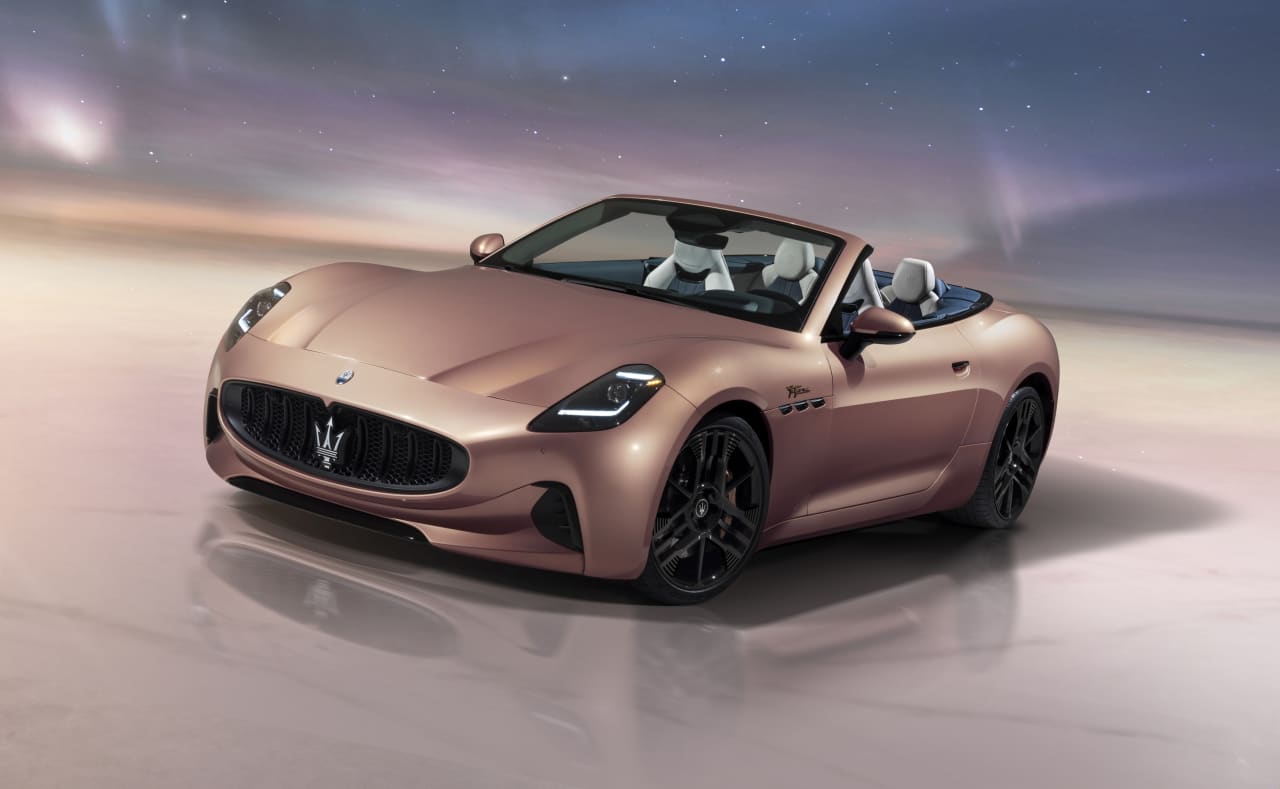
Meanwhile, established supercar makers are rapidly transitioning to electric and hybrid drive, motivated by international regulations that will ban internal-combustion engines by 2035. Maserati, for instance, is introducing electric “Folgore” versions of its GranCabrio convertible this year, and MC20 supercar in 2025. There will be a new electric SUV in 2027 and a four-door battery Quattroporte in 2028. Electrification is not likely to lead to either lower prices or lower demand, but there’s no certainty.
The Collector Market Is Cruising, Too
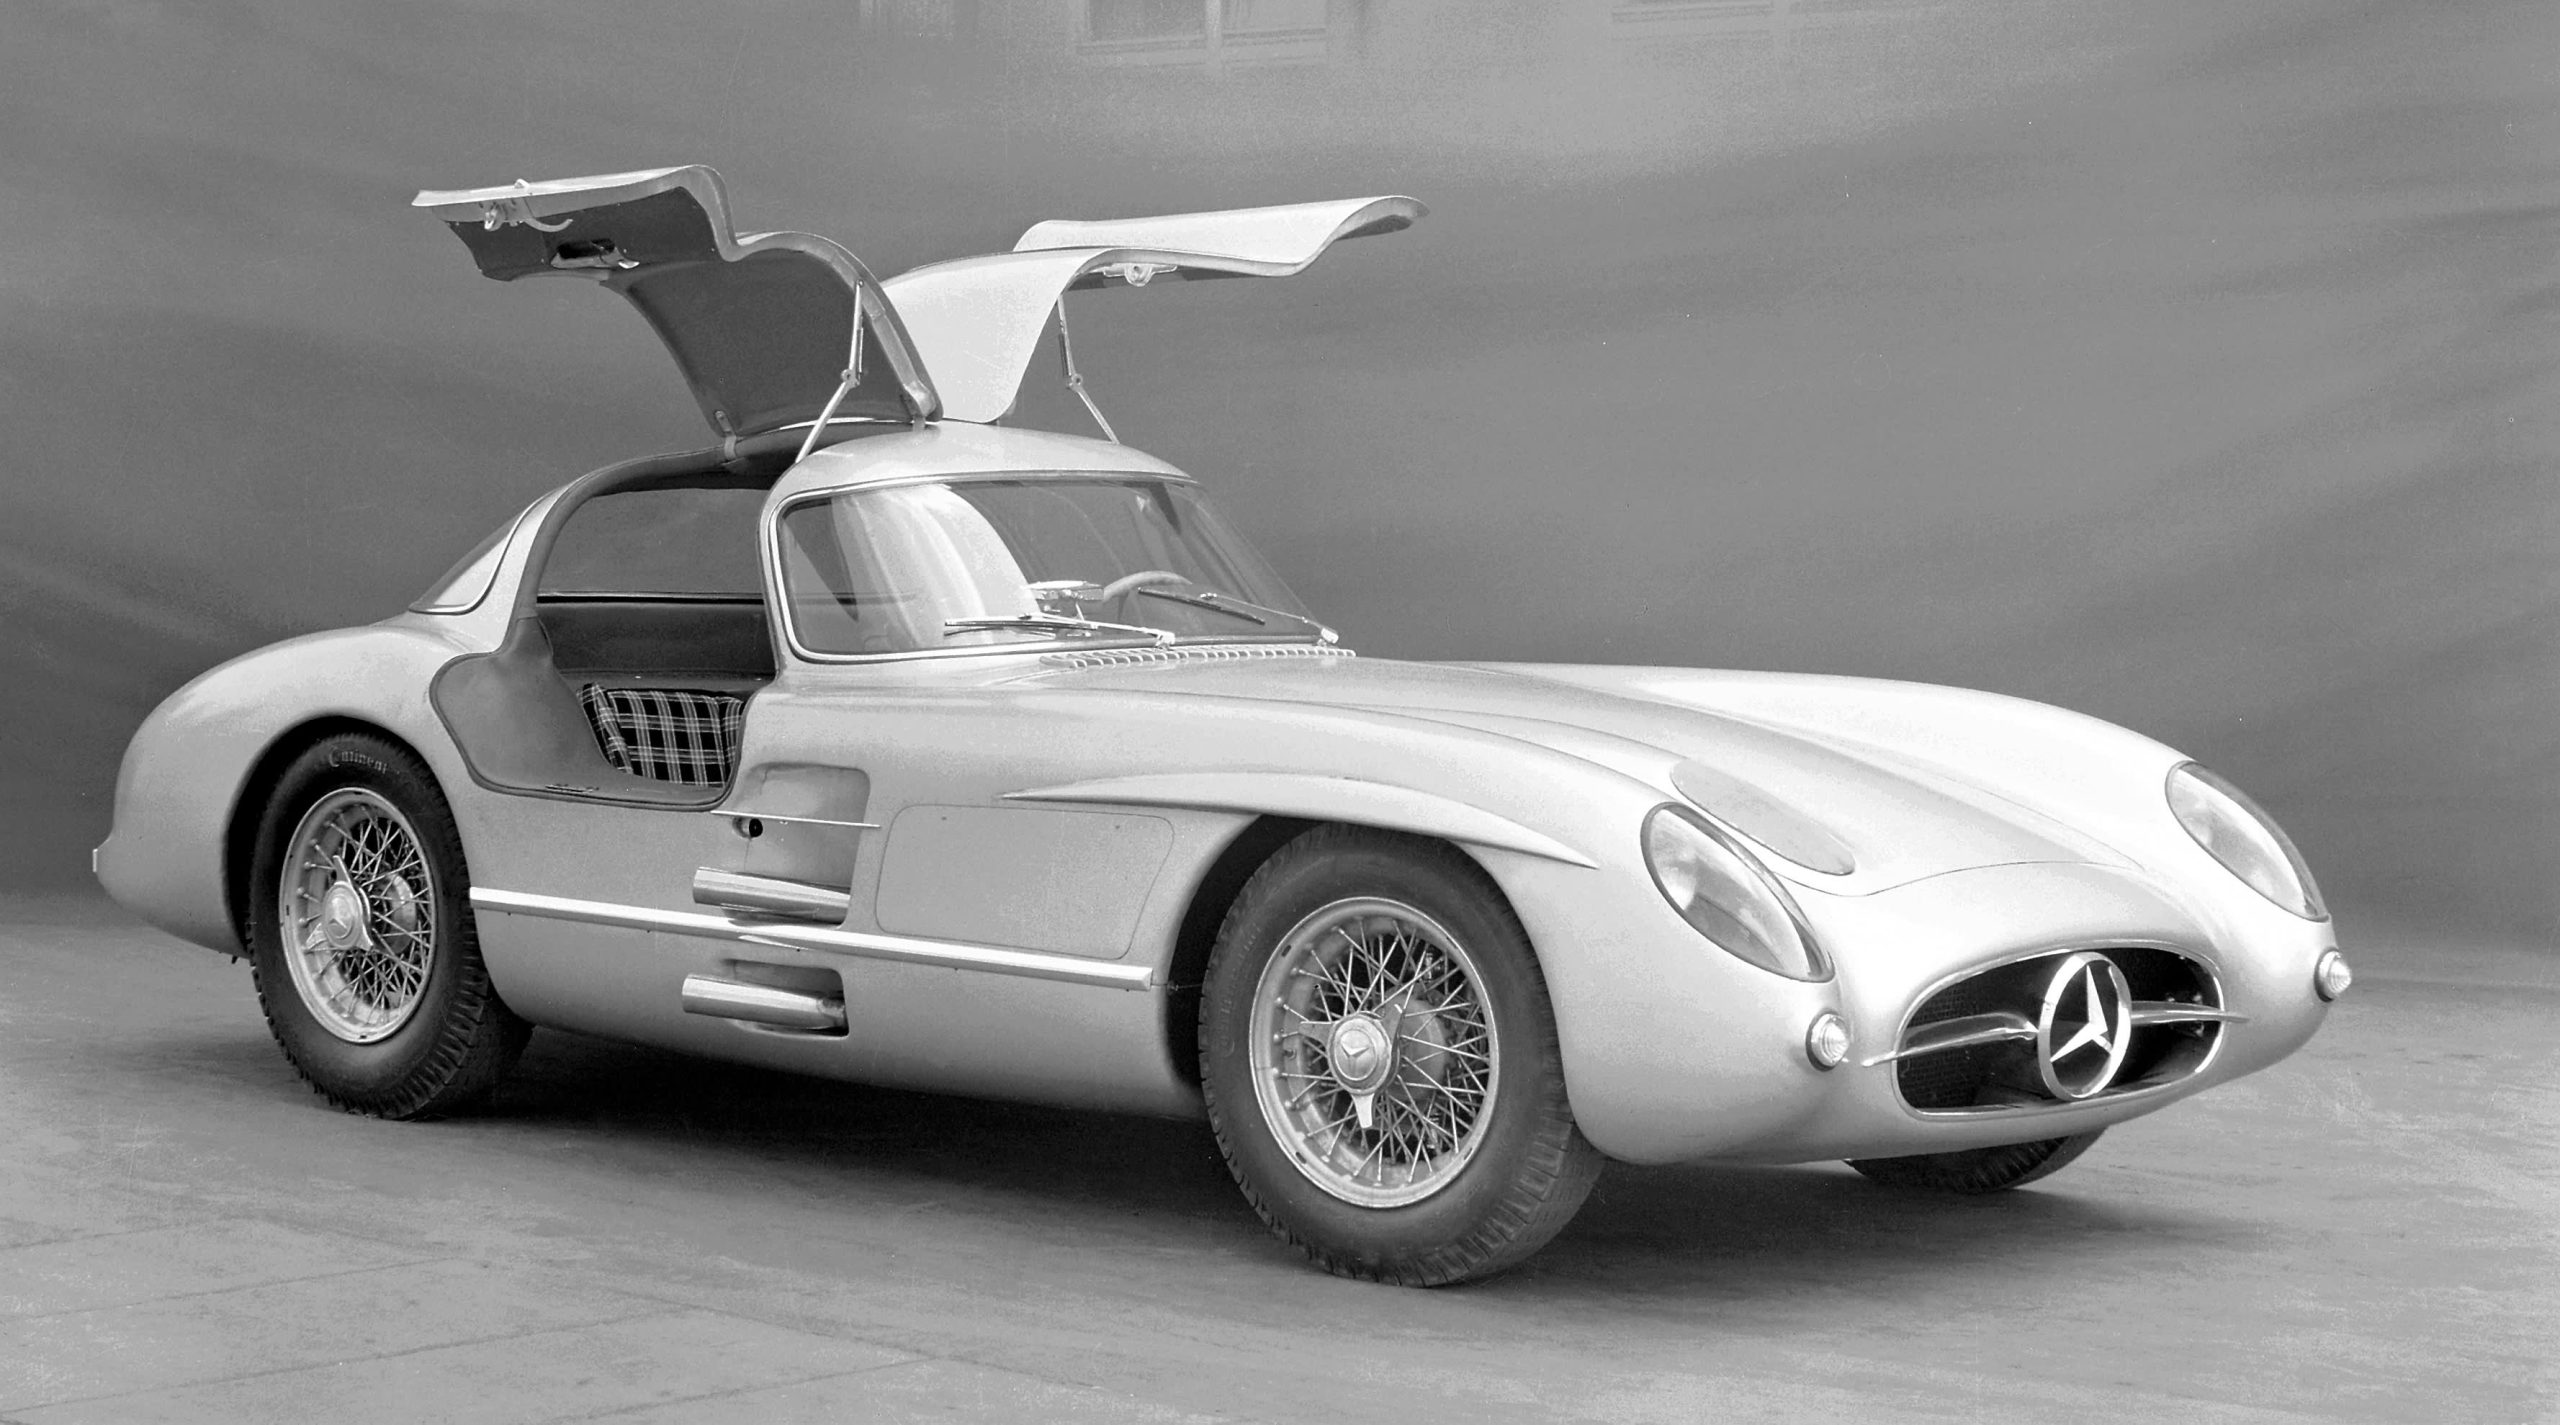
The market for collector vehicles above US$200,000 also remains quite healthy. The US$143 million paid for the 1955 Mercedes-Benz 300 SLR Uhlenhaut Coupe in 2022 surpassed the results of any other car sold at auction by more than US$90 million.
Critics who said that high-dollar buyers would never buy US$200,000-plus cars online (without seeing them in person) have been proven dramatically wrong, and the increase in online buying on sites like Bring a Trailer (BaT) and Cars & Bids has stoked rising values.
“March 2024 was the largest-volume month in our Premium Listings category since we launched it in 2019,” says Randy Nonnenberg, president and co-founder of BaT. “April 2024 followed on with 64 vehicles selling at over US$200,000 in value, with the top sale a Bugatti Chiron at US$3.075 million.”
Offerings in that price range from a US$250,000 1932 Ford hot rod coupe and a Lexus LFA to modern Ferraris and Ford GTs, Nonnenberg says. “The low transaction fees of our online platform make it very attractive for buyers of these expensive items when compared to other venues.”
Pre-owned supercars (and adjacent American muscle) often appreciate in the marketplace, with the rare (and most powerful) ones commanding huge prices.
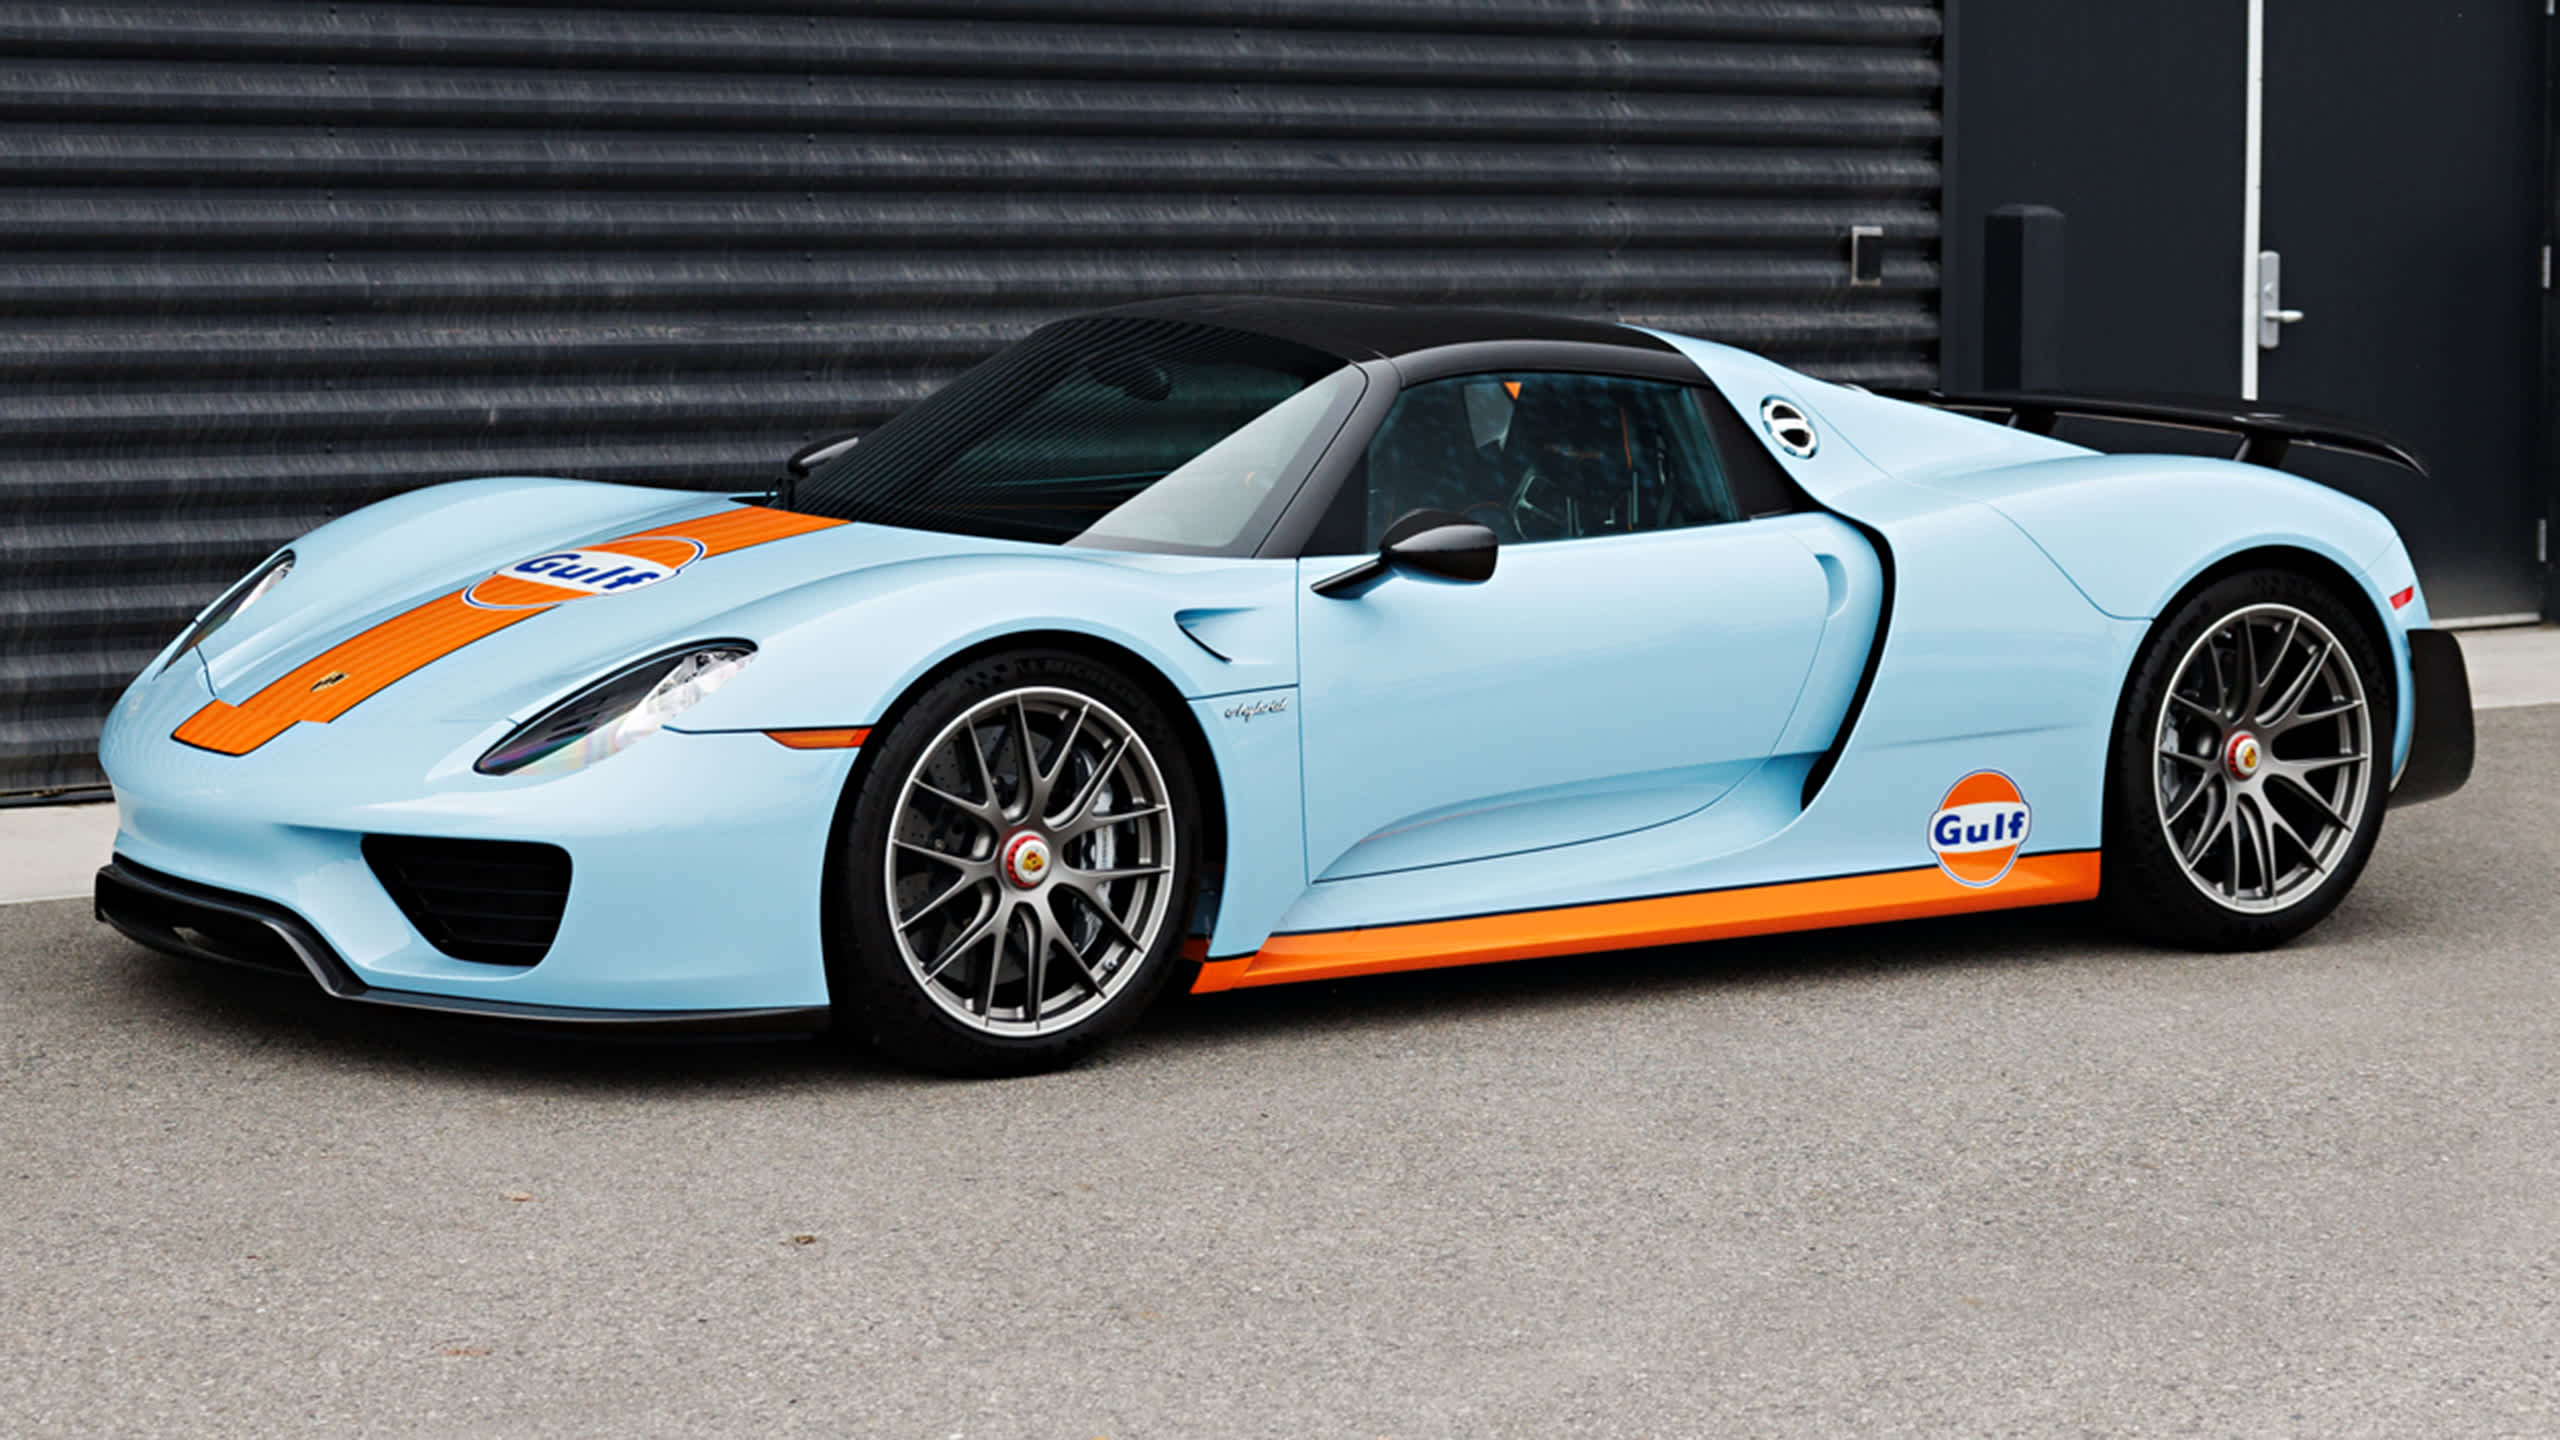
“The strong US$3.5 million paid at our Amelia Island auction in March 2024 for a Porsche 918 Spyder Weissach—as well as many other strong prices for contemporary supercars—demonstrates the strength in this segment,” says David Gooding , president of the Gooding and Company international auction house. Seven cars priced at more than US$10 million were offered at auction last year, reports Hagerty, with as many as 10 expected in 2024.
McKeel Hagerty , CEO and chairman at Hagerty, says the US$200,000 price point is an interesting one in the enthusiast car market.
“With a budget like that, you can buy some fantastic classics with a rich history, late-model supercars, or you can build a wide variety of the latest restomods [older cars restored with modern amenities],” Hagerty says. “These are the dream cars of the American upper-middle class.”
Hagerty says that US$200,000 would buy “a great, early Porsche 911 S or Jaguar Series 1 E-Type Roadster.” A supercar car lover might also find a Lamborghini Huracán or Ferrari 458 with “weapons-grade performance” in the price range, or a Plymouth Superbird and ‘66 Mustang GT350, he adds.
Despite the demand, Brian Rabold, vice president at Hagerty Automotive Intelligence, says that high-priced cars don’t necessarily appreciate as fast as some others when they age.
“In the past five years, the 87 vehicle generations in the Hagerty Price Guide with an average value between US$200,000 and US$500,000 have seen an average value growth of 9.24%. This lags behind the 35% average value growth seen in the remaining 1,351 vehicle generations,” Rabold says.
Nevertheless, he says the future “looks bright” for the US$200,000 to US$500,000 segment. “These vehicles are becoming more popular among collectors. Surprisingly, Baby Boomers (who hold most of the wealth in the country) are not driving this growth.” Hagerty is seeing more queries from Gen-X.
“Owning a desirable car or truck that you can drive, or show is much more fun than storing your stock certificates in a safe,” says Craig Jackson , chairman and CEO of the Barrett-Jackson auction house. “Plus, it can offer a long-term upside if you research before you buy.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
