As Generation X Approaches Retirement, Reality Still Bites
The ‘forgotten generation,’ born between 1965 and 1980, launched their careers at the start of a massive shift in how Americans work.
By HANNAH MIAO
Thu, Aug 22, 2024 8:50am 7min
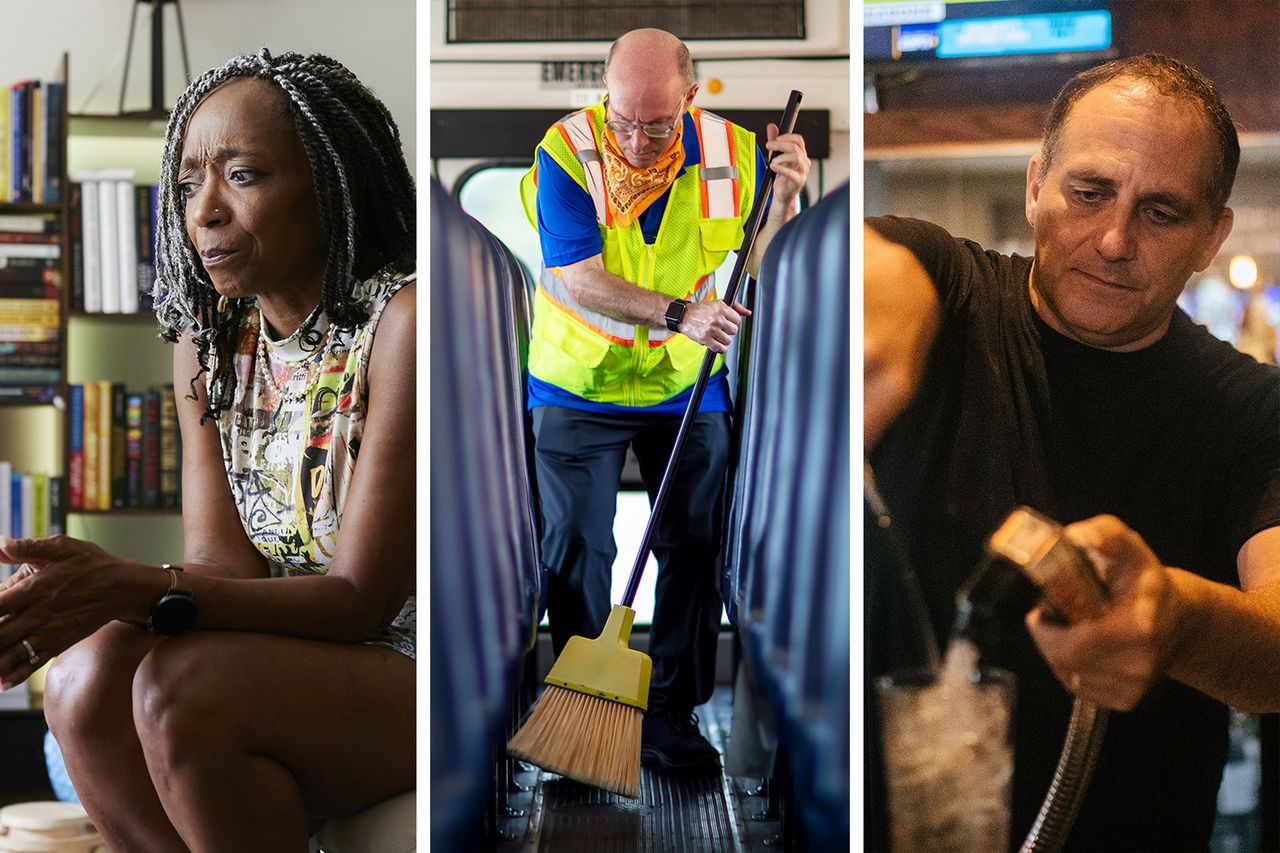
David Bryan, with cap; Darling ‘Diva’ Moore, John Kotrides. PHOTO: ANDREW J. WHITAKER FOR WSJ, JIMENA PECK FOR WSJ, ANGELA OWENS/WSJ
The oldest members of Gen X are turning 60 next year. Many can’t afford to stop working any time soon.
Born between 1965 and 1980, Gen Xers launched their careers at the start of a massive shift in how Americans work. Companies moved from pensions that promise steady income after years of service, to plans such as 401(k)s that place employees’ retirement destiny in their own hands.
Some Gen Xers were hit hard in their prime working years during the 2008 financial crisis. Others are still paying off student debt. Their children are increasingly living at home well into adulthood, while their own aging parents often require care. Few believe they can rely on Social Security to make ends meet later in life.
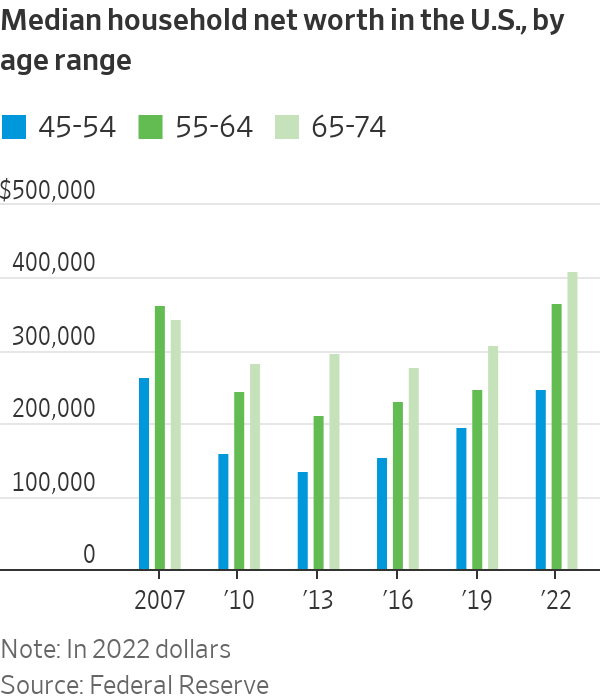
By some measures, Gen Xers are worse off financially than their baby boomer predecessors. The median household net worth of Gen Xers between 45 and 54 years old was about $250,000 in 2022, about 7% lower than that of baby boomers at the same age in 2007, according to inflation-adjusted Federal Reserve data. That was the only age group that experienced a drop in median wealth over the 15-year period.
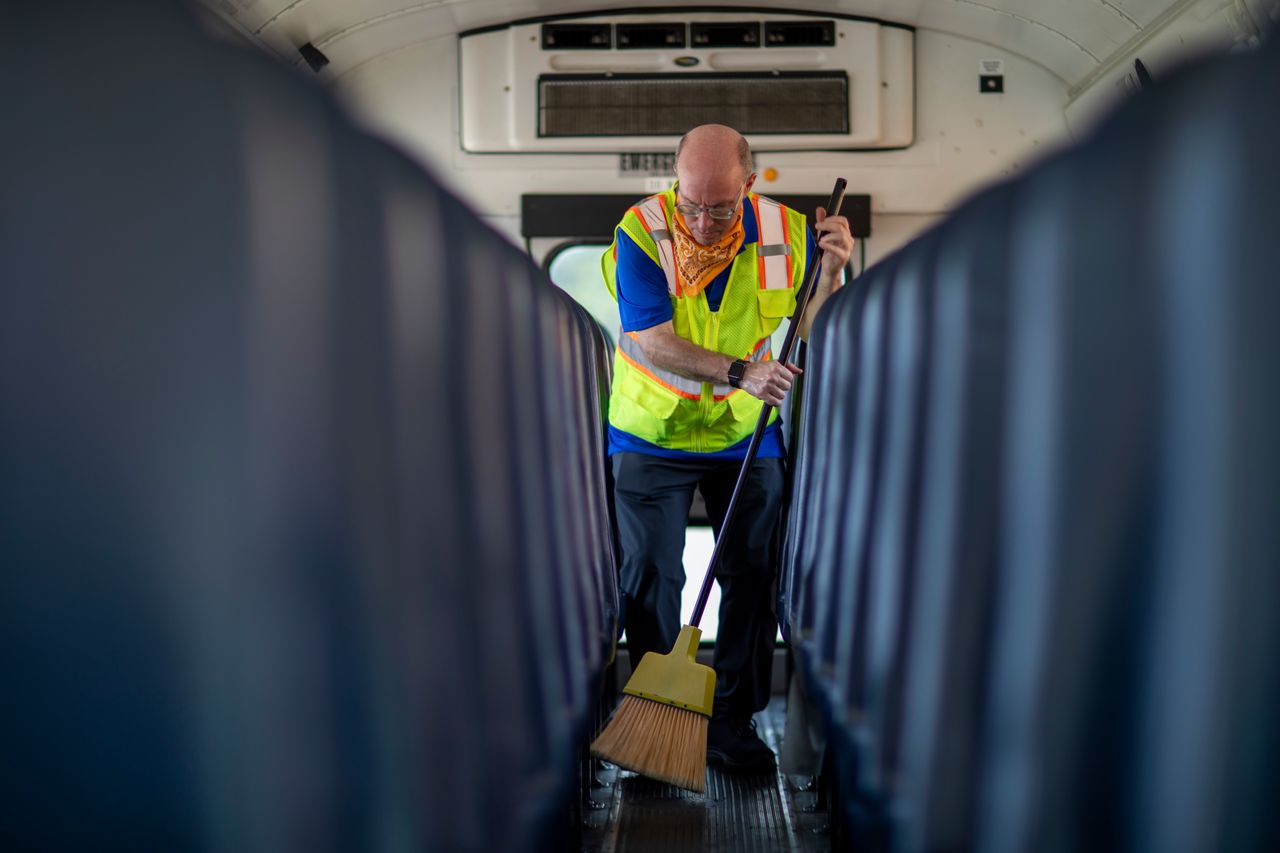
David Bryan, 55, earns about $35,000 a year as a school-bus driver and lives on Tybee Island, Ga. He doesn’t own property and has about $100,000 in retirement savings from his previous jobs as a railroad conductor and a researcher at a college foundation.
It’s a different life than that of his parents, who worked for decades for the sheriff’s department and the post office and received steady pension checks when they retired.
“As long as my body will let me, it’s better I keep working,” said Bryan.
“As long as my body will let me, it’s better I keep working,” said David Bryan.
The roughly 65 million Americans in Gen X are sometimes referred to as the “forgotten generation,” sandwiched between the larger and louder baby boomer and millennial generations. They are also called the “latchkey generation,” often coming home from school as children to an empty house. Goldman Sachs Asset Management in a recent report called Gen X the “‘401(k) experiment’ generation.”
For decades, employers often supported loyal workers in old age through traditional pensions with set payouts for life. The advent of the 401(k) system pushed the responsibility on to the individual—and Gen X was caught squarely in the transition.
“Gen X is the first generation where they were mostly expected to figure out their retirement on their own,” said Jeremy Horpedahl , an economics professor at the University of Central Arkansas and director of the Arkansas Center for Research in Economics.
The early champions of the 401(k) never thought that it would become the dominant way most Americans save for retirement. It is named for a line in the tax code changed in 1978 that gave executives a tax-free way to defer compensation from bonuses or stock options. Human-resources executives and economists jumped on the 401(k) as a way to encourage saving for rank-and-file employees.
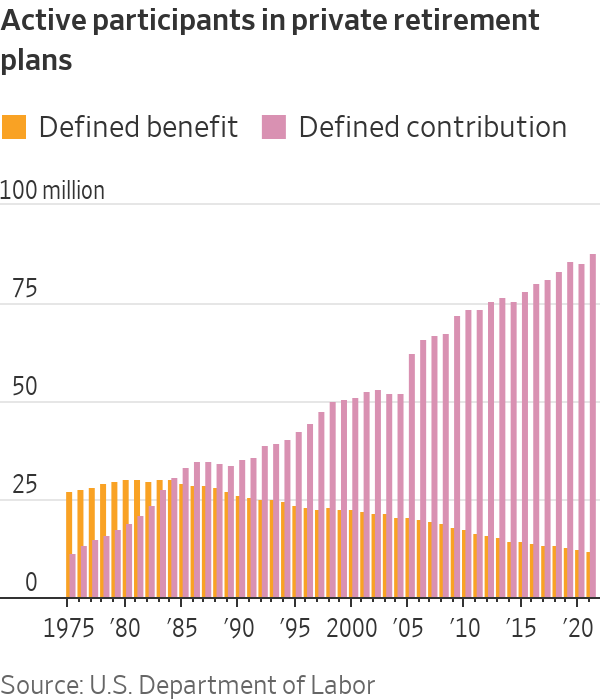
By the mid-1980s, the number of active participants in defined-contribution retirement plans—such as 401(k)s—overtook those in defined-benefit plans—such as traditional pension plans—in the private sector. Now, private pensions are rare.
When Gen Xers entered the workforce, the 401(k) was a new concept. Features such as automatically enrolling employees in a workplace plan and automatically increasing contributions every year didn’t become commonplace until later.
Other common private retirement savings tools were also introduced in the last half-century. The individual retirement account—a tax-deferred investment vehicle—was authorised in 1974, while the Roth IRA—funded with posttax money, but tax-free when withdrawn—was established in 1997.
Gen Xers between 45 and 54 years old had a median account balance of roughly $60,000 in defined-contribution retirement plans at Vanguard Group in 2023, according to the firm. For most Americans, that is well below the target some financial experts recommend of having roughly six times one’s salary saved for retirement by age 50.
John Kotrides, a 54-year-old living near Charlotte, N.C., had contributed to 401(k)s ever since he started his career in banking about three decades ago. But whenever he moved to a different employer, he usually cashed out his 401(k) because there was a more urgent expense, such as a home repair or moving costs.
Keeping the money invested in the stock market didn’t seem worth it after witnessing crashes like the bursting of the dot-com bubble. Retirement seemed far away.
“You no longer have a generation of people whose employer took you from your first job into your retirement,” he said. “When we were offered 401(k)s, I don’t think that was a great deal.”
Kotrides says he doesn’t have much in retirement assets, besides the home he owns, where he lives with his wife and two daughters, who are 12 and 20 years old. After quitting his job as a mortgage lender during the pandemic, he now works as a bartender part-time and earns most of his money making social-media content, mostly nostalgic videos about the 1970s through 1990s. He likes having more time to spend with his family.
“This is basically my retirement plan,” he said. “I truly assume that I’ll continue to work to provide for my family as long as I need to.”
Even those who have benefited from the 401(k) system say it hasn’t been easy.
Scott Zibel, a 56-year-old in Leominster, Mass., started putting money in a 401(k) when he began working at a grocery store at 15. His father encouraged him to contribute. The account grew as he continued working at the store through college and became a manager. In his early 30s, he became an English teacher and expects to receive a pension after retiring.
When the stock market crashed in 2020 at the onset of the Covid pandemic, he and his wife pulled the money in his wife’s 401(k) out of the market and into a money-market fund. Now they have reinvested the money, but put a greater portion of it into bonds than before.
“I’m grateful for the 401(k), but there’s no guarantees as well,” he said, estimating his household retirement savings at a little over $1 million.
Zibel feels prepared for retirement but says he has to live frugally to save. He has driven the same car for 12 years and has avoided pricey expenses such as new carpeting for his 30-year-old home.
“My wife and I have done so much planning for the future with our money, it’s made living in the now difficult,” he said.
For some Gen Xers, the 2008 financial crisis was a hit that took years to recover from.
Around 2007, Darling “Diva” Moore was at the peak of her career as a managing partner at a title company in West Palm Beach, Fla. Then the housing market collapsed and her company went under. She couldn’t make rent on her apartment and had to crash with her significant other at the time, sometimes turning to sleeping on the beach or in the car.
“The Great Recession changed everything for us,” said Moore, who is 57. “After that, I don’t know how many Gen Xers trusted that system.”
Darling “Diva” Moore was at the peak of her career when the housing market collapsed.
After settling in Denver, more than two years went by before she landed a new job. She went back to school, getting an online bachelor’s degree in business management and master’s degree in human relations and organisation development. Now she is self-employed as a career counsellor.
As she is approaching her 60s, Moore is trying to locate money she contributed to various 401(k)s from jobs earlier in her career. Whenever she switched jobs, she didn’t rollover her balance to an IRA or new 401(k), so those accounts are scattered across plan providers. “In the ‘90s, they didn’t make it easy to find out where that money is,” she said.
She is also contending with student debt from a for-profit associates-degree program she completed in her 20s that has swelled to nearly $90,000 from around $27,000 due to interest.
More than a quarter of U.S. households led by Gen Xers between the ages of 45 and 54 had education loans in 2022, compared with about 15% of baby boomers at the same age in 2007, according to Fed data.
Soaring tuition costs, sky-high rents and other inflationary pressures for Gen Z are also Gen X’s problem. Many Gen Xers have forked over tens of thousands of dollars for their children to attend college. Young people are also increasingly living with parents, or relying on them for financial support, well into adulthood .
Pamela Likos’s 21-year-old son lives at home with her in the suburbs of Madison, Wis., while another son and daughter are at college.
“My kids are still definitely not grown and flown,” Likos said.
Some Gen Xers are simultaneously caring for aging parents, who are living longer than previous generations.
Likos isn’t in that situation yet, but her stepmother, who has Alzheimer’s, and her father are in their 80s.
“I need my parents to hang on healthwise for another five to 10 years because we are not ready to help financially, really,” she said.
Likos, who is 54, was the first person in her family to go to college, but didn’t work for about two decades after she got married and became a stay-at-home mom. When she got divorced about seven years ago, she found herself with no savings of her own and no resume to apply for jobs. She got a license to work as an esthetician for a few years and now is remarried. From her divorce, Likos received about half of her ex-husband’s 401(k), which comprises most of her plan for retirement.
The youngest members of Gen X are in their mid-40s, offering more time to boost savings ahead of retirement. Tyler Bond, the research director at the National Institute on Retirement Security, wonders if there will be diverging retirement experiences between the older and younger ends of the cohort.
“The older Gen Xers simply may not have time,” he said.
Avery Nesbitt, a 44-year-old operations manager in the Atlanta area, isn’t waiting for retirement to go on nice vacations or buy a new car because he wants to enjoy them now—and he doesn’t expect to be able to save up a cushy nest egg for later in life. If the Covid pandemic taught him anything, it was that anything can happen.
He and his wife have contributed modestly to employer-sponsored retirement accounts but didn’t feel like they could afford to save more. They own a home, where they live with their two children. That makes up the bulk of their wealth. He said he has put more money into life-insurance policies than in retirement accounts.
“I fully expect to work until I die,” Nesbitt said. “It is what it is.”
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
By Laura Saunders
Fri, Oct 9, 2026 4min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.


 7 min
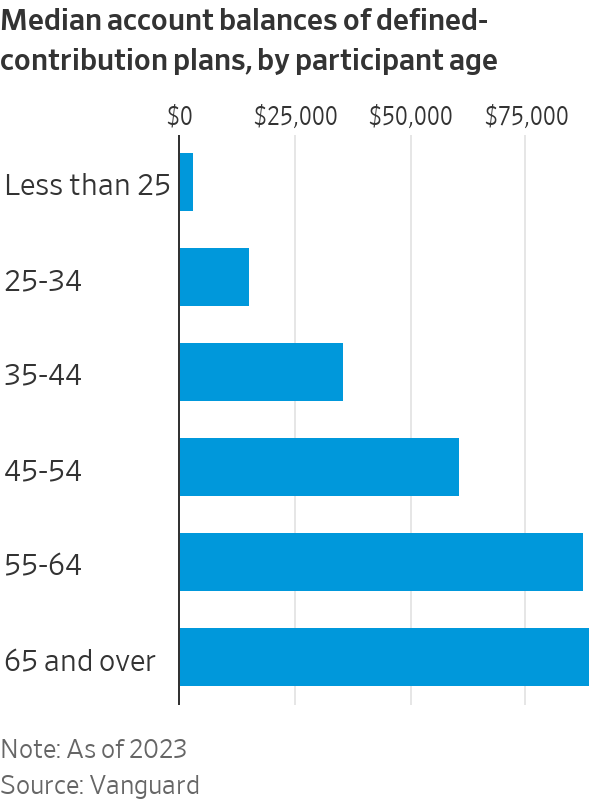
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



