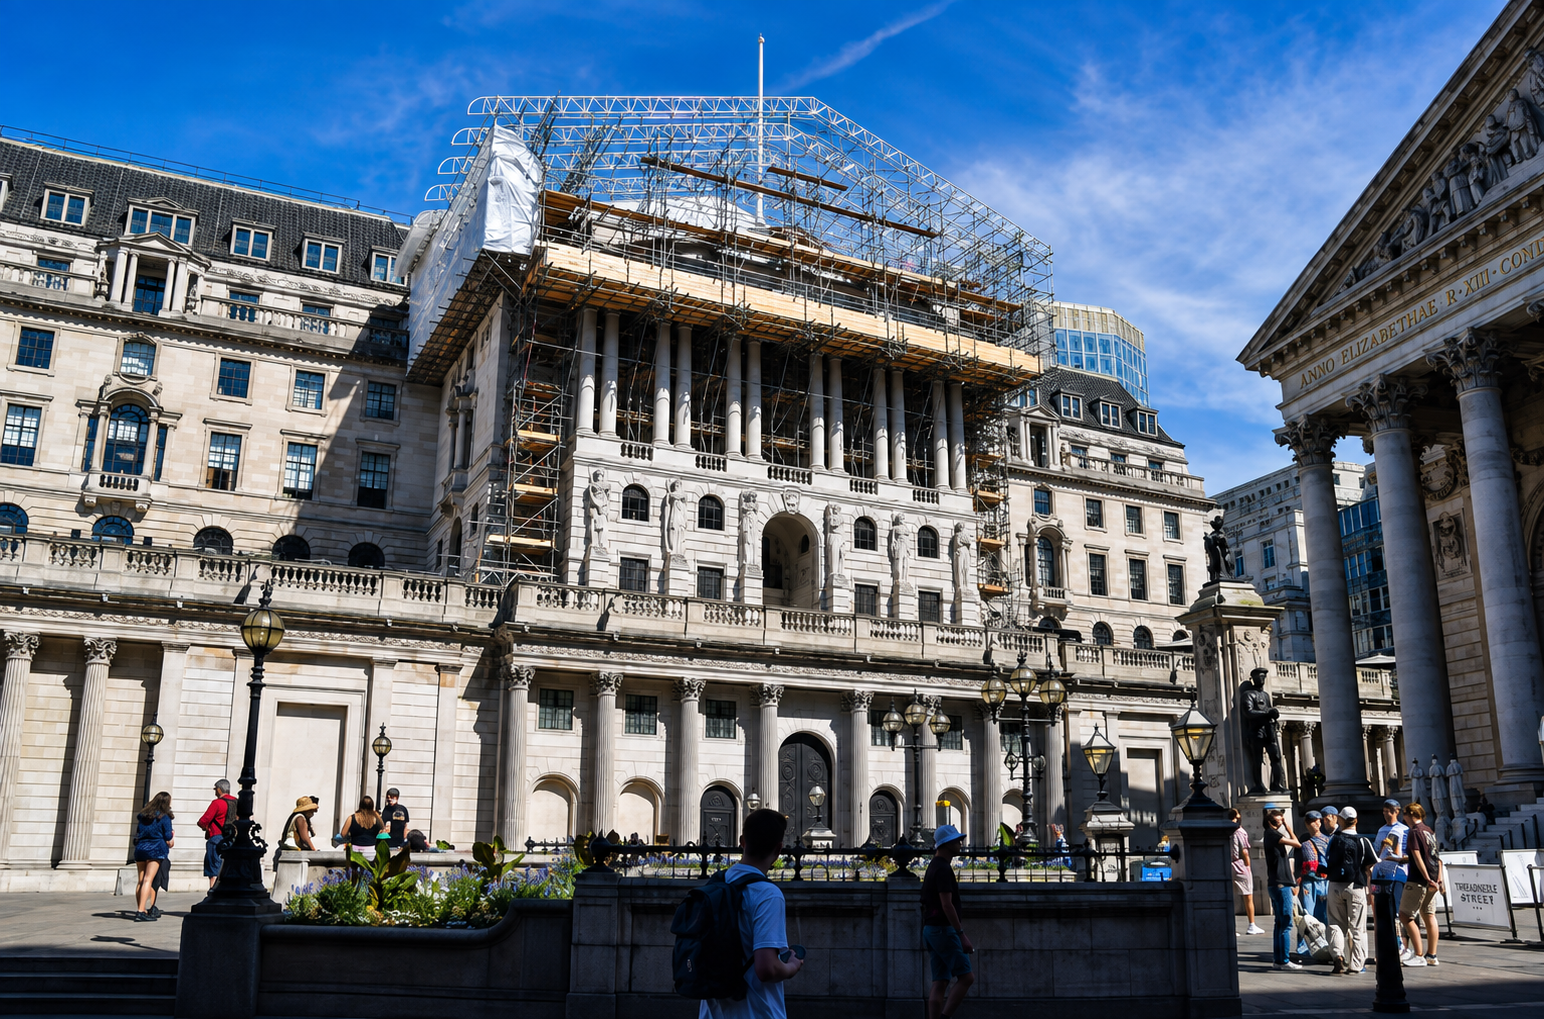
Central Banks Are Stuck in a Rinse-and-Repeat Cycle of Crises - Kanebridge News
Share Button

Central Banks Are Stuck in a Rinse-and-Repeat Cycle of Crises

Central banks’ efforts to keep markets stable may be creating unintended risks. Emergency lending and market backstops have encouraged highly leveraged government bond trades, potentially lowering borrowing costs while increasing financial vulnerabilities that could require further intervention during the next crisis.

By James Mackintosh
Mon, Aug 17, 2026 5:21pmGrey Clock 4 min

Central banks may be accidentally subsidizing government borrowing through their efforts to prevent a repeat of past market blowups, and policymakers are starting to worry that anticrisis lending facilities could even be interfering with their own monetary policy.

The source of the problem is the switch from central banks being the lender of last resort to, in 2008 and 2020, also being market makers of last resort, ensuring corporate—and government—debt markets keep functioning. During a crisis, support is often essential to prevent a downward spiral that destroys the financial system.

But backstopping markets removes a key risk and encourages more borrowing—especially for the hedge funds that now own trillions of dollars of U.S. Treasurys.

“Ironically, vulnerability is created by mechanisms that were introduced to reduce vulnerability,” said Huw Pill, the Bank of England’s chief economist, one of those growing concerned, in an interview. “So, it’s a bit like a whack-a-mole kind of story.”

Offering either an explicit or implied guarantee that government-funding markets will remain open and liquid means hedge funds have less risk of being unable to finance highly leveraged trades. This is particularly true for the overnight repurchase, or repo, market, where borrowers pledge bonds for cash. The result has been a huge expansion of two popular government bond trades, arbitraging Treasurys or British gilts against bond futures or swaps.

The scale is extraordinary: The Dallas Fed estimates hedge funds ended last year with $2.4 trillion of Treasurys, up from $600 billion a decade earlier. Because the profits on each trade are tiny, hedge funds have to leverage as much as 100 times to get worthwhile returns, creating new risks.

This might sound abstruse. But in 2020, it was the Treasury basis trade blowing up that forced the Fed to intervene. In 2025, signs of trouble in the swap trade pushed President Trump to retreat from his tariff plan.

Pill worries that the reassurance central-bank policy provides bleeds into monetary policy by boosting borrowing. This, in turn, keeps government-debt yields lower than they otherwise would be.

“There’s lots of gilts to be bought,” he says. “How do you support that buying of gilts? You make it attractive. How do you make it attractive? Well, there are some imperfections in the market. So those imperfections create profit opportunities, but they’re not very big. So how do you make them more meaningful? You allow leverage to build up.”

“That’s good for the government because it gets to sell the gilts at a lower [yield] than it otherwise would. It’s good for the financial sector because they’re able to extract these rents effectively. And it’s good for the central bank because the market seems to be liquid and functioning. But all of those things are true until they’re not true.”

When it goes wrong, the more leverage, the worse the problem. And the worse the problem, the more likely it becomes that central banks have to create yet more special tools to address it. That then spurs the next buildup of leverage.

Pill thinks more effort is needed to come up with a modern version of the Bagehot Doctrine. Walter Bagehot, the 19th-century editor of the Economist magazine, summed up the role of the central bank as being to lend to banks freely, against good collateral, at a penalty rate. Access to instant cash helps banks withstand runs. The fact the central bank is offering a backstop should make the run less likely, and shareholders are penalized, through the penalty rate, if it is used.

Illustration of economist and journalist Walter Bagehot in profile.
English economist and journalist Walter Bagehot. Hulton Archive/Getty Images

Tools for saving markets from drying up are more haphazard. In 2020 the Fed, BOE and others just bought lots of government debt to inject liquidity into markets. That worked because, even though quantitative easing is also a monetary policy tool, they also wanted easier money.

Unfortunately, that created what Pill described as a tinderbox, ignited by the energy crisis after Russia invaded Ukraine. The excess money creation from left over from emergency QE then fanned the flames of inflation. This made it much harder to calibrate monetary policy when central banks decided to tighten (although policymakers were also, in my view, far too slow to recognize inflation).

Pill points to the “temporary, targeted” BOE buying of gilts amid the forced selling by leveraged pension funds after Britain’s botched tax-cut plan in September 2022 as a successful model. At a time when the BOE was trying to tighten monetary policy, it intervened in a way that stopped the pension fund selling spiral and stabilized gilts. Yet the central bank maintained tight monetary policy.

Bagehot would recognize the goal: Reduce the encouragement to take risk, known as moral hazard, that offering guarantees in advance creates, but retain the ability to mount a rescue in a crisis.

Unfortunately, much of central banking is going backward on this. Moral hazard is increasing, even for banks. In the 2023 bank bailout, the Fed accepted less-than-full collateral, recognizing Treasury bonds at face value rather than their (much lower) market value.

The emergency rescue facility then became a funding facility that even healthy banks chose to tap—in effect easing monetary policy by the back door and prompting the Fed to tighten the terms before it ended. Something similar could be under way with Japan’s plans to use an emergency Fed loan facility to raise cash to prop up the yen without having to sell its hoard of Treasurys.

I don’t know how to break the cycle of crises needing rescues that lead to more leverage and new crises. And I’m concerned we’re firmly into the added-leverage phase of the latest cycle.

At least central bankers are still thinking about it, even if they don’t, so far, have good answers.


MOST POPULAR

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.

Related Stories
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Money
Wall Street Is Counting on Nvidia to Keep the AI Party Going
By David Uberti and Krystal Hur 24/08/2026

Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.

By Hannah Erin Lang
Tue, Sep 8, 2026 3 min

The stock market had a decent summer. Investors are bracing for a bumpier fall.

In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.

Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.

“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”

Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.

Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.

Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.

“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.

The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.

On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.

“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.

That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.

Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.

Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.

Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.

With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.

Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.

But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.

“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”