Does Warren Buffett Know Something That We Don’t?
Berkshire Hathaway is hoarding cash in a pattern seen before the financial crisis, but it has a new reason this time
By
SPENCER JAKAB
Tue, Nov 12, 2024 9:54am 4 min
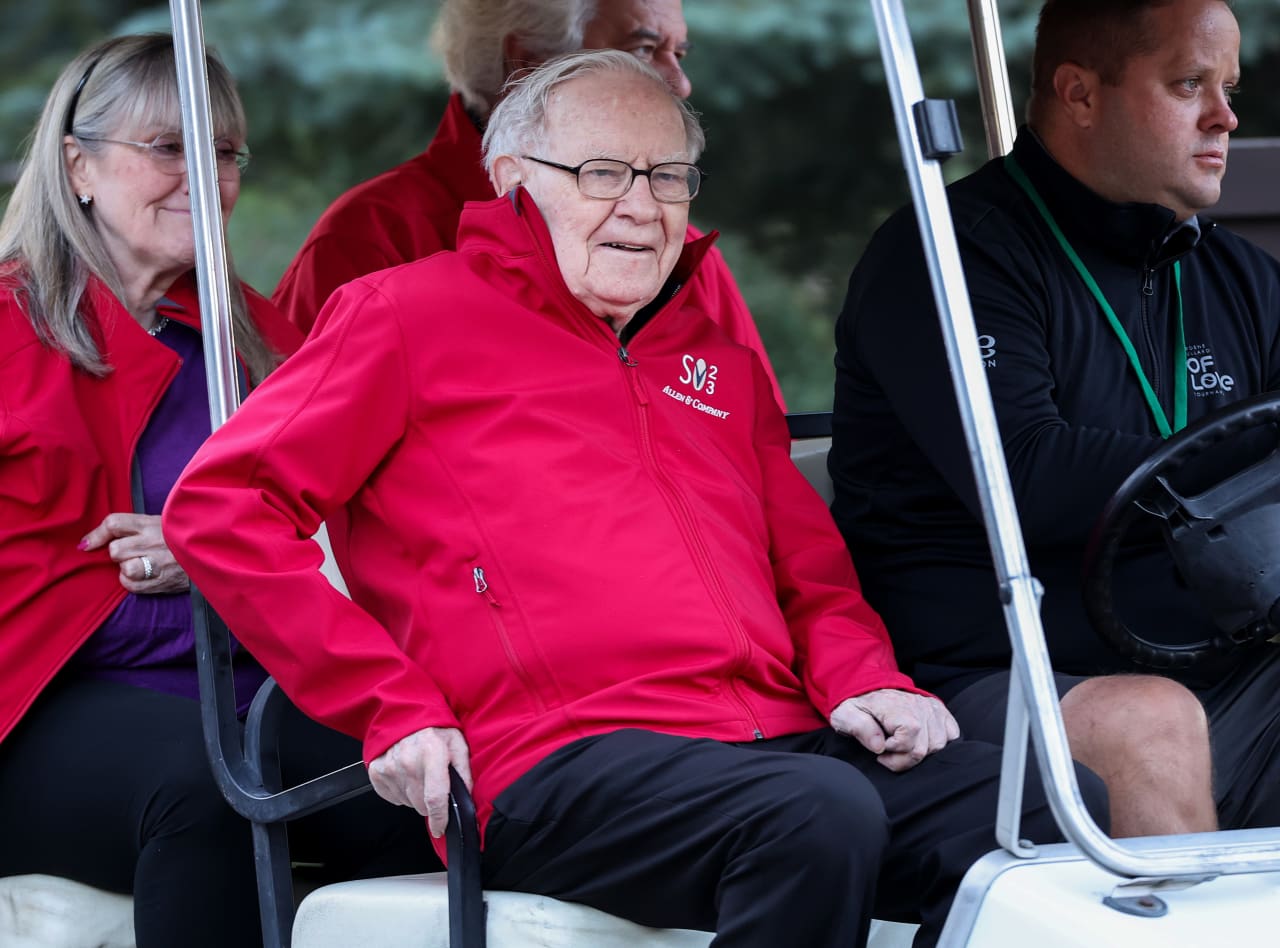
Warren Buffett, chairman and CEO of Berkshire Hathaway.
Getty Images
When the world’s most-followed investor doesn’t feel comfortable investing, should the rest of us be worried?
Warren Buffett , who has quipped that his favourite holding period for a stock is “forever,” continues to have substantial money at work in American companies. But he has never taken this much off the table either—a whopping $325 billion in cash and equivalents, mostly in the form of Treasury bills.
To appreciate the immensity of that hoard, consider that it would allow Berkshire to write a check, with change left over, for all but the 25 or so most-valuable listed U.S. corporations—iconic ones such as Walt Disney, Goldman Sachs , Pfizer, General Electric or AT&T. In addition to letting the dividends and interest pile up on its balance sheet, the conglomerate has aggressively sold down two of its largest shareholdings, Apple and Bank of America, in the past several months. And, for the first time in six years, it has stopped buying more of the stock it knows best— Berkshire Hathaway.
Does that mean mere investing mortals should be cautious about the market? Maybe, but it tells us even more about Berkshire.
Buffett and his late business partner Charlie Munger didn’t outperform the stock market 140-fold by being market-timers. Probably Munger’s most famous quote is his first rule of compounding: “Never interrupt it unnecessarily.” Investors who follow Berkshire closely and hope for a bit of its magic to rub off on their portfolios pay very close attention to what it is buying and selling, but much less to when.

Yet the seemingly always optimistic and patient Buffett has turned cautious before, famously shutting his extremely successful partnership in 1969 when he said markets were too frothy and also building up substantial cash in the years leading up to the global financial crisis—money he deployed opportunistically.
“He’s cognisant of the fact that markets gyrate and go to extremes,” says Adam J. Mead, a New Hampshire money manager and Buffetologist who is the author of “The Complete Financial History of Berkshire Hathaway.”
Stock values being stretched doesn’t mean they are on the precipice of a crash or even a bear market. Instead, zoom out and look at what today’s valuations say about returns over the next several years, which will include both good and bad periods. Goldman Sachs strategist David Kostin predicted recently that the S&P 500’s return over the next decade would average just 3% a year—less than a third of the postwar pace.
Kostin’s report went over like a record scratch at a time of high investor optimism, but it is consistent with other forecasts. Giant asset manager Vanguard recently predicted an annual return range of 3% to 5% for large U.S. stocks and just 0.1% to 2.1% for growth stocks over a decade. And Prof. Robert Shiller ’s cyclically adjusted price-to-earnings ratio is consistent with an average return of about 0.5% a year after inflation —similar to Kostin’s projection.
Then there is the even simpler “Buffett Indicator,” which the Oracle of Omaha once called “probably the best single measure of where valuations stand at any given moment.” There are variants on the theme, but it is basically a ratio of all listed stocks to the size of the U.S. economy. Taking the Wilshire 5000 Index as a proxy it is now around 200%, which would leave it more stretched than at the peak of the tech bubble.
With T-bills now yielding more than the prospective return on stocks, it might seem that Buffett has taken as many chips off of the table as possible since there is no upside in risky stocks. But he is on record saying that he would love to spend it.
“What we’d really like to do is buy great businesses,” he said at Berkshire’s 2023 annual meeting. “If we could buy a company for $50 billion or $75 billion, $100 billion, we could do it.”
With Berkshire now worth $1 trillion, it would take a deal of that size to move the needle. Mead explains that a transaction matching acquisitions like 2010’s Burlington Northern Santa Fe deal or the 1998 acquisition of insurer General Re would be worth $100 billion scaled to today’s balance sheet.
Could it also mean that Buffett sees value in keeping dry powder ahead of the next crisis or general froth in the market? Yes, but he isn’t saying, and individual investors also have more options than he does. First of all, we don’t have to pay a 20% or more premium to the market price to invest in a business like Berkshire would in a takeover. We also can sail in much shallower waters and smaller ponds. For example, Vanguard’s 10-year projections range from 7% to 9% a year for non-U.S. developed market stocks and 5% to 7% for U.S. small capitalisation stocks. Other than a very profitable bet on Japanese trading companies in recent years, though, Buffett has kept his money mostly stateside and likely will continue to do so.
Changes at Berkshire are inevitable, though—and not just because the 94-year-old is nearing the end of his remarkable career. Buffett hasn’t hesitated to return cash to shareholders, almost exclusively through stock buybacks, yet he clearly deems even his own stock too pricey for that.
Berkshire also has reached a size at which it can’t replicate its long-run record of deploying its profits and handily beating the market. It is going to have to hand money back somehow—probably through a dividend, reckons Mead. Eventually it becomes necessary to interrupt compounding.


 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



