KERKDRIEL, the Netherlands—For much of the spring and summer, Jeroen van Diesen got paid for using electricity.
Sometimes his neighbours came over to power up too, generating even more cash.
Van Diesen’s situation reflects the strange, new dynamics of electricity that could soon become the norm in many parts of the world: A big increase in wind and solar power has pushed wholesale prices to zero or below for many hours of the year, spurring a sea change in the way people use power—based on whether the sun is shining or the wind is blowing.
Most people pay a fixed price for each kilowatt-hour of electricity they consume throughout the day. The price is set by their power company and only changes at infrequent intervals—once a week, a month or even only once a year.
Van Diesen, a software salesman, recently signed up to receive electricity from two providers that charge him the hourly price on the Dutch wholesale power market, rather than a fixed price that resets monthly or annually. When the price of electricity falls low enough, smart meters in his house begin charging his two electric cars.
Wholesale prices swing wildly each hour of the day, and even more so as a larger share of electricity flows from wind and solar installations. Because the generation costs of wind or solar farms are negligible, market prices will be near zero when there is enough renewable power to cover most of a region’s electricity demand.
Electricity market dynamics get weirder when renewable-energy producers don’t have an incentive to stop feeding power into the grid, usually because of government subsidies. Then grids can be flooded with excess power, pushing prices into negative territory.
Van Diesen said he’s made 30 euros, equivalent to around $34, over the past five months charging his car, enough to cover the service fee from his power supplier, a Norwegian company called Tibber.
“I’m charging the car for free,” said van Diesen, who is part of a group of clean-energy enthusiasts in the Netherlands who call themselves green nerds. “To me it’s also like a hobby and a game—how far can I go?”
Doing laundry in the evening? The electricity could be free a few hours later when demand dies down and the wind picks up. Likewise, in regions with lots of solar power, charging an electric vehicle in the morning is usually far more expensive than powering up under the midday sun—or whenever the price is right.
In the U.S., most states don’t currently allow such real-time pricing, but many think that will change. Already, in some of the world’s biggest economies from Western Europe to California, the occurrence of zero and negative wholesale power prices is growing fast.
Negative prices
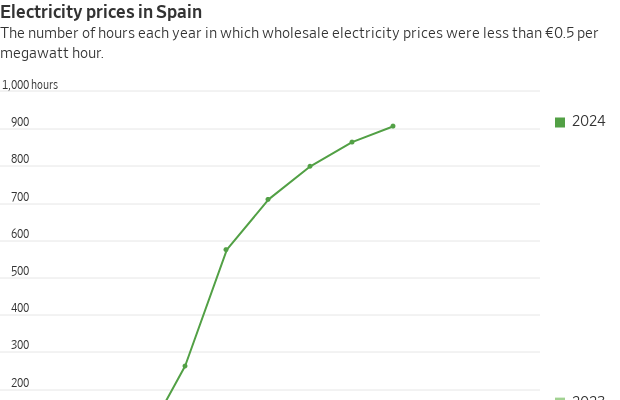
Wholesale prices across continental Europe have fallen to zero or below in 6% of all hours this year, up sharply from 2.2% in 2023 and just 0.3% in 2022, according to data collected by Entso-E, the group of European transmission system operators. In markets with lots of renewable capacity, this year’s figure was higher: 8% in the Netherlands, 11% in Finland and 12% in Spain. Analysts expect those numbers will grow as more solar panels and wind turbines are installed.
The changes sweeping Europe’s electricity markets, which were accelerated by the energy crisis brought on by the war in Ukraine, show what could happen in the U.S. in a few years when renewable capacity reaches a similar scale. In 2023, 44% of EU electricity was generated by renewables, compared with 21% in the U.S.
In some U.S. markets—sunny California, the wind-swept Great Plains, and Texas—zero and negative prices are already common. The wholesale price in Southern California was negative nearly 20% of all hours this year because of the region’s boom in solar-panel installations. That compares to around 5% last year, according to data collected by the U.S. Energy Information Administration.
U.S. regulators have been cautious about allowing households and companies to sign up for electricity plans that charge them wholesale prices, fearing consumers could be hit with big bills if prices jump. Texas consumers who signed such contracts were walloped with huge bills in 2021 when a rare winter storm sent prices soaring.
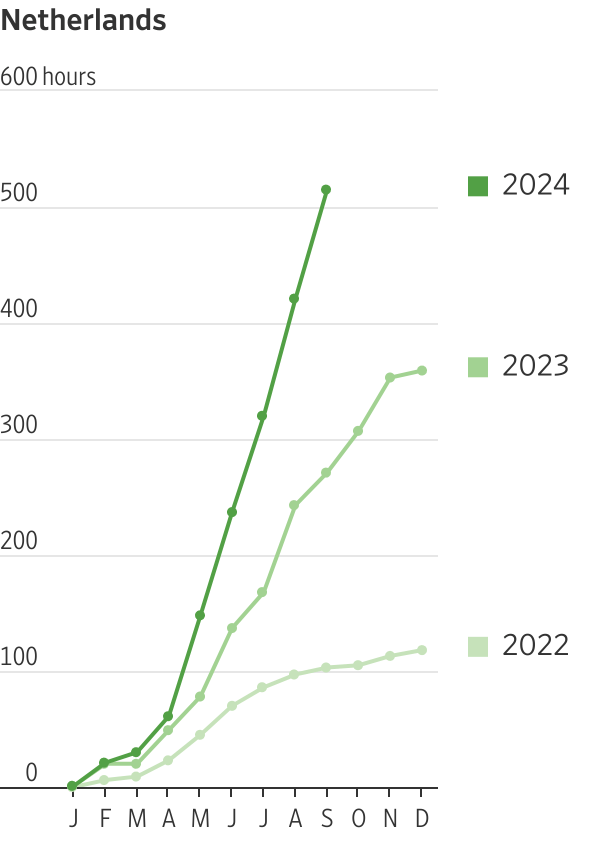

States’ reluctance, however, may now be waning as policymakers increasingly see real-time pricing as a way to lower peak demand, reduce the need for costly infrastructure and integrate more renewables into the grid.
California regulators this year ordered the state’s utilities to expand dynamic price pilot programs that have only been available for a select group of customers.
Your overall power bill still won’t be zero in a clean-energy future. Generation costs comprised around 60% of customer bills on average in the U.S. in 2023. Transmission and distribution costs account for most of the rest—and are expected to grow sharply in the coming decade to reinforce the grid for electric heating, electric transport and data centers.
Negative prices could also be reined in over the next few years as governments from Europe to California pare back renewable-energy subsidies. Governments are particularly focused on trimming subsidies for solar power, which is driving negative prices in a number of markets.
Green nerds
In Europe, energy-hungry manufacturers are shifting their operating strategies to maximise energy consumption when prices are close to zero or negative, while throttling back when prices are high.
Linde, a U.K.-based engineering company, is building a new generation of industrial gas plants that can be quickly ramped up and down depending on the wholesale price of power.
When solar and wind power drive prices down, Linde’s plants fire up and send the output to large tanks. When electricity prices shoot up again, the plants can ramp back down and supply customers out of the gases stored in the tanks.
“The tank functions like a virtual battery,” said Klaus Ohlig, a research and development executive at Linde Engineering.
Trimet, an aluminium producer that is one of Germany’s single-largest power consumers, is overhauling its smelters to vary their power consumption depending on the availability of renewable energy on the grid.
A new European Union law requires dynamic-price power contracts be made available to consumers across the 27-nation bloc. Tibber, a power retailer based in Norway that charges its customers the wholesale hourly price, has signed up more than one million households across the Nordic countries, Germany and the Netherlands.
Edgeir Aksnes, Tibber’s co-founder and chief executive, says he doesn’t expect customers to constantly track the hourly price before deciding when to charge their car or run appliances.
“We can automate all of this for you. You don’t have to think about it,” he said.
Some enthusiasts, however, like to get into the weeds.
Wouter van Embden, a 49-year-old Dutch entrepreneur and one of the country’s so-called green nerds, switched to Tibber earlier this year. On a recent summer Sunday, the battery in his home began charging as solar power flooded the Dutch grid and the wholesale power price fell to zero. He also charged his two electric cars and programmed his heat pump to make the water in the house tank extra hot.
Toward the evening, as prices rose with the drop-off in solar, van Embden’s battery—which he and his son built at home—would power his home as well as feed into the Dutch grid.
“I have to be honest, when I started building the battery I had so many outages. There was a lot of testing to do,” he said. “But now it’s working pretty stable.”


 5 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



