
Fed Cuts Rates Again, This Time by a Quarter Point
Powell says he has no intention of leaving Fed before his term expires

By NICK TIMIRAOS
Fri, Nov 8, 2024 9:31am 4 min
4 min


Powell says he has no intention of leaving Fed before his term expires
4 min
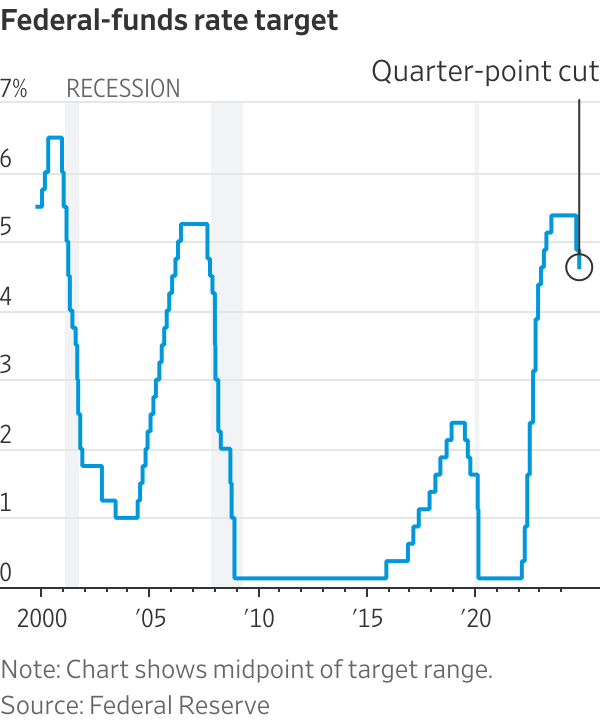
US: The Federal Reserve approved a quarter-point interest-rate cut Thursday, the latest step to prevent large rate increases of the prior 2½ years from weakening the labour market as inflation eases.
The decision, coming the same week as the election of Donald Trump to a second presidential term, followed an initial cut of a half-point in September and will bring the benchmark federal-funds rate to a range between 4.5% and 4.75%. All 12 Fed voters backed the cut.
Officials have said those moves are warranted because they are more confident that inflation will return to the central bank’s target and because they believe rates are still high enough, even with the latest cuts, to dampen economic activity.
The move was expected. Stocks and Treasury yields were steady after the announcement.
“We are committed to maintaining our economy’s strength,” Fed Chair Jerome Powell said at a news conference. He said officials are confident that with an “appropriate recalibration of our policy stance,” inflation can continue heading lower with a solid economy.
Trump’s election victory this week has the potential to reshape the economic outlook, with presumed GOP majorities on both sides of Capitol Hill enabling a broad shift on taxes, spending, immigration and trade. Economists are divided over whether the mix of policies will boost or weaken growth and drive up prices.
The shift in the outlook, in turn, has fuelled questions on Wall Street over whether the Fed will alter its earlier expectation that rates could be steadily dialled lower over the coming year or two.
Powell said it was too soon to say how the next administration’s policies would reshape the economic outlook.
“We don’t guess, we don’t speculate, we don’t assume” what policies will get put into place, Powell said. “In the near term, the election will have no effects on our policy decisions.”
Powell also said he had no intention of leaving the Fed before his four-year term as chair expires in May 2026. “Not permitted under the law,” Powell said when asked if he believed the president could remove him or other Fed personnel from their positions before their term expires.
Since the Fed cut rates in September, longer-dated bond yields have climbed notably, meaning the cost to borrow for a mortgage or car loan has gone up. Yields have increased in large part because better economic data has led investors to reduce their worries about a recession, which could have triggered larger rate cuts.
But some analysts think the bond-market selloff may also reflect concerns by some investors about higher deficits or inflation in a second Trump administration.
Either way, the market has generated an unusual result: Borrowing costs rose after the Fed cut rates. The average 30-year mortgage rate has jumped since mid-September, to 6.8% this week from 6.1%, according to Freddie Mac.
Over a similar time frame, investors in interest-rate futures markets have steadily reduced their expectations over how much the Fed will cut rates over the next year or so. They now see the Fed cutting rates to around 3.6% by 2026, up from an estimated trough of 2.8% in September, according to Citi.
Officials are trying to bring rates back to a more “normal” or “neutral” setting that neither spurs nor slows growth. But they don’t know what constitutes a normal rate. Policies that boost economic activity or prices could also lead officials to conclude that they should maintain a moderately restrictive rate stance. That means they would hold rates somewhat higher than a normal or neutral level.
Before the 2008-09 financial crisis, many thought a neutral rate might be around 4%, but after the crisis and an extremely sluggish recovery, economists and Fed officials concluded the neutral rate might be closer to 2%.
Interest-rate projections that officials submitted in September show most of them expected that if the economy expanded solidly with inflation continuing to cool , they could cut rates to around 3.5% next year.
Inflation based on the Fed’s preferred index was 2.1% in September, from a year earlier. A separate measure of so-called core inflation that strips out volatile food and energy prices was 2.7%. The Fed targets 2% inflation over time.
Because officials don’t have much conviction over where the neutral rate sits, they are likely to be guided by how the economy performs in the months ahead. If inflation keeps slowing and the demand for workers looks soft, officials could conclude it makes sense to continue cutting rates along the path they envisioned in September.
“We’re going to move carefully as this goes on so we can increase the chances that we get it right,” Powell said. “We’re trying to steer between the risk of moving too quicky…or moving too slowly. We’re trying to be on a middle path.”
If inflation progress stalls or ebullient financial markets raise concerns that inflation might get stuck above their target, officials might face more reservations around continuing to cut rates at a steady, meeting-after-meeting clip.
The most immediate focus is whether the Fed will cut again at its upcoming meeting in December. In September, 19 participants were about evenly divided over whether to cut rates one or two more times this year. Nine of them penciled in no more than one cut in either November or December, while 10 penciled in two cuts.
“There’s a lot to learn between now and the December meeting,” said Diane Swonk, chief U.S. economist at KPMG. “They can’t leave the door wide open, but they can’t close the door either.”
Powell said Thursday it was too soon to rule anything “out or in” at that meeting. Slowing down the pace of rate cuts is “something we’re just beginning to think about,” he said. “We’re on a path to a more neutral stance. That has not changed at all since September. We’re just going to have to see where the data lead us.”
Even before the election result, recent data suggested that cutting again would be a finely balanced decision because inflation looks like it might end the year slightly above officials’ projection, while the unemployment rate has edged lower recently, said Matthew Luzzetti, chief U.S. economist at Deutsche Bank.
The election result— which sent stock markets to new highs while raising the prospect of stronger growth, higher inflation and better labour-market outcomes—boosted the odds that the Fed forgoes a cut next month, he said.
“Those could present a strong case from a risk-management perspective to potentially skip that meeting,” said Luzzetti.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
