
How Can Companies Push Back on China? Be Like Australia.

By Isaac Stone Fish
Thu, Dec 3, 2020 1:39am 3 min
3 min

 3 min
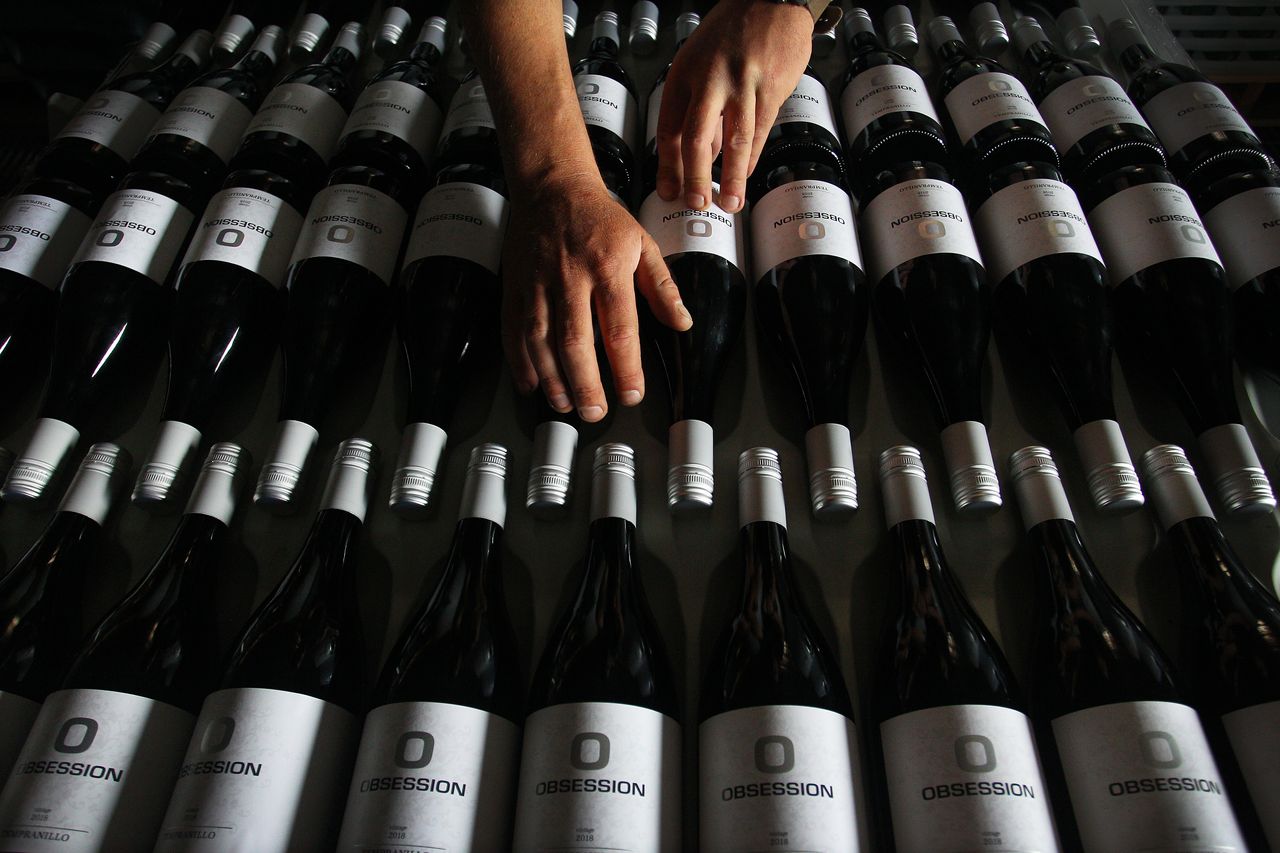
Drinking together has always been a way to show solidarity. And that’s what Australian allies are doing, in response to Beijing’s newest trade sanctions on the country’s wine industry. Taiwanese legislators posted photographs of themselves with bottles of Australian wine, while a Swedish politician urged people to stand up to Beijing by “drinking a bottle or two.” Even the U.S. National Security Council joined in with an unusually punchy tweet. The bandwagoning may be awkward at times, but it contains an important lesson: The best way to push back against Beijing’s coercion is through a unified response.
For more than six months, Beijing has been waging a trade war against Australia. The latest salvo—up to 212% tariffs on Australian wine, announced on Nov. 27—threatens to decimate the country’s roughly $3 billion wine industry, and adds to a crowded list of tariffed items. The total amount targeted is now roughly $20 billion. Beijing has blamed Australia for a “series of wrong moves,” and announced 14 political disputes it expects Canberra to rectify in order to improve the relationship.
This is not a new tactic for Beijing. Since the 1990s, Beijing has made public examples of foreign institutions, people, and countries, and used that to scare others into acquiescence. After the Houston Rockets’ then general manager Daryl Morey tweeted about Hong Kong in October 2019, for example, Beijing froze the NBA out of China for a year, leading to hundreds of millions of dollars of lost revenue for the organisation. Reached for comment, an NBA spokesperson forwarded NBA Commissioner Adam Silver’s recent comments, where he said that the NBA’s response to the China scandal was, “We support freedom of expression.”
The NBA incident wasn’t the first. After the independent Nobel committee’s 2010 decision to award the Nobel Peace Prize to the Chinese dissident Liu Xiaobo, Beijing drastically curtailed Norway’s salmon exports to China. Companies like Marriott and the South Korean conglomerate Lotte have been targeted, too.
The strategy Beijing is using against Australia—coordinated complaints, economic punishment for political crimes, and an insistence that the other party is solely at fault—is remarkably similar to what Beijing did to the NBA. What’s new is Australia’s response.
The crucial difference lies in Australia’s smart insistence in not facing China alone. Since the beginning of its trade war, Canberra has strengthened old alliances and built new ones. It has agreed to develop a supply chain resilience program with Japan and India, signed a free trade deal with Indonesia, and benefitted from political support of countries like France, New Zealand, and especially the United States. Australia has urged its allies to understand that the more it yields to an attack by Beijing, the worse it is for its partners. This is especially true with the countries in the so-called Five Eyes intelligence sharing partnership, whose other members are Canada, the United Kingdom, New Zealand, and the United States.
The other major difference is Canberra’s willingness to publicly criticise Beijing. The NBA’s responses were almost uniformly milquetoast, including from normally outspoken stars, like LeBron James, who called Morey “misinformed.” Compare that to criticism of Beijing across the Australian political spectrum: Prime Minister Scott Morrison has posted criticisms on Chinese social media, while Penny Wong, the leader of the opposition in the senate, called one of Beijing’s recent actions “gratuitous” and “inflammatory.”
Corporations can learn from Australia. When faced with Beijing’s ire, businesses need to partner more closely with their home governments and their global competitors. Organisations like the U.S.-China Business Council already serve as platforms for companies to coordinate and share grievances. But they do so mostly privately, and with an overwhelming desire to maintain positive relationships with Beijing. They argue that staying quiet in public helps companies maintain leverage and keep their China presence. “China can’t make good on its promises to further open its economy if there is no longer anyone there—or that could be there—to open to,” a spokesperson for the council said.
Chambers of commerce need to understand that publicly and privately pushing back against Beijing with American and other home government support when one of their members is targeted is better in the long run for all member companies. In certain cases, Congress should consider an antitrust waiver for firms that are collaborating to challenge Beijing.
Will publicly and multilaterally pushing back against Beijing help Canberra succeed in reducing tensions without showing weakness? It’s difficult to say—in large part because Beijing’s responses to these situations are uneven. Sometimes Beijing holds the grudge for years, and sometimes it calms down in weeks, or even days. The capriciousness of the response is a sign of strength, not weakness—it pushes the adversary to overcompensate, to seek to right the relationship. But standing strong and not yielding is Australia’s best hope for a healthy future relationship with both China and the United States. And Australia’s allies are stepping up. In late November, the Trump administration announced plans to work with Australia to counter Beijing’s economic hostage-taking. “The West needs to create a system of absorbing collectively the economic punishment from China’s coercive diplomacy and offset the cost,” a senior administration official told the Wall Street Journal.
Corporations targeted by Beijing can effectively engage their allies, both in governments, and in the business world, but most don’t. As tensions between the United States and China continue to worsen, it’s imperative that they build support from their home governments—and that they speak out when Beijing targets them.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
