
I Said Yes to Every Upgrade in Las Vegas. Here’s What It Cost.

By DAWN GILBERTSON
Thu, Feb 8, 2024 8:58am 4 min
4 min

 4 min
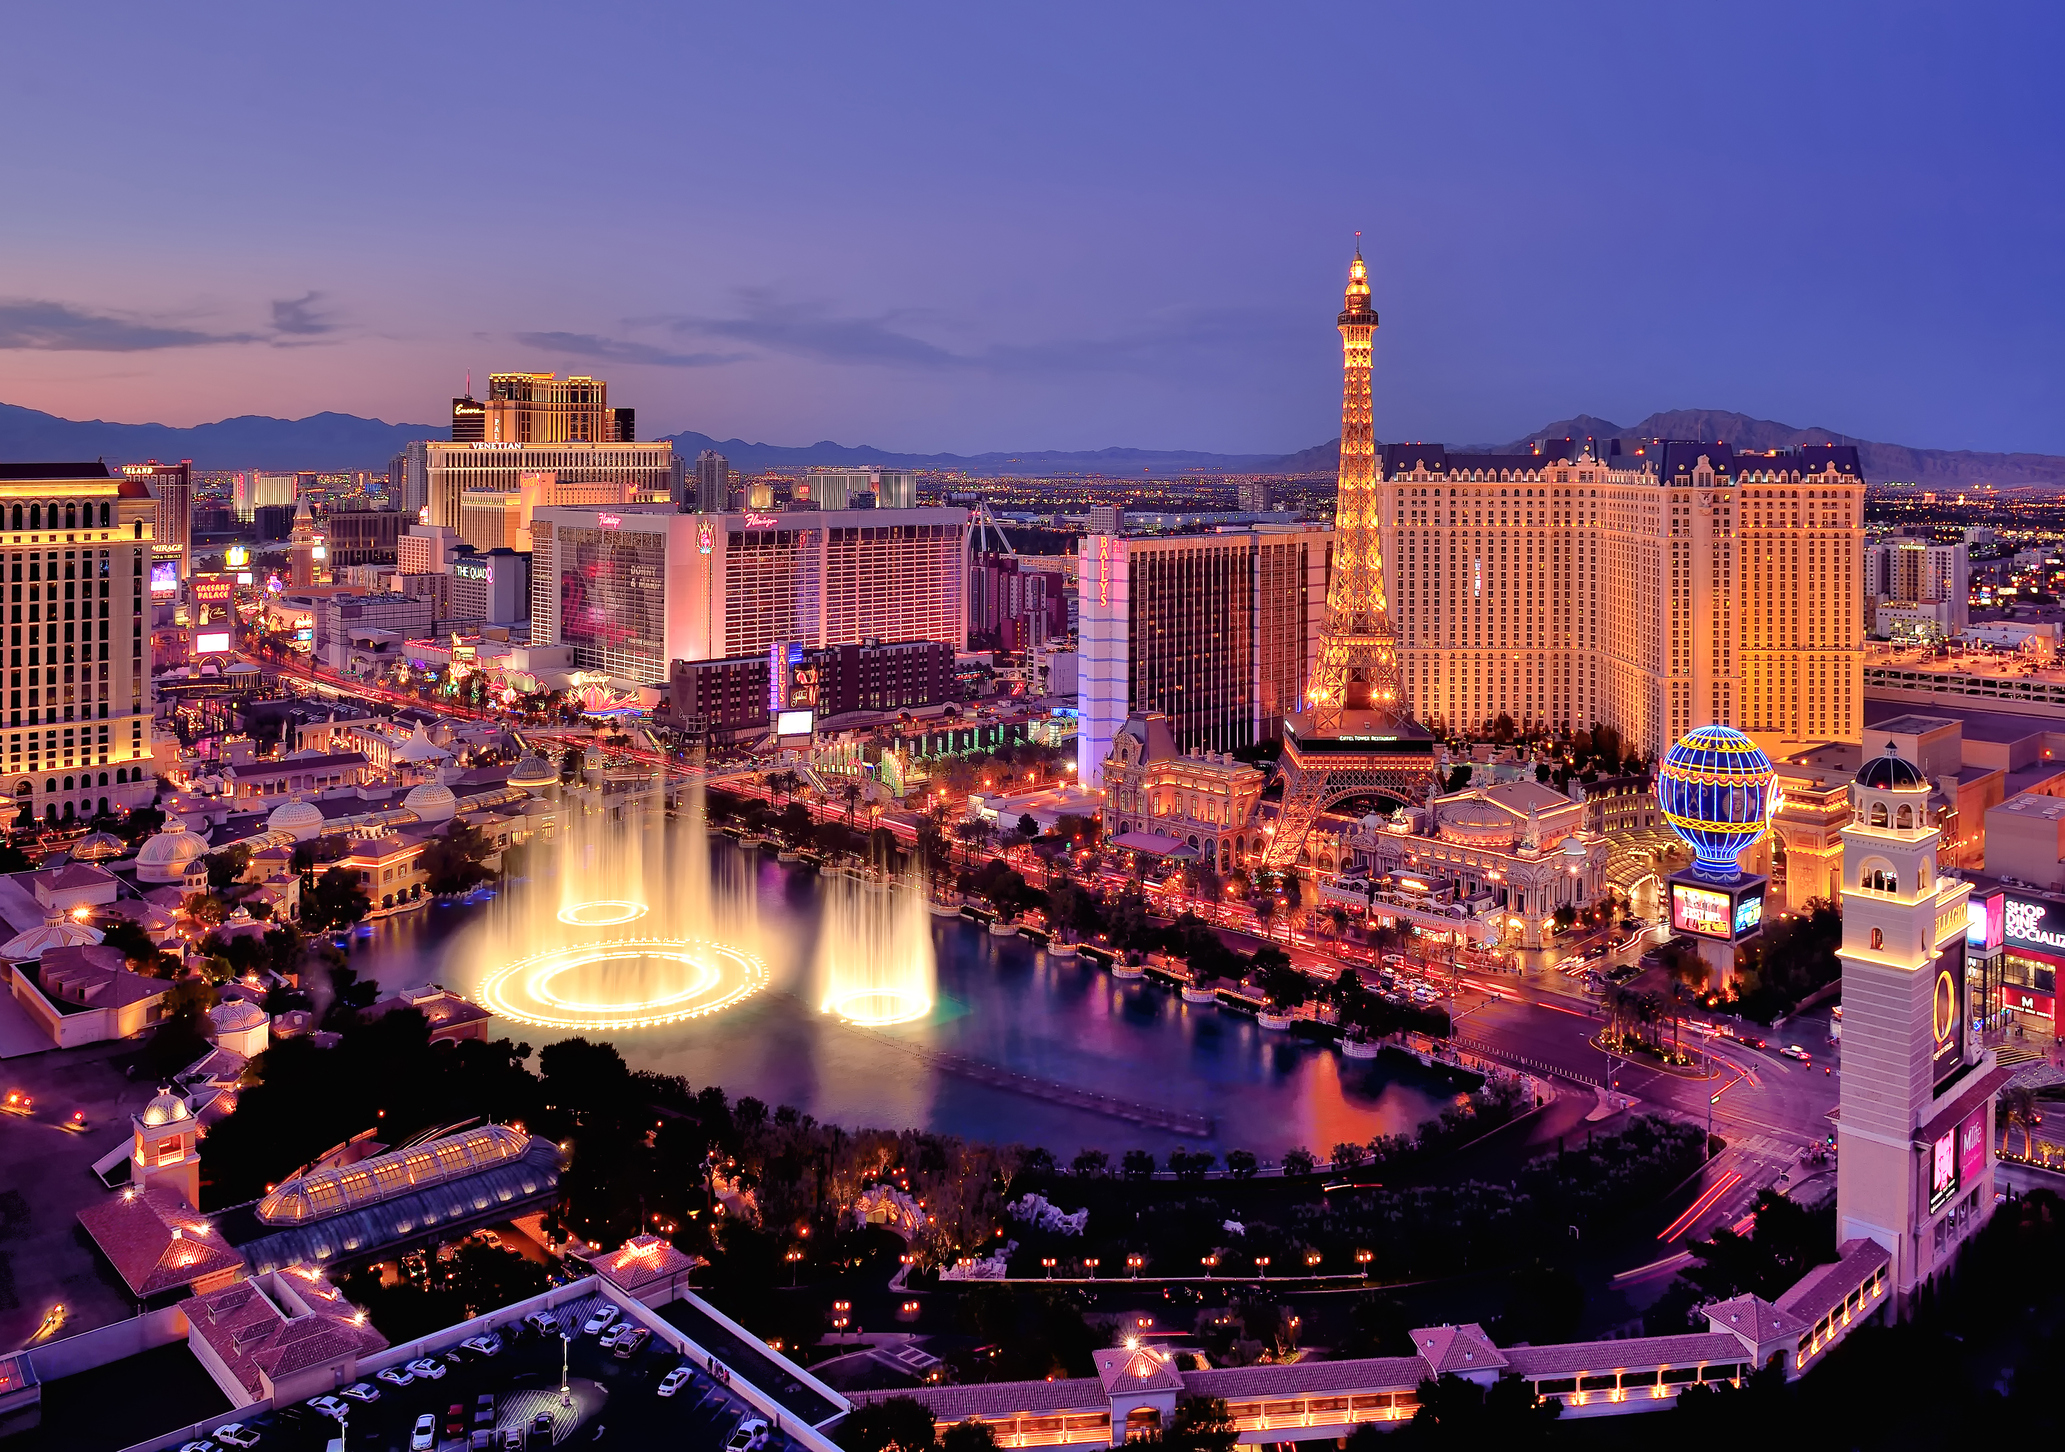
LAS VEGAS—Few places vacuum money from you like this glittering gambling and entertainment playground. That’s true for the visitors in town for Sunday’s Super Bowl —official motto: Excessive Celebration Encouraged. And it’s true for visitors any time, with the $US200 seats at the pool and the $US800 bottle service at nightclubs. All before you step onto the casino floor. You can fly here for as little as $US50 if you play your cards right. But people come to Vegas to spend, and the businesses here know it. This place hits travelers with potential upgrades every few steps. So I flew in for an experiment, a real-life version of the Jim Carrey comedy “Yes Man” (or “Yes Day” if you’re a Jennifer Garner fan). I said yes to every upgrade and VIP package to see just how much you get for your money, and what can be skipped. I had parameters. The $US3,999 helicopter ride to the top of Valley of Fire State Park for yoga was out. As was the $US4,000-a-night upgrade offer to a three-bedroom presidential suite at my hotel. Still, I cut lines, got a massage in the reserved seats at the Aria sportsbook during an NFL wild-card game, relaxed in a private lounge before a show at the Sphere , and drank a French 75 from a prime window seat at the Eiffel Tower Restaurant. In all, I spent $US976 to upgrade my Vegas visit. Was every upcharge worth it? Absolutely not. But a few are worth your money.
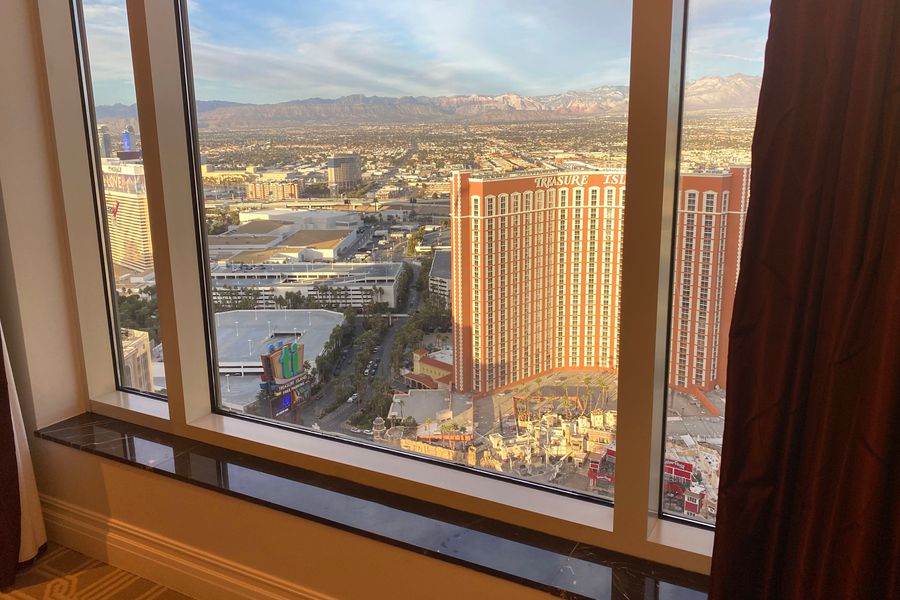
The offers began minutes after I booked a room for two nights at the luxury all-suite Palazzo resort. The price: $US480 before taxes and fees for two nights, a relative bargain on a holiday weekend in January. How much for a room booked last-minute for Super Bowl weekend? $US1,700 a night. I landed two upgrades after an email prompt gauged my interest: $US75 for early check-in and $US57 a night for a city view, the cheapest room category upgrade. Early check-in fees irk me , but this was worth it after my early flight. I was in the room by 11 a.m. The room was swank. The view of Treasure Island and the Mirage was nothing special.
I headed to Area15, an arts and entertainment complex. First stop: Meow Wolf ’s Omega Mart, a popular immersive art experience that takes visitors into a bizarro grocery store that links to an alternate dimension. Admission is $US54; upgrading to a $99 VIP package promised to “enhance my experience” but bought me a souvenir pin, VIP lanyard, a cocktail and a 15% discount I didn’t use at the gift shop. Maybe the good stuff comes with the $US129 scavenger hunt package. (As I perused products like cans of faux La Croix in mashed-potato flavour and wandered a dizzying hall of mirrors, I wondered how many visitors upgraded with a trip to a local dispensary beforehand.) Admission to stroll around the rest of Area15 is free, but I upgraded to a $US35 pass, which included five attractions, the best of which was the outdoor Liftoff ride with great views of the Strip.
Many resorts here gave up the buffet business for good during the pandemic . The Wicked Spoon buffet at the Cosmopolitan of Las Vegas still packs them in. Saturday brunch had an hour-long wait during my visit. VIP line to the rescue! $US35 gets you a head start on the $US62 all-you-can-eat feast of snow crab legs, sushi and slow-roasted strip loin. The best part: The manager overseeing the line comped the fee because she said she enjoyed talking to me and a friend while we waited. (I never identify myself to employees as a Wall Street Journal reporter on these types of assignments.) Suddenly playing with house money, I sprang for the unlimited mimosa package for $US33 after tax and tip, to go with the brunch base price. There is a 90-minute limit, but I had places to be.
My colleague Jason Gay calls the Sphere, the giant orb that sits behind the Venetian, a “beach ball peaking on acid.” He paid $US539 to see U2 at the new venue. In the biggest single splurge on my trip, I paid $US245 to see a 50-minute movie there. The Director’s Seat package promised VIP entry, preshow lounge access with free beer, wine and snacks and a souvenir Sphere T-shirt. The VIP entry was the best perk, letting me skip the clogged Regular Joe lines. I was one of the first people in the atrium, where a humanoid robot named Aura chatted with me and a couple from Arkansas who also took the VIP plunge. The robot asked them the secret to their 55-year marriage. We met again in the nearly empty lounge before the Darren Aronofsky show “Postcard From Earth.”
Delta Sky Club this ain’t: The small food spread included soft pretzels with cheese and mustard. The bartender did dig out a great local IPA, Atomic Duck, and pointed me to the popcorn that VIP guests could take into the movie. The package promises premium seating for the show, a trip around the globe in which seats rattled when elephants or a jumbo jet rumbled across the giant screen.
My seat was good, albeit one row up and an aisle over from my friends who paid $US79 for their standard tickets. The final Yes Day in Vegas is a spendy blur: $US190 to watch the Lions and Rams duke it out in an NFL playoff nail-biter from a high-top table with food and alcohol included in a roped-off section at Aria Resort & Casino. The rest of the sportsbook was standing room only.
Then there was the $US40-a-person fee for the window seat at the Eiffel Tower Restaurant overlooking the dancing Bellagio fountains. The couple celebrating their anniversary one table back couldn’t believe I paid the fee. I left Vegas a little spoiled and out of sorts. When Southwest Airlines offered a $US50 upgrade to jump to the front of its boarding line on my flight home, I clicked buy. Can’t wait to explain that one to the folks in Expense Accounting.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
