
Profiting From the Pet Boom

By ABBY SCHULTZ
Mon, Oct 2, 2023 11:58am 4 min
4 min

 4 min
Humans may not be acquiring pets at a pandemic-induced pace anymore, but they still are spending plenty on food, supplies, and services to take care of the furry members of their families.
Investors in public and private markets have their eyes on all that pet-care spending. Increasingly, consumers have gone beyond buying kibble to snapping up premium products and services that ensure their pets are living healthy, environmentally friendly lives. It’s a trend familiar to anyone who has followed the growth in eco-friendly wellness products and services for humans.
The shorthand for this phenomenon? The “humanisation of pets,” according to Milwaukee-based Baird.
“What that meant 10 years ago was you started to see the premiumisation of the quality of the diets and the emergence of grain-free brands and premium, cleaner-labeled food brands,” says Spencer DePree, a director in Baird’s global consumer and retail group. “That certainly is true today, but you’re starting to see that expand into other parts of the lifestyle of the pet.”
The entire pet economy is valued at about US$130 billion to US$140 billion, divided into four main categories: nutrition, products and supplies, healthcare, and services, according to Baird. Nutrition products snag most consumer dollars, but the so-called humanisation trend touches all of them.
Australia, Canada, and parts of Europe are leading the pet-market conversion to “non-traditional, more premium food and nutrition,” says Scott Ehlen, a director in Baird’s global consumer investment banking group. For the U.S., it’s a question of “how quickly, not if,” the trend will take hold, Ehlen says.
Penta spoke with DePree and Ehlen about what’s driving the growth in pet-related purchases and some of the companies on their radar screen.
Proactive vs. Reactive
One reason for the uptick in purchases of healthier pet products is consumers have realised they can proactively keep their pets happy and free from illness. The simplest step is to provide them with a diet that won’t lead to health problems in future years, and, as with humans, mix in nutritional supplements and treats with health benefits, such as dental care.
“That’s something you’ve seen in human wellness over the last five to seven years,” DePree says.
In pet food, that’s led companies to go beyond making grain-free kibble to producing fresh foods and to offering “toppers,” such as fish oils or freeze-dried raw meat. Companies are even developing foods that don’t rely on traditional beef and poultry proteins, such as Berkeley, Calif.-based Jiminy’s insect-based pet foods—a company backed by venture capital, according to private-markets data company PitchBook.
“Their value proposition is pretty impressive when you just look at the energy consumption that goes into producing a pound of beef,” DePree says.
As people spent more time at home with their pets during the pandemic, they also realised their furry companions have a lot of downtime. Humans that have returned to the office want to make sure their pets stay happy and active, so many are putting their dogs in daycare facilities with cameras that allow them to check in to see how their pup is doing.
“It’s not a kennel, it’s doggy daycare, where it’s analogous to taking your child to daycare,” Ehlen says.
There are a handful of franchisors backed by private equity in this sector including Dogtopia, which Ehlen says is one of the larger companies with at least 200 franchisees and more in the pipeline. An investment vehicle formed by the New York-based private-equity firm Red Barn Equity Partners with funding from institutions and family offices made a major investment in 2020 in the company, which offers daycare, boarding, and spa facilities, according to a news release.
Pet grooming is another area that’s prime for investment. Ehlen says he takes his own dog to a groomer who keeps track of appointments on a paper calendar. “It’s impossible to get a hold of her, impossible to schedule,” he says.
“A vast majority of the market continues to exist in that state in 2023,” Ehlen says. “You’re finally starting to see folks realise that this is a huge market, it’s a non-discretionary market, it’s going to be around forever. It’s just in desperate need of investment, of capital, of innovation.”
The ‘Pet’ Play in Food
The importance of pets to the economy is evident within the four major consumer products companies—Mars, Nestlé, Post Holdings, and General Mills. All include pet foods among their brands; Post, in fact, made a push into the business in February by purchasing Nature’s Way and Rachael Ray Nutrish, among other more standard pet food brands, from J.M. Smucker Co. for $1.2 billion.
For an investor interested in the growth of premium natural pet food, the only pure public-market play is Freshpet, based in Secaucus, N.J., DePree says.
While bigger companies have grabbed more market share, independent, private companies are “still the birthplace of new brands, new innovation, and that could be coming from either new companies or new product lines,” he says. “When the category validates itself or the scale hits, then you may see one of the bigger players jump in through an acquisition.”
Independent companies in the natural pet food space include the Farmer’s Dog, based in New York, which is backed by venture capital, according to Pitchbook. Denver-based Alphia, a pet food co-manufacturer that supplies other companies, was bought late last month by PAI Partners, a private-equity firm, from another PE firm, J.H. Whitney, according to a news release.
In March, the specialty pet food brand Natural Balance, announced it would merge with Canidae, which makes premium sustainable pet food, a news release said.
Before the stock market became more volatile last year, there was a “big queue of folks circling the wagons,” DePree says. Considering that the large consumer products companies are still trying to figure out how to grow this market, “over the next 18, 24 months, you’ll see some more stories become public.” For now, he says, “the demand for ways to play ‘pet’ outstrips the supply.”
The Internet-of-Things for Dogs
Pets aren’t exempt from humans’ obsession with tech, either. The latest pet-tech trends range from fitness trackers to food-monitoring devices that not only monitor how much and when your pet is eating, but also automatically order more food when you’re running low, DePree says.
Old-tech—such as electronic fences that keep dogs confined to a designated space—are being replaced by devices considered more humane and able to collect data on a pet’s behaviour, Ehlen says.
An example is Halo Collar, which uses wireless GPS and allows owners to set up zones to contain their pets wherever they are. The company, based in Woodcliff, N.J., and co-founded by dog psychologist Cesar Millan and tech innovator Ken Ehrman, was backed in May by Utah-based Decathlon Capital Partners, which provides revenue-based financing.
Most innovations in the pet economy so far have focused on dogs, but Ehlen and DePree say companies also have their sights on improving the lives of cats.
“If anyone is doing any innovation in cat, it’s alongside dog, but now you’re starting to see a more purpose-driven and specific sort of focus on the category,” DePress says. But he chides, “cats might be insulted at the humanisation concept—they probably hold themselves in a higher place.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min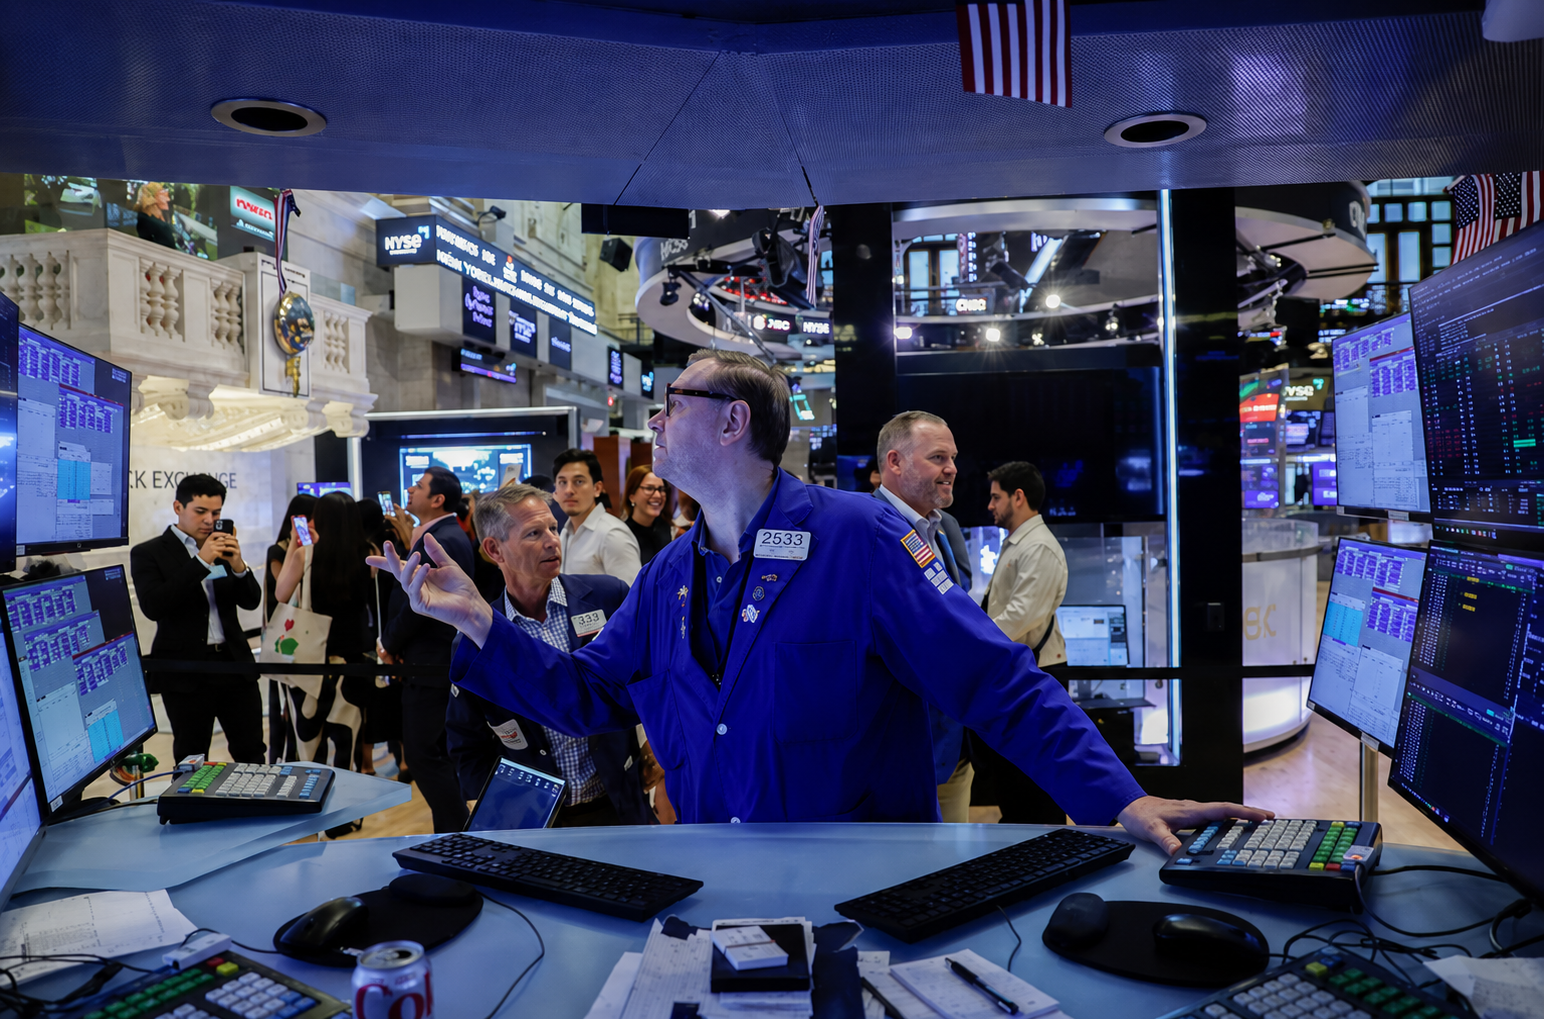
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”
