
Rest of World’s Growth Is at Trump’s Mercy
Growth in size of U.S. market gives him extra leverage in trade negotiations with other countries

By JOSH MITCHELL
Thu, Nov 14, 2024 8:49am 3 min
3 min


Growth in size of U.S. market gives him extra leverage in trade negotiations with other countries
3 min
Donald Trump will retake office in a global economy substantially transformed from eight years ago—one much more reliant on the U.S.
It means that the president-elect’s plans, including across the board tariffs, could pack an even greater wallop on other countries than the first round of “America First” economic policy. It also gives Trump much more leverage in negotiations over trade policy.
Strong growth since the pandemic has expanded the U.S.’s weight in the global economy. Its share of output among the Group of Seven wealthy nations is higher than at any point since at least the 1980s, International Monetary Fund data shows.
Growth in China, the world’s second-largest economy, has slowed. Germany, the largest European economy, is contracting. Many poorer economies are buckling under the weight of high debt.
U.S. gains in global output partly reflect the strong dollar, which pushes up the value of American output relative to that of foreign economies. But they also result from substantial increases in U.S. productivity compared with the rest of the world.
The changes in the global economy have made America, not China, the premier destination for foreign direct investment, enlarging the exposure that foreign companies have to the U.S. economy and changes in government policy. A booming U.S. stock market has attracted huge flows of investment dollars.

“The fact that much of the rest of the world is now struggling to generate demand on its own provides more reason for countries to try to reach some sort of accommodation with Trump,” said Brad Setser , a senior fellow at the Council on Foreign Relations.
Trump started imposing tariffs in 2018, primarily on China but also on Europe and other allies. Those tariffs fractured global trade, weighing on large exporting economies in Asia and Europe, while not obviously hurting the U.S., which is less reliant on foreign demand than its trading partners. Trump campaigned on a promise to impose at least a 60% tariff on China, and an across the board tariff of 10% to 20% on everywhere else.
America’s superior economic performance has been driven in part by energy independence and massive government spending, said Neil Shearing , chief economist at Capital Economics in London. Since the U.S. now exports more energy than it imports—including millions of barrels of oil each month to China—the nation as a whole benefits when energy prices rise, unlike for net importers such as China and Europe.
The upshot: America’s traditional role as the centre of gravity in the global economy has become even more pronounced in the years after Trump’s first-term tariffs, the pandemic, and Russia’s full-scale invasion of Ukraine.
U.S. influence over Europe’s economy is a case in point. The U.S. has cemented its position as Europe’s largest export market as trans-Atlantic trade surged in recent years and China’s imports from Europe stalled. The U.S. has replaced Russia as Europe’s major source of imported energy. Europe runs big trade surpluses with the U.S. but big trade deficits with China.
The result is access to the U.S. market is far more important for Europe than access to European markets for the U.S. That asymmetry will give Trump leverage in trade negotiations with Europe, according to economists.
Germany exports around 7% of its entire manufacturing value-added to the U.S., but Germany imports only around 0.8% of value-added in U.S. manufacturing, according to a September paper by researchers at Germany’s Ifo Institute for Economic Research.
“German business is vulnerable to Trump,” said Marcel Fratzscher , president of the Berlin-based economic research institute DIW Berlin.
Parts of Asia have benefited from the changes in supply chains sparked by Trump’s initial trade war with China. Many manufacturers, including Chinese ones, moved factories to places such as Vietnam and Cambodia. For the past two quarters, Southeast Asia’s exports to the U.S. have exceeded those to China.
But that now leaves them more exposed to across the board tariffs, a policy that Trump advisers say will be necessary to force manufacturing back to the U.S.
To be sure, Trump’s policies could create countervailing forces. Tariffs would decrease imports and potentially weigh on productivity, but tax cuts would drive up household and business spending, including, inevitably, on imports. Other countries could retaliate by placing tariffs on U.S. goods.
Meanwhile, a tight U.S. labor market has pushed up wages, which is good for those workers. But it could pressure employers to raise prices, in turn making them vulnerable to foreign competition.
Many economists are girding for a different type of trade war from Trump 1.0, when trade fell between the U.S. and China but was diverted elsewhere.
“As long as protectionism refers only to one country, China, the world can live with this,” said Joerg Kraemer , chief economist at Commerzbank. “The thing becomes difficult or dangerous if you implement tariffs on all countries. This would be a new era in global trade.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min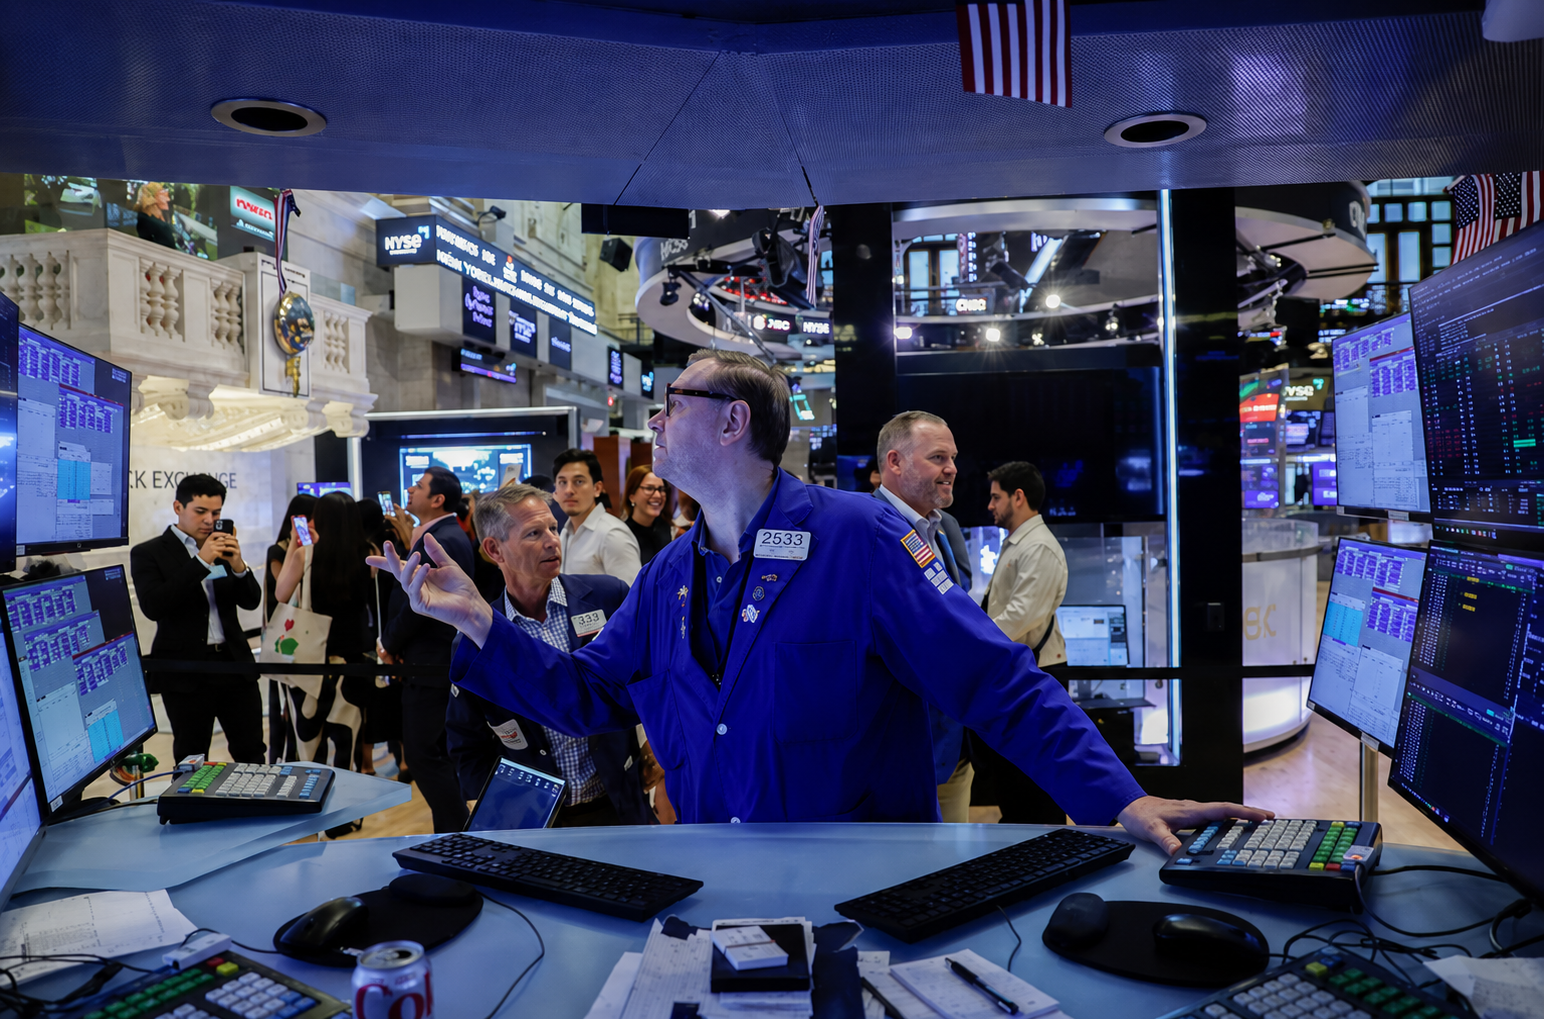
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”
