The Sandwich Generation Is Stressed Out, Low on Money and Short on Time
As millennials start to hit middle age—and boomers near their 80s—the number of Americans caring for both older and younger generations is poised to surge
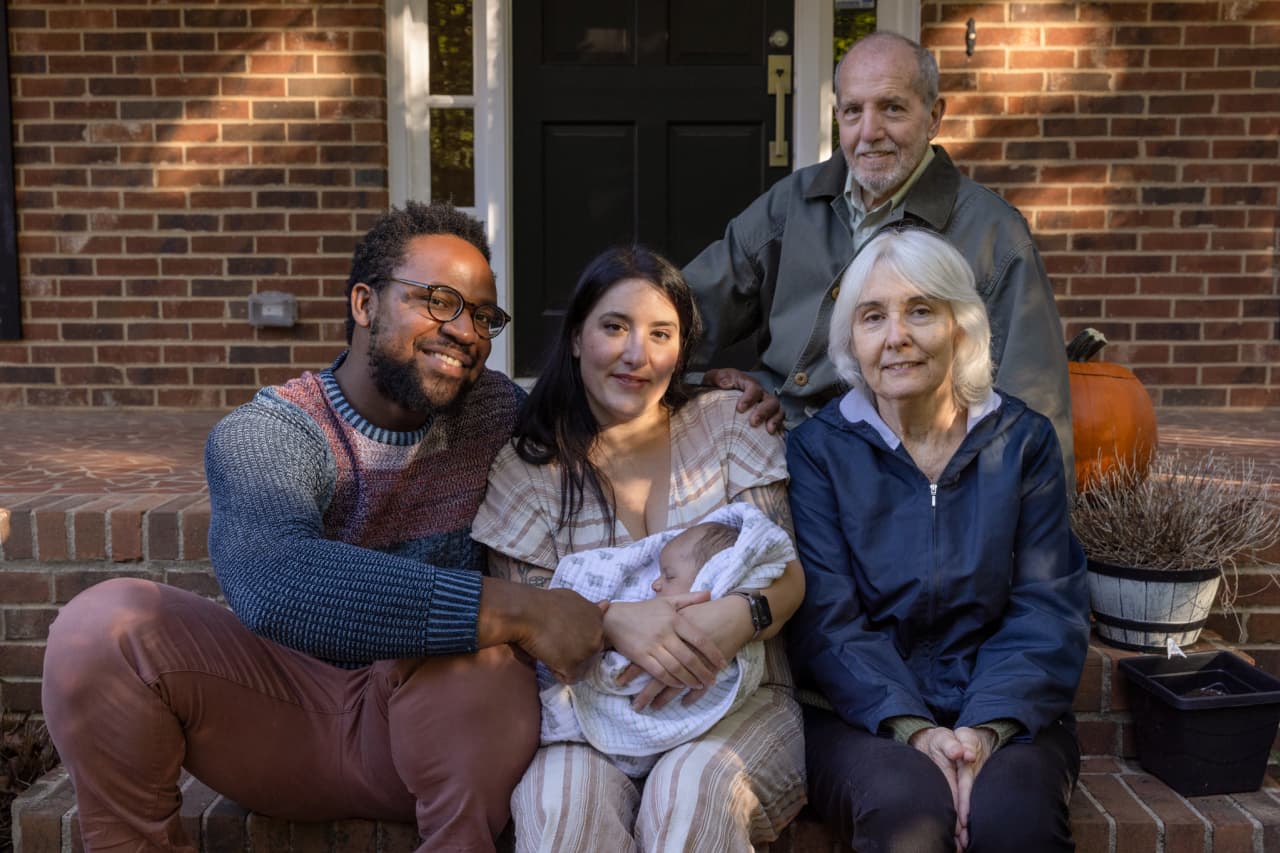
At 34, Kait Giordano is juggling her job, a newborn and two parents with dementia.
Just over a month into motherhood, she tends to her infant son and her live-in parents in the morning and afternoon, some days with the help of a rotating cast of paid companions at their Tucker, Ga., home. In the evenings, her husband, Tamrin, takes over while she colours hair.
They had already delayed starting a family when Kait’s father moved in a few years ago. Her mother moved in this year. “We chose to take this on,” she says. “We didn’t want to wait any longer.”
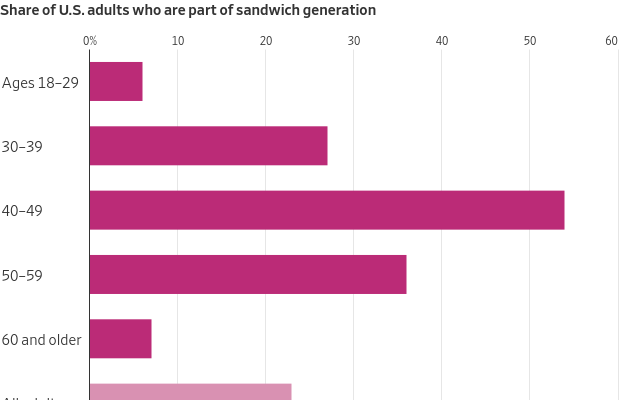
More Americans shoulder a double load of caring for their children and at least one adult , often a parent. The “sandwich generation” has grown to at least 11 million in the U.S., according to one estimate, and shifts in demographics, costs and work are making it a longer and tougher slog.
People are having children later, and they are living longer , often with care-intensive conditions such as dementia. That means many are taking care of elderly parents when their own kids are still young and require more intensive parenting—and for longer stretches of their lives than previous generations of sandwiched caregivers.
As the oldest millennials start to hit middle age —and baby boomers near their 80s—the number of Americans caring for older and younger family makes up a significant part of the electorate. Vice President Kamala Harris invoked the sandwich generation when she recently proposed expanding Medicare benefits to cover home healthcare.
“There are so many people in our country who are right in the middle,” the Democratic presidential candidate said on ABC’s “The View” this month. “It’s just almost impossible to do it all, especially if they work.”
Responding to the Harris proposal, former President Donald Trump ’s campaign said he would give priority to home-care benefits by shifting resources to at-home senior care and provide tax credits to support unpaid family caregivers.
The growing burden on this sandwich generation weakens careers and quality of life, and has ramifications for society at large. It is a drag on monthly budgets and long-term financial health.
A 40-something contributing $1,500 a month over five years to support an aging parent stands to lose more than $1 million in retirement savings, according to an analysis by Steph Wagner , national director of women and wealth at Northern Trust Wealth Management.
“It’s become incredibly expensive to manage the longevity that we’ve created,” says Bradley Schurman , an author and demographic strategist, who says that the demands of caring for older generations could push more people in midlife to retreat from the workforce, particularly women. “That’s a massive risk for the U.S. economy.”
Not too long ago, the typical sandwich caregiver was a woman in her late 40s with teenage kids and maybe a part-time job. Now, according to a 2023 AARP report, the average age of these caregivers is 44, and a growing share are men. Nearly a third are millennials and Gen Z. They are in the critical early-to-middle stages of their careers and three-quarters of them work full or part time.
Diana Fuller, 49, says being the go-to person for her 83-year-old mother’s care for more than four years has been stressful, even with her mother now living in a nearby, $10,000-a month memory-care centre in Charlotte., N.C. (Long-term-care insurance covers 75%; the rest is paid out of her mother’s savings.)
She has put on the back burner career goals such as ramping up the leg warmer business she started with her sister. She has missed moments such as her 9-year-old son’s school holiday concert last year because of her mother’s frequent hospital stays.
Her husband picks up a lot of the child care duties when her mom is in the hospital. Still, she says, “it often feels like everything is about to implode.”
The financial pressures are also growing for the sandwich generation. According to a Care.com survey of 2,000 parents, 60% of U.S. families spent 20% or more of their annual household income on child care last year, up from 51% of families in 2021. Meanwhile, the median cost of a home health aide climbed 10% last year to $75,500, data from long-term-care insurer Genworth Financial show.
Caregivers often risk paying for such costs in their own old age, financial advisers say. More than half reported in a 2023 New York Life survey that they had made a sacrifice to their own financial security to provide care for their parents on top of their children.
Many in the sandwich generation say they feel torn between the needs of their kids and parents. Liam Davitt , a public-relations professional, and his wife, Lisa Fels Davitt , recently moved from their Washington, D.C., condo to suburban New Jersey so that their 7-year-old son could be closer to cousins and go to a good public school. (They had previously paid for private school.)
That meant moving away from his 84-year-old mother in an independent living community. The long distance has made helping her even with little things more complicated, such as troubleshooting glitches with her iPhone. He recently enlisted a nearby fraternity brother to help her assemble a new walker.
An avid runner, he says he finds himself taking care of himself—avoiding potentially ankle-twisting mud runs and keeping up with his doctors’ appointments, for example—out of fear he won’t be able to care for his younger and older family.
“If all of a sudden I’m less mobile, then I’m more of a burden on my own family” says Davitt. He is planning to move his mother closer by.
The Giordanos, in Georgia, have made adjustments, too. With their newborn keeping them busy, they installed cameras and door chimes to help monitor Kait’s parents.
Her parents enjoy pushing their grandson in the stroller around the house while supervised, she says. When Tamrin comes home from work, he gives his in-laws dinner and medications while holding the baby.
The couple isn’t sure when they’ll have another child, which would require paying for more help.
“We may have to wait,” Kait said. “We’re very much living in the moment.”
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.