
Why the Silver Trade Shouldn’t Be Lumped In With GameStop Stock and AMC

By JACOB SONENSHINE
Wed, Feb 3, 2021 4:24am 3 min
3 min

 3 min
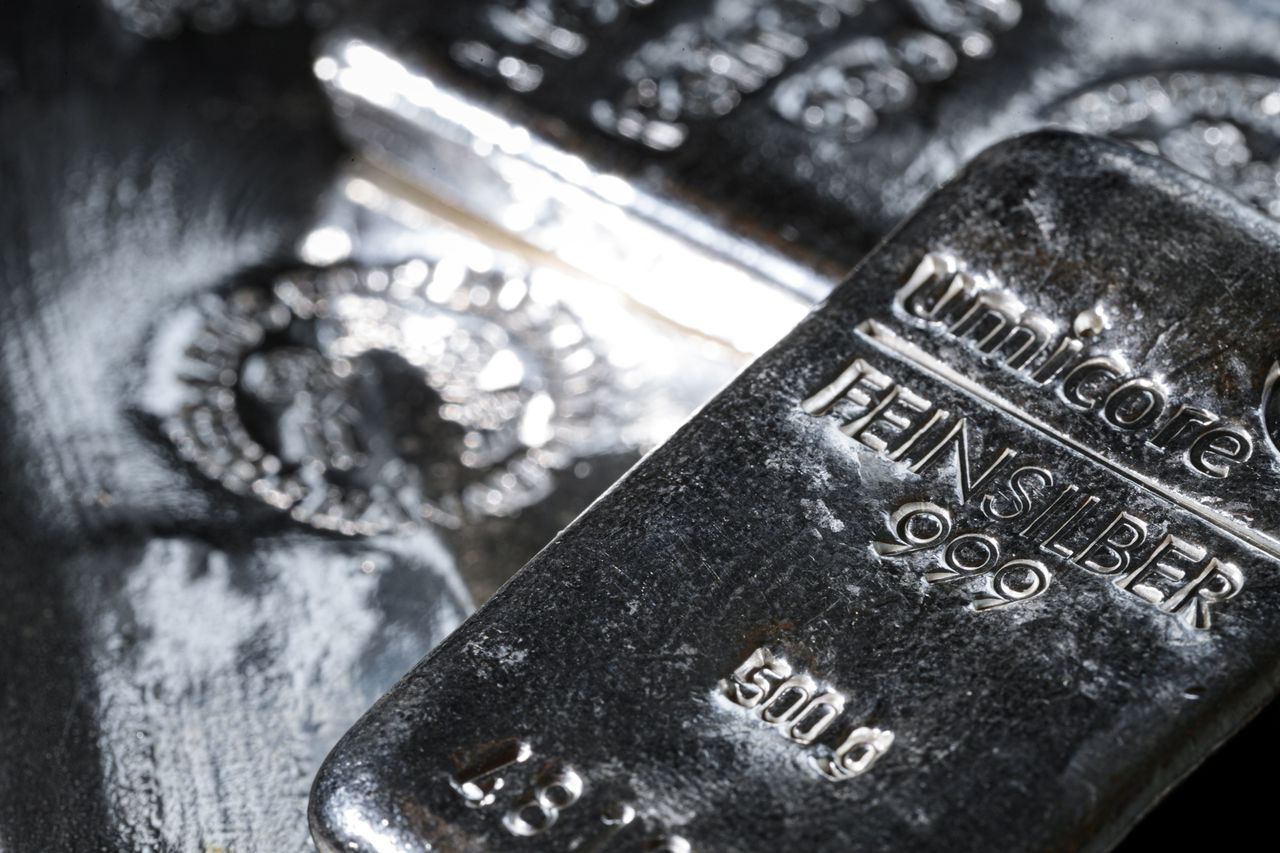
Silver soared, then dropped. Whatever happens now, the metal’s price movements will look nothing like what happened with the stocks that faced a spectacular short squeeze and are now falling.
Monday, the price of actual silver rose as much as 9% to $29.52 per ounce. “Retail traders who drove the short squeezes in stocks like GME last week were banding together to try and trigger a squeeze in silver,” wrote Tom Essaye, founder of Seven’s Report Research, in a note.
It all revolves around the practice of short selling, where people borrow a stock and sell it, hoping the price will fall, making it possible to buy shares at a lower price and return them. A short squeeze happens when the price of the stock rises, rather than falls, forcing short sellers to buy. If a lot of the stock available for trading has been sold short, there can be a scramble to buy that triggers spectacular price gains.
That is what happened with GameStop (ticker: GME) last month. Other stocks that had been aggressively sold short surged as well.
But the iShares Silver Trust (SLV), after rising 11% to $27.76 a share Monday, is now down 11% from that level. There are key differences between companies like GameStop and AMC Entertainment (AMC) and silver.
First off, GameStop rose as much as 1,800% in a few weeks in January. AMC rose as much as 890% in roughly the same period. The iShares Silver exchange-traded fund, which buys futures contracts linked to the direction of the metal’s price, rose to roughly its all-time high of $27, set in August, and failed to break past it.
With the price down Tuesday, fundamentals, rather than the possibility of a short squeeze, are returning to the fore. While silver is an asset that can take part in a “reflation rally,” or one that occurs when economic stimulus jolts an economy out of recession and spurs inflation, that possibility doesn’t seem to have been enough to send the silver ETF to a new high.
Importantly, options trading was an important factor in the gains for GameStop and AMC. Retail traders were buying calls, or the right to buy shares at a specified strike price on a later date. The hope is that an option’s strike price will be lower than the stock’s price when that day comes, making it possible to buy at the strike price and make a profit by immediately selling on the open market.
That possibility forces the brokers who wrote the options contracts to hedge by buying the shares. It adds to demand for a stock and can contribute to a short squeeze, as appears to have happened with GameStop and AMC. Retail traders posting on Reddit were able to move the stock without much capital because they could buy call options at a far lower price per underlying share than the cost of the actual stock.
For silver, the overarching theme is that retail traders can’t summon up the large pool of capital needed to create huge demand for silver.
Traders aren’t buying calls on silver right now, Andrew Smith, chief investment strategist at Delos Capital Advisors, told Barron’s, citing the activity he saw Tuesday. That’s partly because buying calls on commodity ETFs, which reflect a blended forward expected price—based on the prices forecast for several different dates—is a complex process.
Buying silver outright, which is what retail traders did, requires much more money. There are no call options and no need for brokers to hedge against them.
“Squeezing the market isn’t likely” from here, wrote Jeff Currie, global head of commodities research at Goldman Sachs, in a note. In order for the WallStreetBets crowd to send silver prices up the 700% they rose in 1980, when the wealthy Hunt brothers gobbled up almost one-third of the global supply, they would have to own 4,600 tons of silver each.
Silver could certainly charge ahead, just not so fast so soon.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
