Worldwide Efforts to Reverse the Baby Shortage Are Falling Flat
Subsidised minivans, no income taxes: Countries have rolled out a range of benefits to encourage bigger families, with no luck
By CHELSEY DULANEY
Tue, Oct 15, 2024 9:43am 7min
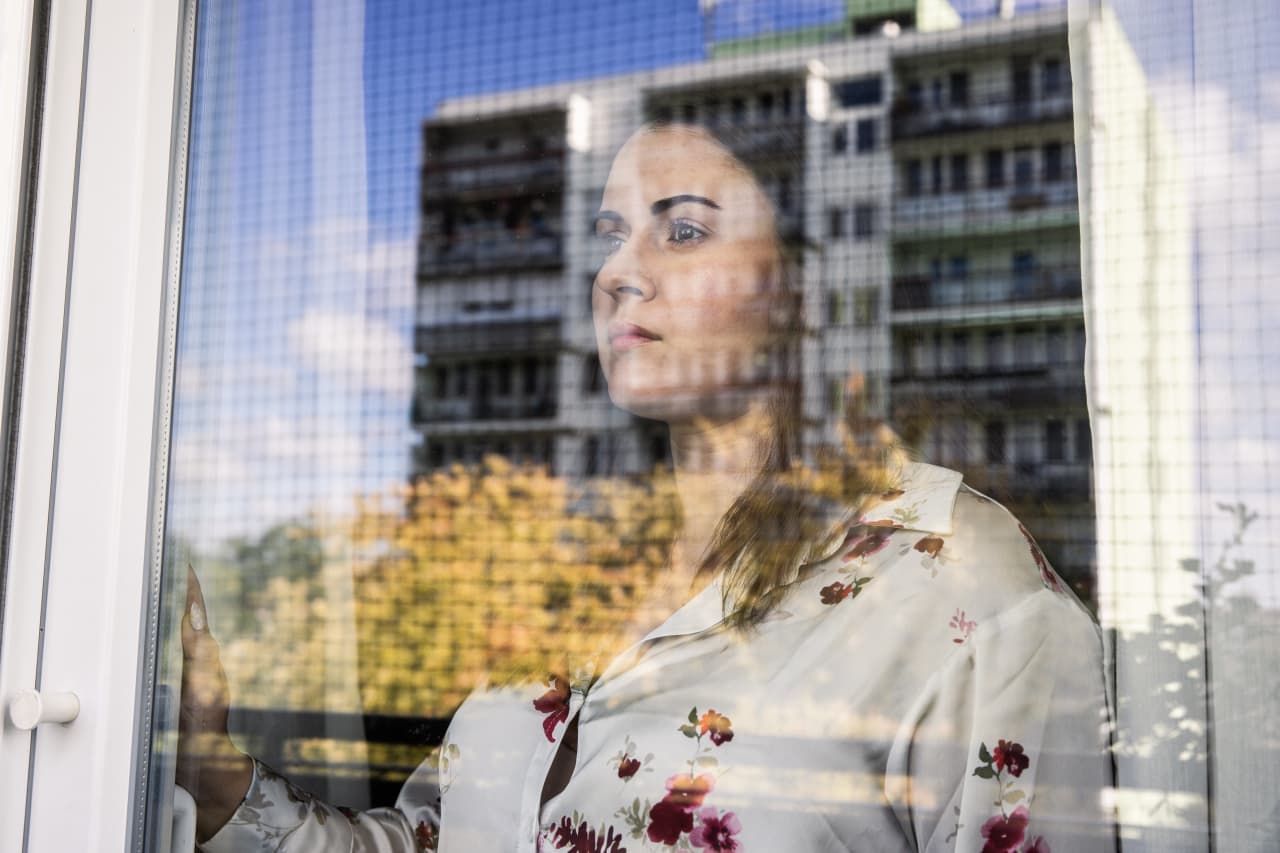
Orsolya Kocsis in Budapest hasn’t changed her mind about not wanting children. Photo: Akos Stiller for WSJ
Imagine if having children came with more than $150,000 in cheap loans, a subsidised minivan and a lifetime exemption from income taxes.
Would people have more kids? The answer, it seems, is no.
These are among the benefits—along with cheap child care, extra vacation and free fertility treatments—that have been doled out to parents in different parts of Europe, a region at the forefront of the worldwide baby shortage. Europe’s overall population shrank during the pandemic and is on track to contract by about 40 million by 2050, according to United Nations statistics.
Birthrates have been falling across the developed world since the 1960s. But the decline hit Europe harder and faster than demographers expected—a foreshadowing of the sudden drop in the U.S. fertility rate in recent years.
Reversing the decline in birthrates has become a national priority among governments worldwide, including in China and Russia , where Vladimir Putin declared 2024 “the year of the family.” In the U.S., both Kamala Harris and Donald Trump have pledged to rethink the U.S.’s family policies . Harris wants to offer a $6,000 baby bonus. Trump has floated free in vitro fertilisation and tax deductions for parents.
Europe and other demographically challenged economies in Asia such as South Korea and Singapore have been pushing back against the demographic tide with lavish parental benefits for a generation. Yet falling fertility has persisted among nearly all age groups, incomes and education levels. Those who have many children often say they would have them even without the benefits. Those who don’t say the benefits don’t make enough of a difference.
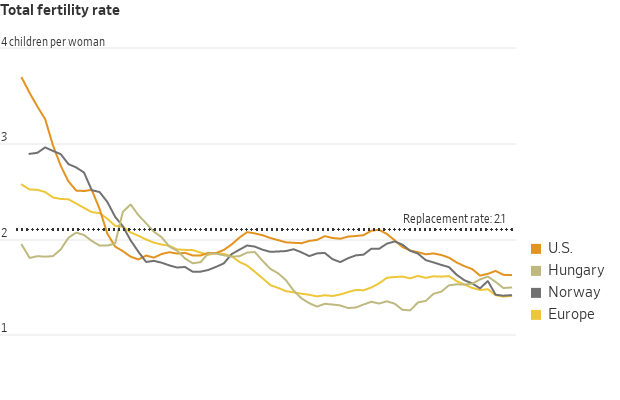
Two European countries devote more resources to families than almost any other nation: Hungary and Norway. Despite their programs, they have fertility rates of 1.5 and 1.4 children for every woman, respectively—far below the replacement rate of 2.1, the level needed to keep the population steady. The U.S. fertility rate is 1.6.
Demographers suggest the reluctance to have kids is a fundamental cultural shift rather than a purely financial one.
“I used to say to myself, I’m too young. I have to finish my bachelor’s degree. I have to find a partner. Then suddenly I woke up and I was 28 years old, married, with a car and a house and a flexible job and there were no more excuses,” said Norwegian Nancy Lystad Herz. “Even though there are now no practical barriers, I realised that I don’t want children.”
The Hungarian model
Both Hungary and Norway spend more than 3% of GDP on their different approaches to promoting families—more than the amount they spend on their militaries, according to the Organization for Economic Cooperation and Development.
Hungary says in recent years its spending on policies for families has exceeded 5% of GDP. The U.S. spends around 1% of GDP on family support through child tax credits and programs aimed at low-income Americans.
Hungary’s subsidised housing loan program has helped almost 250,000 families buy or upgrade their homes, the government says. Orsolya Kocsis, a 28-year-old working in human resources, knows having kids would help her and her husband buy a larger house in Budapest, but it isn’t enough to change her mind about not wanting children.
“If we were to say we’ll have two kids, we could basically buy a new house tomorrow,” she said. “But morally, I would not feel right having brought a life into this world to buy a house.”
Promoting baby-making, known as pro natalism, is a key plank of Prime Minister Viktor Orbán ’s broader populist agenda . Hungary’s biennial Budapest Demographic Summit has become a meeting ground for prominent conservative politicians and thinkers. Former Fox News anchor Tucker Carlson and JD Vance, Trump’s vice president pick, have lauded Orbán’s family policies.
Orbán portrays having children inside what he has called a “traditional” family model as a national duty, as well as an alternative to immigration for growing the population. The benefits for child-rearing in Hungary are mostly reserved for married, heterosexual, middle-class couples. Couples who divorce lose subsidised interest rates and in some cases have to pay back the support.
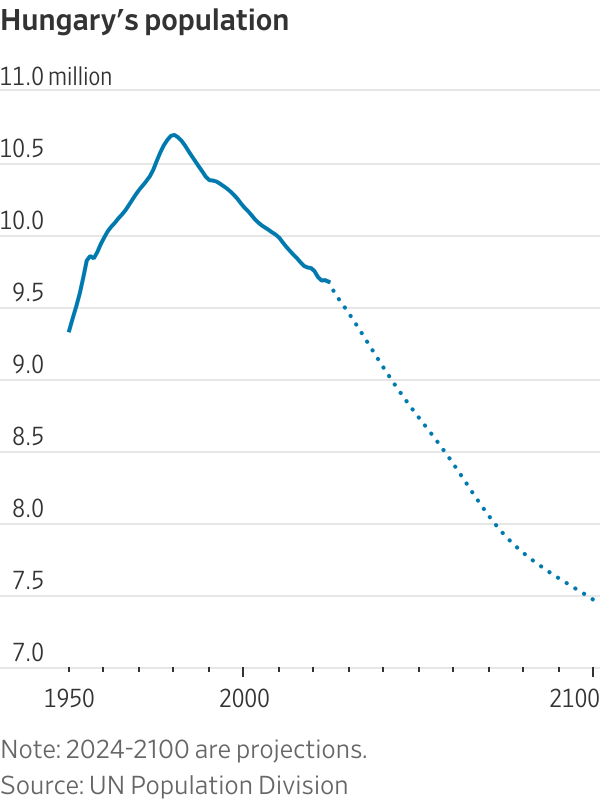
Hungary’s population, now less than 10 million, has been shrinking since the 1980s. The country is about the size of Indiana.
“Because there are so few of us, there’s always this fear that we are disappearing,” said Zsuzsanna Szelényi, program director at the CEU Democracy Institute and author of a book on Orbán.
Hungary’s fertility rate collapsed after the fall of the Soviet Union and by 2010 was down to 1.25 children for every woman. Orbán, a father of five, and his Fidesz party swept back into power that year after being ousted in the early 2000s. He expanded the family support system over the next decade.
Hungary’s fertility rate rose to 1.6 children for every woman in 2021. Ivett Szalma, an associate professor at Corvinus University of Budapest, said that like in many other countries, women in Hungary who had delayed having children after the global financial crisis were finally catching up.
Then progress stalled. Hungary’s fertility rate has fallen for the past two years. Around 51,500 babies have been born there this year through August, a 10% drop compared with the same period last year. Many Hungarian women cite underfunded public health and education systems and difficulties balancing work and family as part of their hesitation to have more children.
Anna Nagy, a 35-year-old former lawyer, had her son in January 2021. She received a loan of about $27,300 that she didn’t have to start paying back until he turned 3. Nagy had left her job before getting pregnant but still received government-funded maternity payments, equal to 70% of her former salary, for the first two years and a smaller amount for a third year.
She used to think she wanted two or three kids, but now only wants one. She is frustrated at the implication that demographic challenges are her responsibility to solve. Economists point to increased immigration and a higher retirement age as other offsets to the financial strains on government budgets from a declining population.
“It’s not our duty as Hungarian women to keep the nation alive,” she said.
Big families
Hungary is especially generous to families who have several children, or who give birth at younger ages. Last year, the government announced it would restrict the loan program used by Nagy to women under 30. Families who pledge to have three or more children can get more than $150,000 in subsidised loans. Other benefits include a lifetime exemption from personal taxes for mothers with four or more kids, and up to seven extra annual vacation days for both parents.
Under another program that’s now expired, nearly 30,000 families used a subsidy to buy a minivan, the government said.
Critics of Hungary’s family policies say the money is wasted on people who would have had large families anyway. The government has also been criticised for excluding groups such as the minority Roma population and poorer Hungarians. Bank accounts, credit histories and a steady employment history are required for many of the incentives.
Orbán’s press office didn’t respond to requests for comment. Tünde Fűrész, head of a government-backed demographic research institute, disagreed that the policies are exclusionary and said the loans were used more heavily in economically depressed areas.
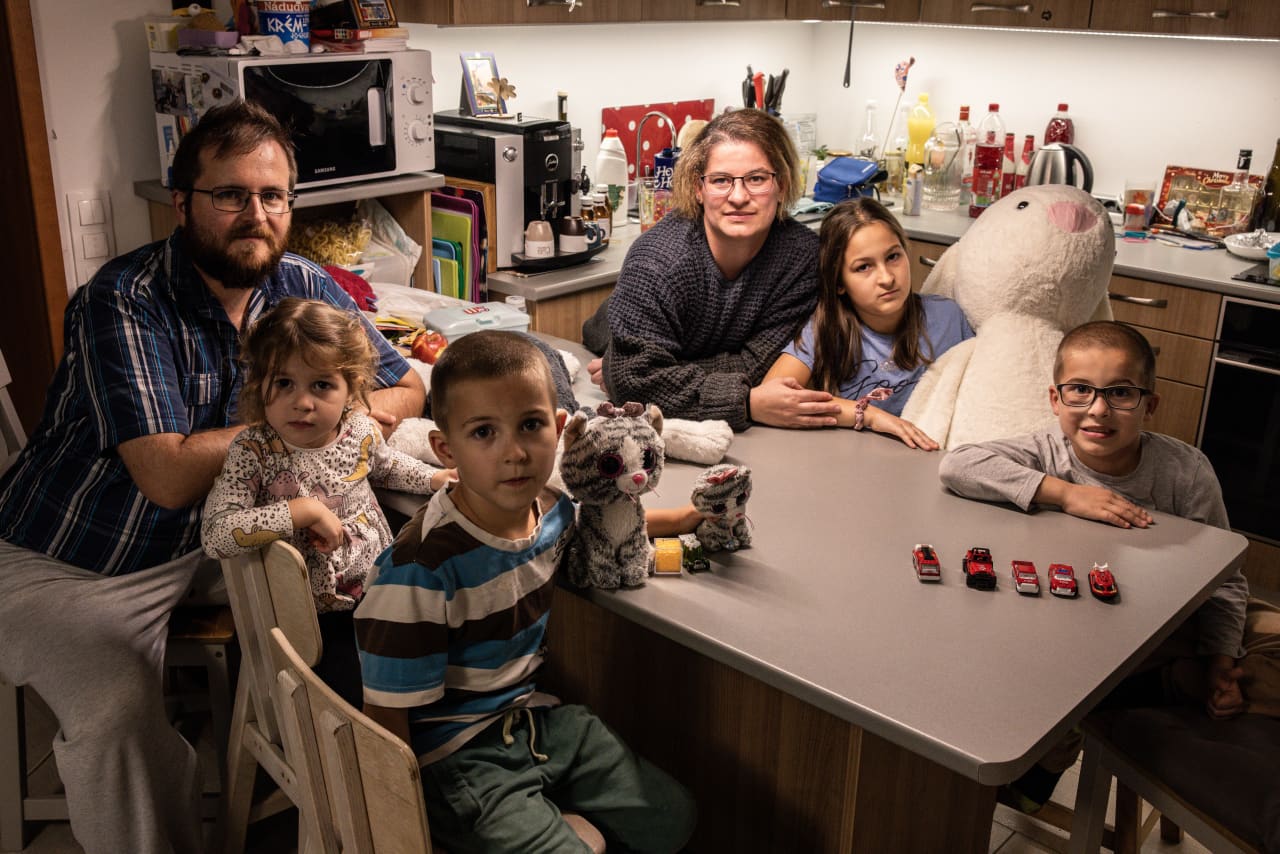
Eszter Gerencsér and her husband, Tamas, always wanted a big family. Photo: Akos Stiller for WSJ
Government programs weren’t a determining factor for Eszter Gerencsér, 37, who said she and her husband always wanted a big family. They have four children, ages 3 to 10.
They received about $62,800 in low-interest loans through government programs and $35,500 in grants. They used the money to buy and renovate a house outside of Budapest. After she had her fourth child, the government forgave $11,000 of the debt. Her family receives a monthly payment of about $40 a month for each child.
Most Hungarian women stay home with their children until they turn 2, after which maternity payments are reduced. Publicly run nurseries are free for large families like hers. Gerencsér worked on and off between her pregnancies and returned full-time to work, in a civil-service job, earlier this year.
She still thinks Hungarian society is stacked against mothers and said she struggled to find a job because employers worried she would have to take lots of time off.
The country’s international reputation as family-friendly is “what you call good marketing,” she said.
Gina Ekholt said the government’s policies have helped offset much of the costs of having a child. Photo: Signe Fuglesteg Luksengard for WSJ
Nordic largesse
Norway has been incentivising births for decades with generous parental leave and subsidised child care. New parents in Norway can share nearly a year of fully paid leave, or around 14 months at 80% pay. More than three months are reserved for fathers to encourage more equal caregiving. Mothers are entitled to take at least an hour at work to breast-feed or pump.
The government’s goal has never been explicitly to encourage people to have more children, but instead to make it easier for women to balance careers and children, said Trude Lappegard, a professor who researches demography at the University of Oslo. Norway doesn’t restrict benefits for unmarried parents or same-sex couples.
Its fertility rate of 1.4 children per woman has steadily fallen from nearly 2 in 2009. Unlike Hungary, Norway’s population is still growing for now, due mostly to immigration.
“It is difficult to say why the population is having fewer children,” Kjersti Toppe, the Norwegian Minister of Children and Families, said in an email. She said the government has increased monthly payments for parents and has formed a committee to investigate the baby bust and ways to reverse it.
More women in Norway are childless or have only one kid. The percentage of 45-year-old women with three or more children fell to 27.5% last year from 33% in 2010. Women are also waiting longer to have children—the average age at which women had their first child reached 30.3 last year. The global surge in housing costs and a longer timeline for getting established in careers likely plays a role, researchers say. Older first-time mothers can face obstacles: Women 35 and older are at higher risk of infertility and pregnancy complications.
Gina Ekholt, 39, said the government’s policies have helped offset much of the costs of having a child and allowed her to maintain her career as a senior adviser at the nonprofit Save the Children Norway. She had her daughter at age 34 after a round of state-subsidised IVF that cost about $1,600. She wanted to have more children but can’t because of fertility issues.
She receives a monthly stipend of about $160 a month, almost fully offsetting a $190 monthly nursery fee.
“On the economy side, it hasn’t made a bump. What’s been difficult for me is trying to have another kid,” she said. “The notion that we should have more kids, and you’re very selfish if you have only had one…those are the things that took a toll on me.”
Her friend Ewa Sapieżyńska, a 44-year-old Polish-Norwegian writer and social scientist with one son, has helped her see the upside of the one-child lifestyle. “For me, the decision is not about money. It’s about my life,” she said.
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Related Stories
Money
How Families Can Beat 7% Mortgage Rates and Lower Their Tax Bills
By Laura Saunders 09/10/2026
Money
The Stock Market’s Breezy Summer Is Over. Investors Beware.
By Hannah Erin Lang 08/09/2026
Money
The Sudden Unraveling of Wall Street’s Momentum Trade
By Gregory Zuckerman and Gunjan Banerji 31/08/2026
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
By Laura Saunders
Fri, Oct 9, 2026 4min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.


 7 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



