
Louis Vuitton Unveils Its Most Extravagant High-Jewellery Collection Ahead of Olympics

By LAURIE KAHLE
Sun, Jun 9, 2024 7:00am 3 min
3 min

 3 min
As the world turns its eyes to Paris for the start of the Summer Olympics next month, Louis Vuitton pulled out all the stops for its largest, most extravagant, and expensive high-jewellery collection with the title Awakened Hands, Awakened Minds.
Making its debut in St. Tropez on Wednesday night, the collection will encompass 13 themes and 220 pieces, some of which have yet to be unveiled. Of the 100 unique pieces that were exhibited as the first chapter, one overarching theme is clear: French pride and the celebration of the remarkably transformative period in 19th-century France, which witnessed an explosion of French influence and inventiveness.
“France in the 19th century was a phenomenal time of incredible change, and when Paris really became the centre of the world,” says Francesca Amfitheatrof, artistic director for watches and jewellery, in a news release. “The design language of Awakened Hands, Awakened Minds reflects that—all its intricacies, complications, and innovations—turned into incredible jewels.”
The collection explores a journey through that century, beginning with the end of royal court rule, which resulted in a surge of creativity and talent as France’s ateliers and master craftsmen explored and experimented without limits. Among those influenced by this vibrant zeitgeist was a 16-year-old Louis Vuitton, who arrived in Paris in 1837. The apprentice developed his own unique trunkmaking métier, devising a flat and stackable trunk specifically designed for travel.
“Craftsmanship becomes the currency of this country,” Amfitheatrof said. “It is the birth of France’s Art de Vivre —and the birth of what we know as luxury today.”
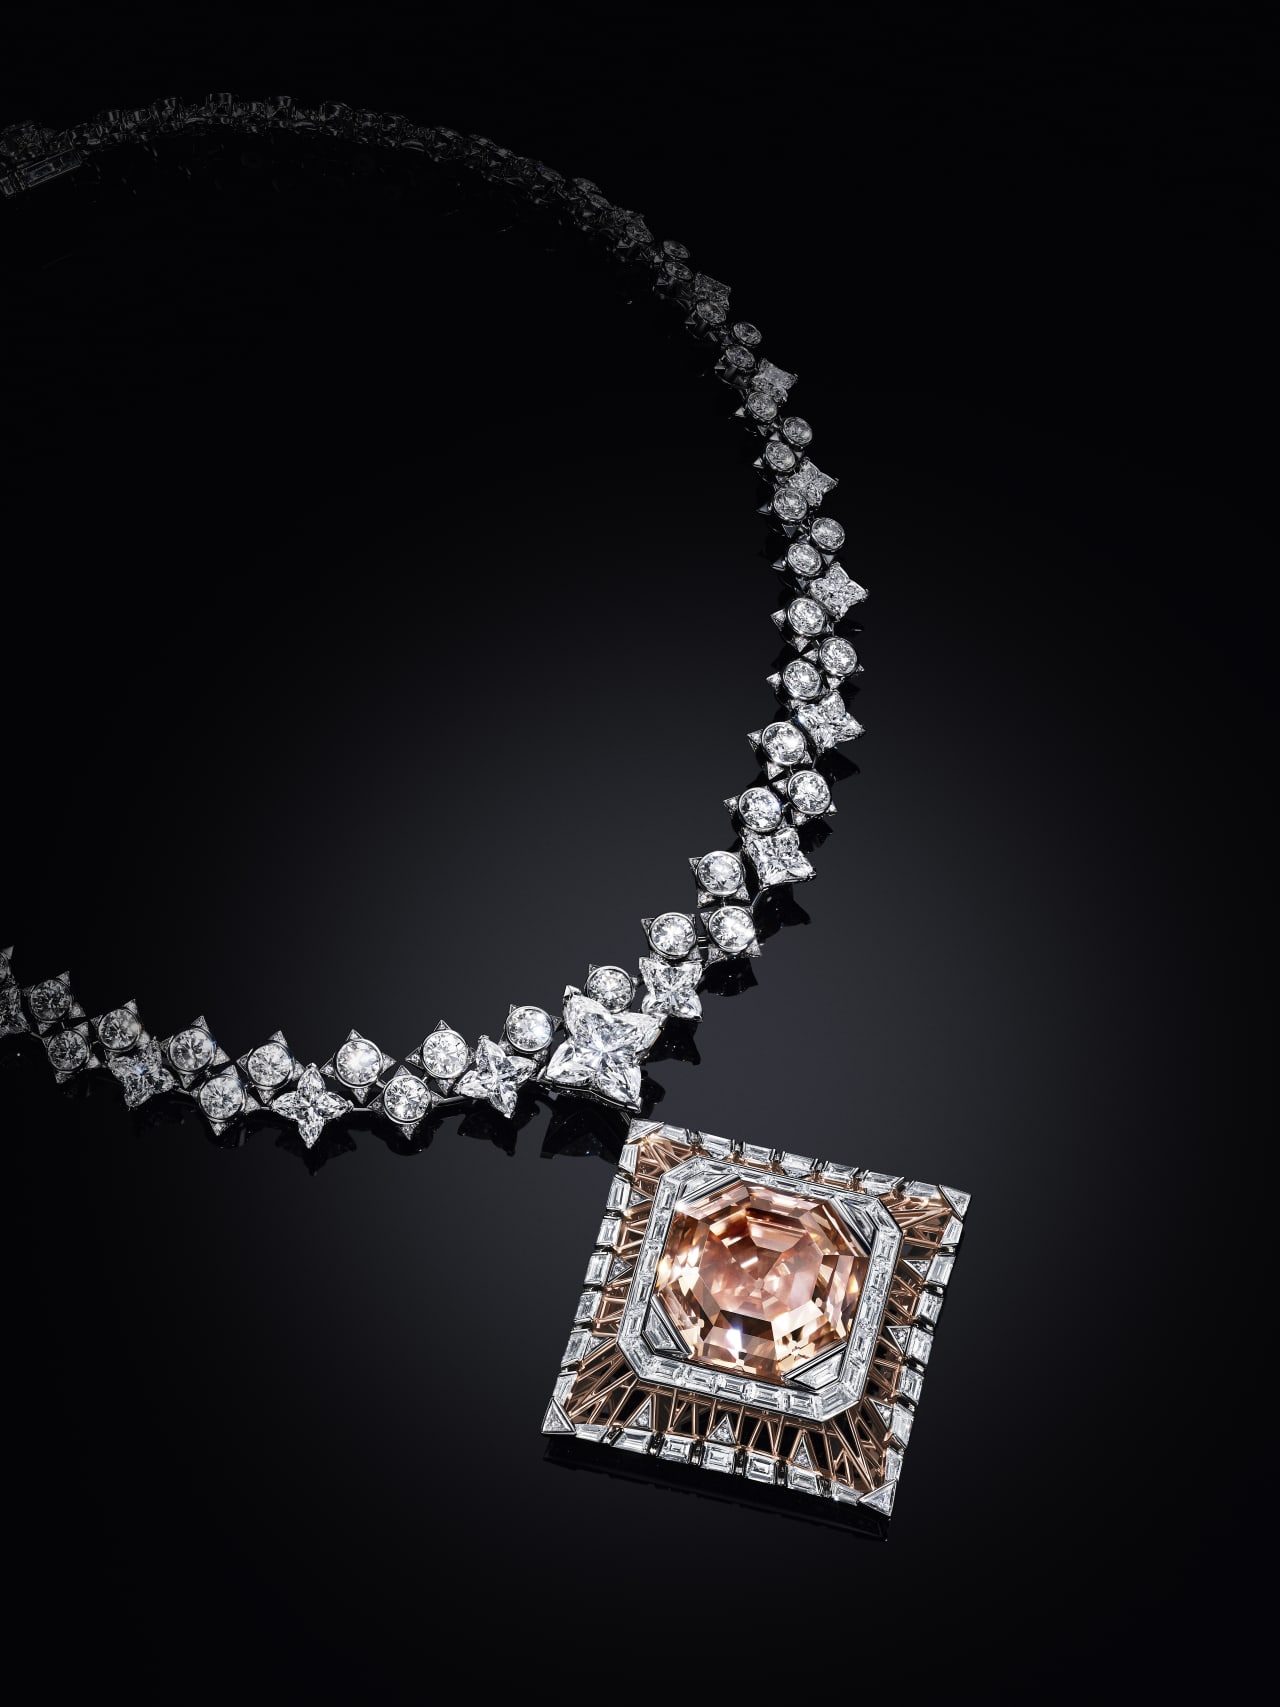
The collection’s Splendeur suite took inspiration from an imperial bed embellished with low-relief woodwork in lace-like floral patterns. But the luxury brand is looking to compete for consumers with more than just aesthetics: The jewels feature more than 110 perfectly matched rubies from Mozambique, all fully traceable through blockchain technology, making Louis Vuitton the first to offer traceability of coloured stones.
Louis Vuitton’s iconic LV Monogram Flower is the chosen theme. The symbol was designed by Louis Vuitton’s son Georges in 1896 in memory of his late father. The flower is portrayed in gold and diamonds with a large center ruby in earrings that complement a high collar, transformable necklace set with 52 rubies framed with an intricate, woven mesh of carved gold flowers. Among the collection’s most complex creations, the Splendeur necklace required the workmanship of 17 setters and 30 jewellers, who spent a total of 3,217 hours on its creation.
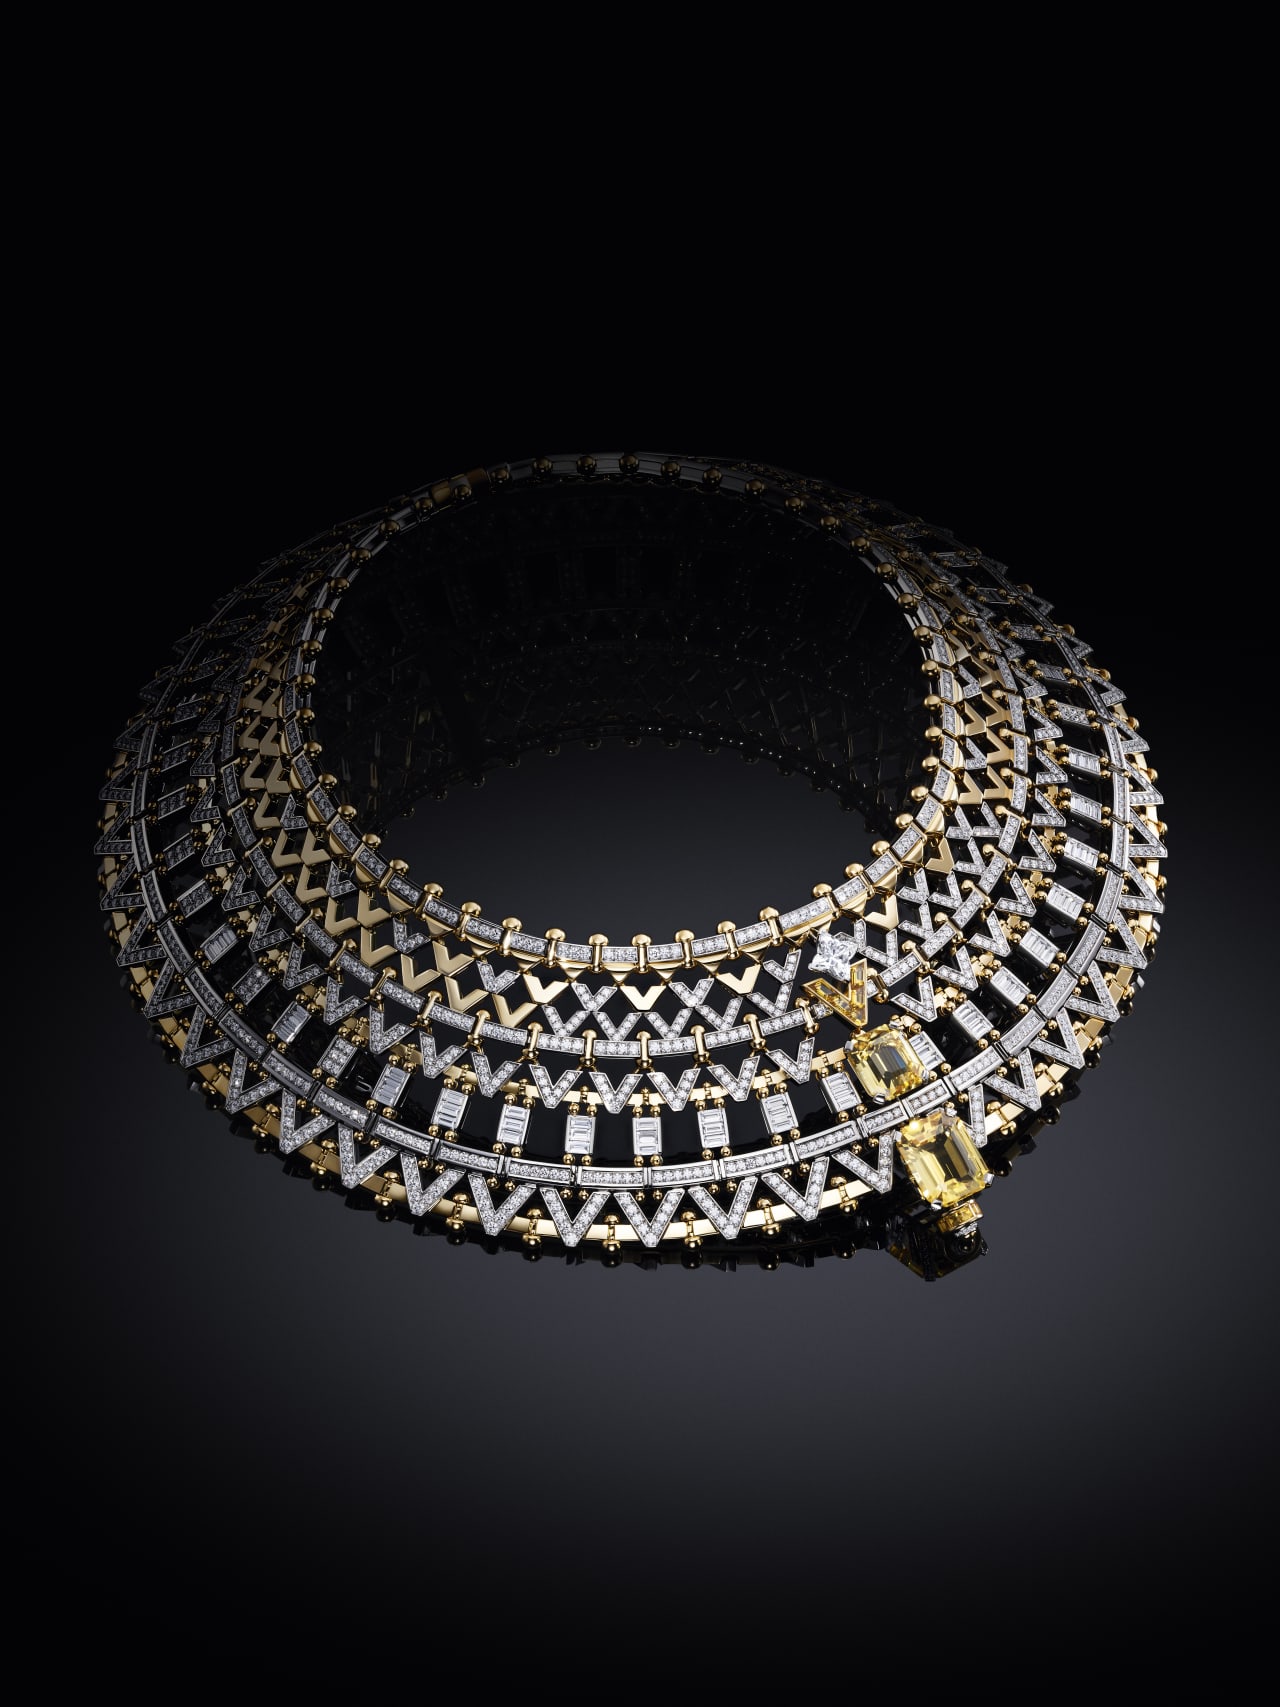
Louis Vuitton’s passion for travel is explored in the Vision necklace, which plays on the rivets of Louis Vuitton trunks. Crafted in platinum, yellow gold, diamonds, and yellow sapphires, the disruptive design interlaces V-shaped structures, highlighted with two octagonal-cut yellow sapphires measuring 13.47 carats and 11.79 carats. The piece occupied five jewellers, who mounted and set the necklace section by section over the course of 2,504 hours.
The masterpiece of the entire collection is the Cœur de Paris, the most expensive high-jewellery piece the maison has ever produced.
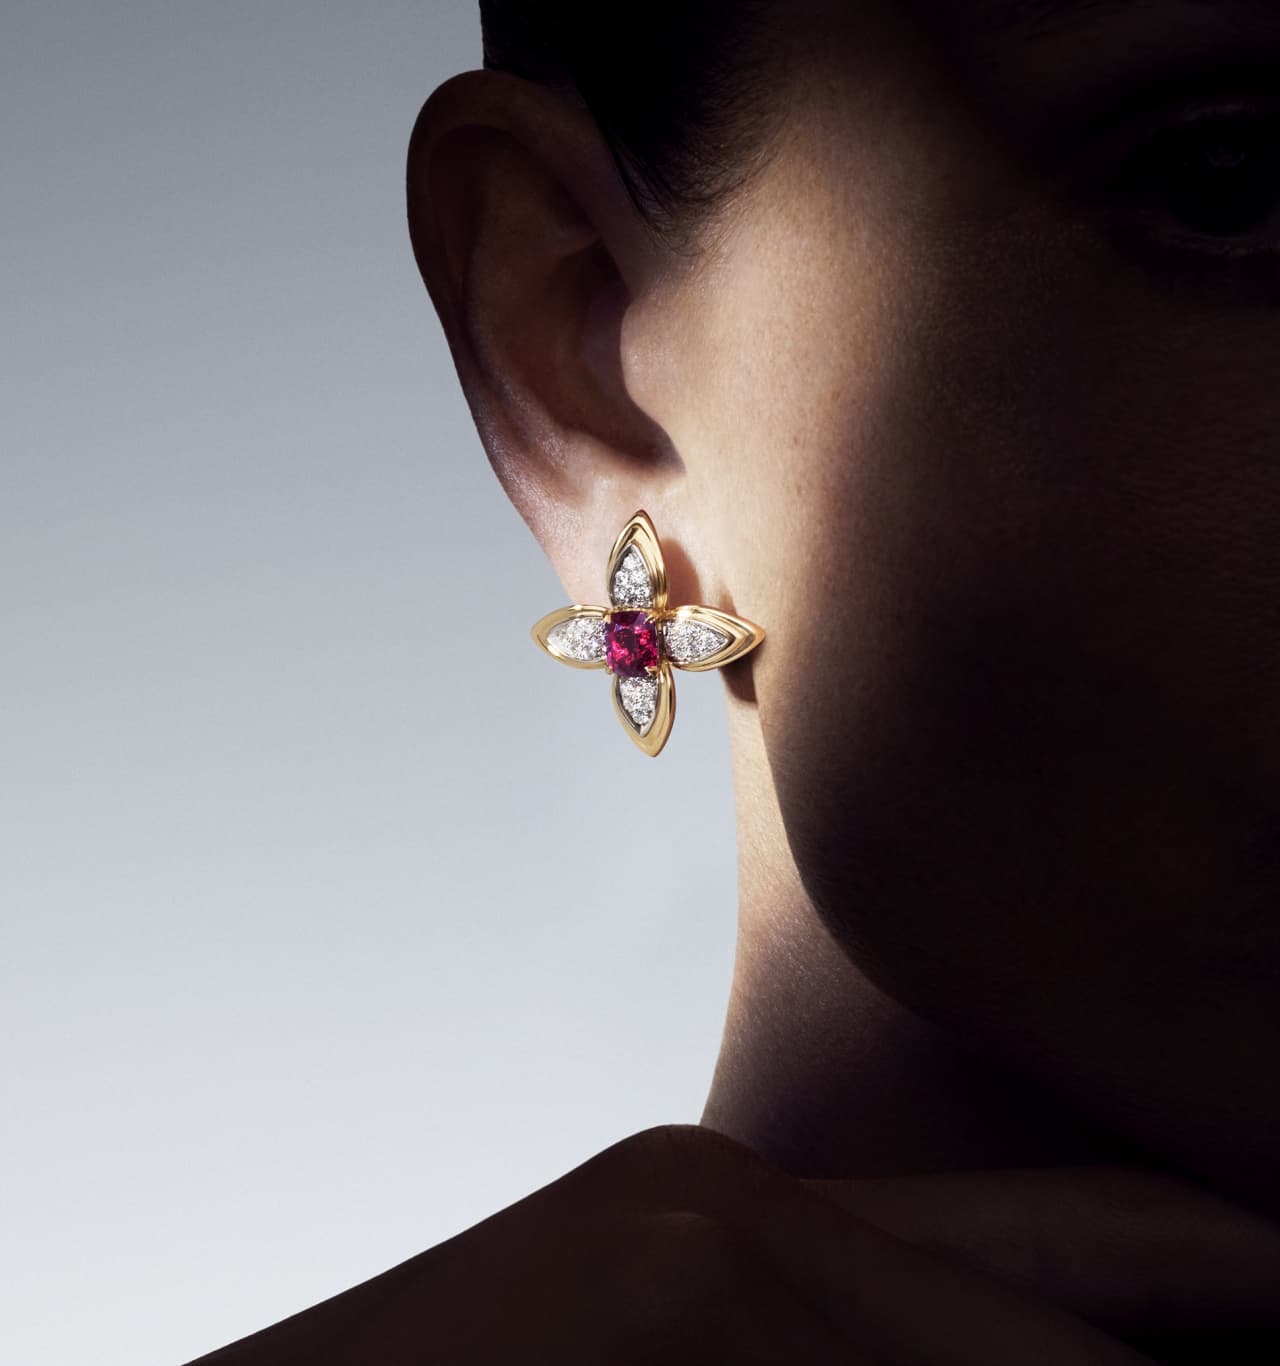
The necklace pays homage to the Eiffel Tower, which was unveiled to the world at the 1899 Exposition Universelle as a beacon of modernity and ingenuity. The Cœur de Paris offers a new perspective on the structure, as if you are viewing it from underneath looking up. Pink gold rods embrace a grid of baguette settings and diamond-lit arrows, which frame the jewel’s centrepiece: a captivating 56.23-carat diamond christened the Cœur de Paris. The collection’s rarest and most important master stone radiates a unique colour with an intense pink hue complemented with unusual tones of orange and brown. It is set in a medallion that can be detached to wear as a brooch.
The centrepiece dangles from a 5.73-carat LV Monogram Star-cut diamond interlinked with 26 LV Monogram Star-cut diamonds in an opulent rivière creation that is a first for the house. A companion ring features a complementary 12.67-carat, museum-quality diamond that emanates a fancy deep, brownish pink and orange hue.
“Awakened Hands, Awakened Minds tells a story that’s very close to who we are,” Amfitheatrof said. “By showing this mixture of craftsmanship, engineering, invention, and bravery, we are really talking about Louis Vuitton. … we couldn’t celebrate in a better way.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
