Crypto Mortgages Test Home Buyers’ Appetite in Digital-Currency World
Miami firms now offer home loans in crypto, but many traditional lenders doubt such practice will gain scale.
By
Deborah Acosta
Wed, Apr 13, 2022 10:45am 3 min
Some Miami developers have enabled buyers to purchase homes in cryptocurrency since at least 2021. Now a pair of Miami lenders is going one step further by offering home mortgages in digital currencies.
Milo, a fintech company in the lending business, made the first crypto home loan in March, when it provided a 30-year mortgage in bitcoin for a Miami duplex.
The firm says the early response among other crypto-oriented home buyers has been so enthusiastic that it is already looking to double the size of its Miami office to 100 employees to handle the anticipated demand.
XBTO, another cryptofinance company with offices in Miami, said it is also gearing up to offer crypto mortgages this year, in partnership with a traditional Miami-based mortgage lender.
“Between crypto millionaires who don’t want to sell their cryptocurrency and foreign buyers who have trouble entering the market, we see a huge demand,” says Joe Haggenmiller, head of markets for XBTO.
Kieran Gibbs is one of the newcomers to the city who has expressed interest. The professional soccer player from the U.K. moved to South Florida last year to play for the local Inter Miami CF. He said that he has been receiving half of his salary in bitcoin since January and that he is in talks with XBTO to secure a crypto mortgage.
“I’m renting my property at the moment and I’d like to buy,” Mr. Gibbs said. “The trouble is I haven’t been here for long enough to get enough credit, so it’s difficult for me at the moment to get a mortgage.”
Crypto mortgages are structured much like traditional mortgages and are lent out to home buyers in dollars but are meant to appeal to people who have large crypto holdings they don’t want to convert to dollars.
These mortgages require additional collateral in the form of a cryptocurrency, and the agreements allow the lender to take ownership of the home and the additional collateral in the event of default. If the value of crypto falls, the borrower may have to put up more crypto or other collateral.
Many traditional lenders are sceptical that loans in digital currency will ever gain scale, and analysts list numerous risks and complications when lending in crypto.
For one, they point to the legal pitfalls of engaging in a space that is still largely unregulated. Volatile fluctuations in the price of digital currencies could mean that lenders may require a borrower to put up additional collateral if the crypto price drops significantly.
“Anyone in the digital asset space should proceed with a great degree of caution,” says Richard Levin, an attorney and chair of the fintech and regulation practice at the law firm Nelson Mullins Riley & Scarborough LLP.
Even proponents of these loans say that the new companies are already encountering logistical issues.
“Integrating the legacy mortgage system with the new crypto environment is an operational nightmare,” says Lorenzo Delzoppo, an attorney who specializes in disruptive technology and who is consulting XBTO as they finalize their mortgage product.
Still, he adds, “It’s all incredibly exciting.”
Crypto mortgages are only the latest way that Miami businesses have experimented with the nexus of real estate and digital currencies, a trend that is on display this week during Miami’s bitcoin conference and other crypto-related gatherings.
Propy, a property-tech company whose chief executive resides in Miami, made headlines in February for being the first to process a U.S. real-estate transaction as a nonfungible token, or NFT.
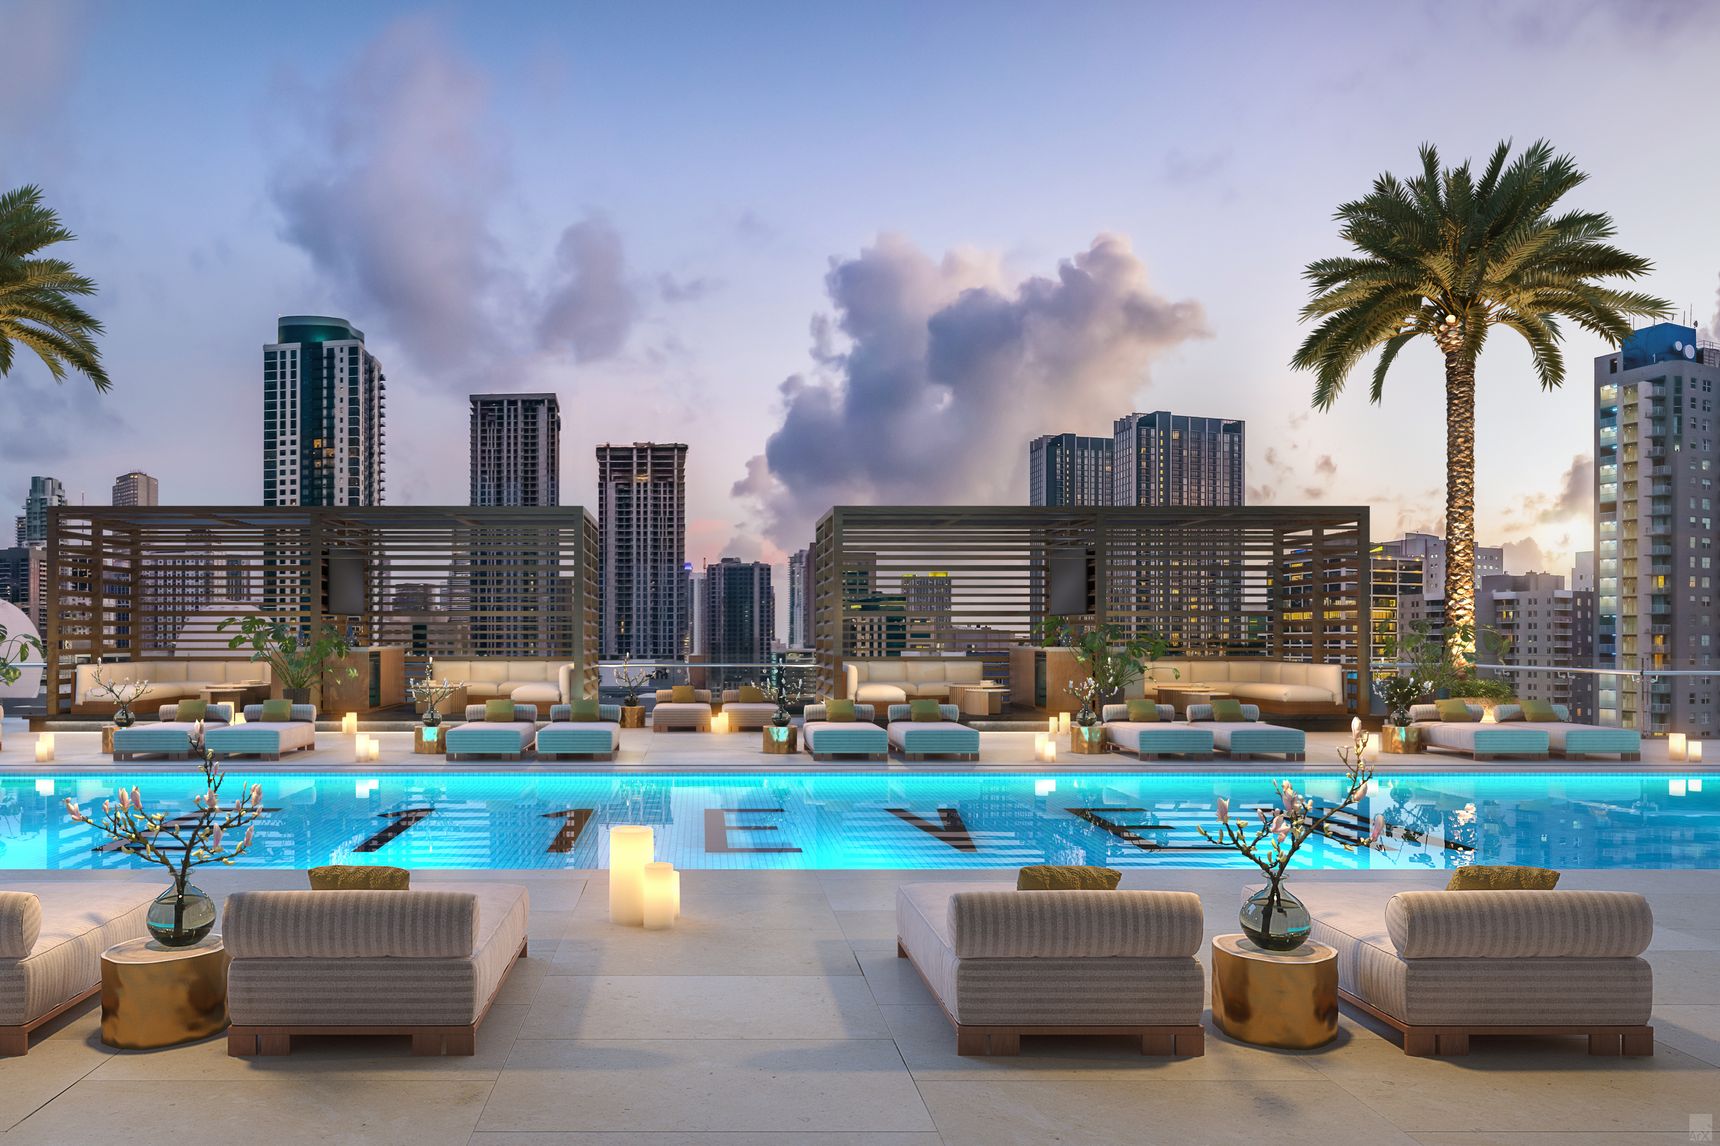
Real-estate developer PMG, in a partnership with the crypto-derivatives exchange FTX, said it has accepted more than $20 million in cryptocurrency payments toward preconstruction purchases of about 60 condo units at its E11even Hotel & Residences.
Lofty, a condo project in Miami’s Brickell district, is providing a digital NFT art piece as an amenity along with the purchase of a unit.
Milo, meanwhile, is offering interest rates for crypto mortgages between about 4% and 6%, which skew a bit higher than what banks tend to charge for dollar-based loans. The 30-year fixed-rate mortgage averaged 4.67% last week, according to mortgage-finance company Freddie Mac.
The crypto lender allows borrowers to take out loans of up to 100% of the purchase price by pledging their bitcoin as collateral. XBTO will require purchasers to put down 10%.
Reprinted by permission of The Wall Street Journal, Copyright 2021 Dow Jones & Company. Inc. All Rights Reserved Worldwide. Original date of publication: April 5, 2022.


 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.