EV Trade War Could Spread to Luxury Cars
Investors used to worry about an invasion of Chinese electric vehicles into Europe. Tit-for-tat tariffs would instead hit Porsches heading to China.
Europe’s politicians have no easy options for dealing with Chinese electric vehicles.
Slap a 100% tariff on them, as President Biden did last month , and China can easily retaliate against the more than 300,000 luxury cars it gets annually from the European Union. Let Chinese EVs into the EU with the current 10% tariff, though, and Chinese companies have an open road to take market share, given impressive technology and a roughly 30% cost advantage.
This week, the European Commission is expected to announce the results of a nine-month investigation into Chinese EV subsidies . Its most likely course of action is a cautious middle ground—a 25% to 30% tariff that would make European EVs broadly competitive with lower-cost Chinese imports. This could still trigger retaliation, but the EU’s executive body has to do something to protect an economically and strategically important industry.
This political reality only looms larger after this past weekend’s elections for the European Parliament, which rewarded right-wing populist parties in France and Germany. In the coming months a new European Commission will review the policy response to the EV investigation. Arguments for going easy on cheap Chinese EVs , because they help Europe’s climate goals, will presumably take a back seat to economic protectionism.
Just how much market share Chinese cars might take in Europe, at least in the short term, is debatable. After years of modest gains, they accounted for roughly one in 10 new EVs sold in Western Europe in the third quarter of 2023, according to Schmidt Automotive Research. But their share fell back in the final three months of the year, when France excluded China-made models from its subsidy program. High discounts on Chinese brands also point to stalling progress.
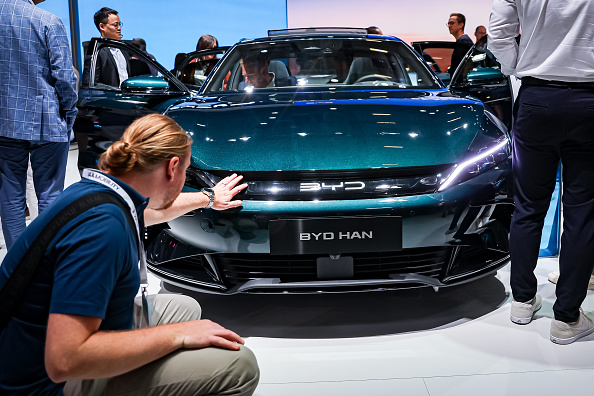
Many European consumers might not be ready for proudly Chinese brands such as BYD. The bestselling “Chinese” brand in Europe by far is MG, which is historically British but now belongs to China’s SAIC. Even it wasn’t one of April’s 10 bestselling EV models in the EU, according to data provider Jato Dynamics.
Many more Europeans would no doubt be converted to Chinese brands by the rock-bottom prices advertised domestically in China, which is in the throes of a vicious price war. But BYD launched its vehicles last year at surprisingly high prices, perhaps mindful of the EU’s investigation as well as the potential to juice its margins to compensate for a tough home market.
Still, the long-term threat posed by Chinese-made EVs in Europe is clear, and the EU won’t take any chances. One consequence of higher tariffs will be more local production. BYD is already building a factory in Hungary, while Volvo Cars will start producing its new EX30 in Belgium next year, rather than shipping it to Europe from China as it currently does. Tesla , which makes its Model 3 for Europe in its factory near Shanghai, will probably need to follow suit.
Other consequences will depend on China’s response. The China Chamber of Commerce to the EU said last month that Beijing was considering a 25% tax on imported cars with large engines. China’s current tariff on vehicle imports from the EU is 15%. This move would hit Porsche in particular as it makes about a quarter of its revenue in China and produces all its cars in Germany.
The irony is that investors previously assumed luxury cars were relatively insulated from the threat of Chinese EV imports. Last year, the market was instead worried about the competitive challenge to mass-market manufacturers such as France’s Renault . As politicians in Paris and Brussels responded, concerns shifted, contributing to a gaping divide in stock-market performance: Porsche’s stock is down 37% over one year while Renault’s is up 55%.
In the end, some kind of truce that keeps trade flowing is likely. The EU is more dependent on exports to China than the U.S., ruling out the kind of isolationism Washington is moving toward. That might be a reason to worry more about Renault again, though the French company appears to be making progress in cutting EV costs.
This points to the only sustainable European response to Chinese EVs: matching their technology and cost structure, at least as far as local differences allow. Higher tariffs can only buy a little time.
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
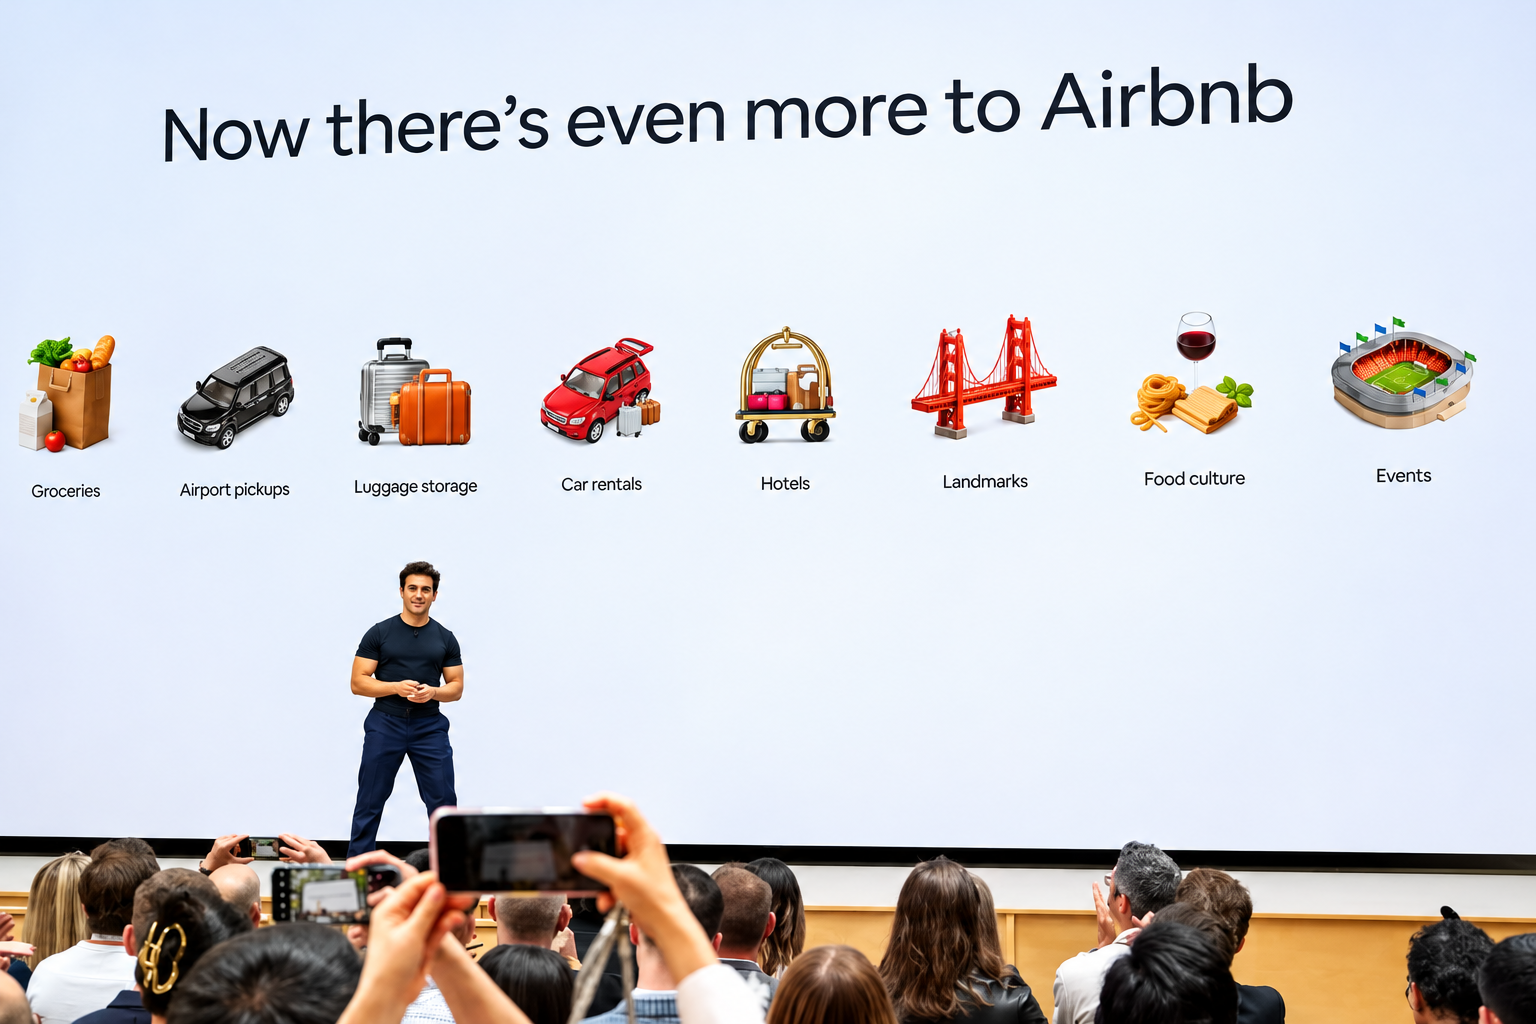
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.