MyTheresa Is E-Commerce for Luxury. The Stock Might Be the Cheapest Thing It Sells.
Mytheresa, based in Munich, went public in the U.S. in late January, raising about US$350 million for the company.
Bricks-and-mortar fashion boutiques have been in a tough spot during the pandemic. Small stores, after all, aren’t set up for social distance. Online retailer Mytheresa has been able to fill the void. The website caters to wealthy shoppers looking for help in finding their next designer handbag, pair of shoes, clothing item, or accessory.
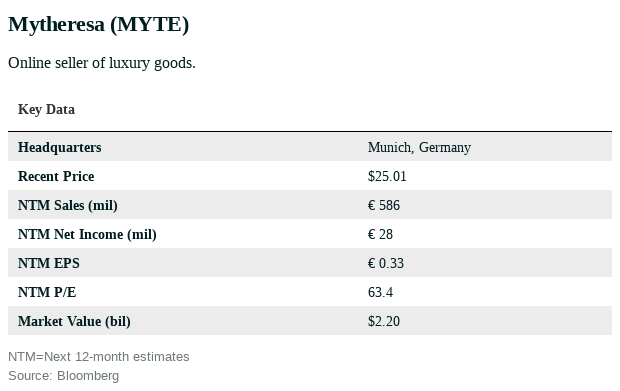
Mytheresa, based in Munich, went public in the U.S. in late January, raising about US$350 million for the company. The listing grew out of the bankruptcy of Neiman Marcus, which purchased Mytheresa in 2014. The small-cap has a market value of about $2.2 billion.
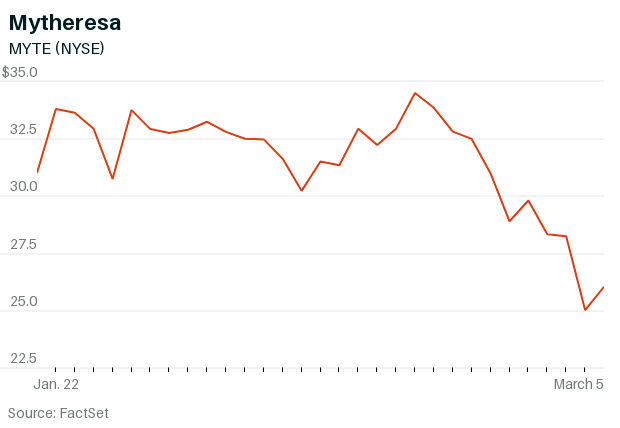
Mytheresa stock (ticker: MYTE)—technically an American depositary share of parent company MYT Netherlands Parent—was recently trading just below its $26 initial-public-offering price after having jumped to $36 shortly after the debut. The stock could recover those losses and more in the coming months.
“They are at the intersection of two higher-than-average growth trends in retail: luxury and e-commerce,” says J.P. Morgan analyst Matthew Boss.
Luxury buyers have been slower to adopt e-commerce. Before the Covid-19 pandemic, some 12% of global luxury sales happened online, compared with a 20% share of overall retail. The gap is closing. A recent study by consultancy Bain estimates that the share of luxury goods sold online could nearly triple to more than 30% by 2025.
Meanwhile, the overall luxury market is growing by about 7% annually.
The tailwinds put Mytheresa in an enviable position, and the company should get a further boost from its expansion in the U.S. and China, which are currently just 10% of sales each. (Europe was 60% in its latest fiscal year.) The company now has collections for men and kids, and it could expand into categories like jewellery and furniture in the future.
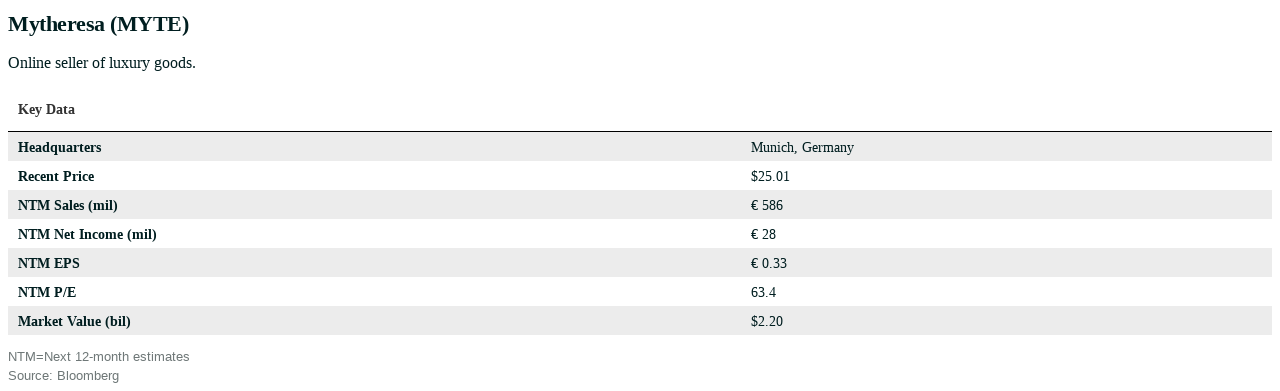
Mytheresa isn’t your typical money-losing tech start-up. The company, which reports in euros, earned €6.4 million ($9.9 million) in its latest fiscal year on €449 million in revenue.
Sales have grown an average of 22% over the past two fiscal years, while adjusted earnings before interest, taxes, depreciation, and amortization, or Ebitda, have grown at a 30% clip. For the fiscal year that ends in June, analysts are forecasting revenue growth of 25%, to €560 million. Analysts, who track adjusted earnings, expect the company to make €30.4 million this year, up about 60% from the adjusted figure last year.
“We are dealing with high-net-worth individuals who like to spend money—that’s a great customer base, and our core asset is this customer,” says Mytheresa CEO Michael Kliger.
The customer focus has helped the company earn a consistent profit, with a gross profit margin of about 45% and an adjusted Ebitda margin of about 8%. Other e-commerce players at Mytheresa’s early stage of growth have been years away from turning a profit.
If Amazon.com is the “Everything Store,” Mytheresa has taken the opposite approach. The site carries about 200 brands, fewer than luxury e-commerce rivals Farfetch (FTCH) or Richemont’s (CFRUY) Net-a-Porter. A recent search for “black dress” on Mytheresa’s U.S. site yielded just over 2,000 results, versus more than 7,000 at Farfetch.
Mytheresa’s most loyal shoppers get access to personal shoppers, styling and concierge services, and other perks like invitations to exclusive designer events and parties.
CEO Kliger says there’s a fine balance between presenting products in a way that’s helpful to shoppers and overwhelming them with an endless assortment. His company is focused on curation and more-abstract shopping desires, he tells Barron’s.
Customers looking for a specific Burberry coat, Chloé handbag, or pair of Gucci sneakers are better served buying directly from the designer.
Mytheresa’s website and app, now set up for spring and summer, are currently promoting multibrand compilations including “sandal season” and “talking-point pieces.”
The unique edit, to use the fashion-industry parlance, stands out to customers. Some 90% of Mytheresa customers surveyed by Cowen analyst Oliver Chen said they were likely to recommend the site to a friend, and 75% of them browse it weekly. Nearly 50% of Mytheresa’s customers spend at least $30,000 on luxury goods annually, the survey found.
Investors have been far more stingy when it comes to Mytheresa stock. The shares trade for 2.8 times this year’s estimated sales, versus 8.2 times for Farfetch and 4.5 times for The RealReal (REAL)—both of which are losing money.
Mytheresa could rally as investors reconsider that valuation gap. J.P. Morgan’s Boss has a price target of $38 on the stock, 50% above its recent close.
For now, Mytheresa stock is a luxury play at a bargain price. The sale is unlikely to last.
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Apple’s growth engine is showing signs of slowing, as rising costs, weaker services growth and AI competition challenge its profitability. With John Ternus taking the helm, the pressure is on to reignite innovation and sustain investor confidence.
The Apple growth and profit machine is wavering, and the boost from price increases might not be enough to keep it going at historic rates. That dials up the pressure on Apple’s new chief executive, John Ternus.
The company saved the bad news for its earnings call, an hour after it posted its results for the September quarter, projecting that for the current quarter its high-margin services business will continue to slow and that its widely watched gross profit margin will continue to fall.
Apple AAPL -1.83%decrease; down pointing triangle shares had been flat in post-close trading but declined as much as 4% after the company made the projections, which fell short of Wall Street estimates.
The impact of high memory costs are weighing even more heavily on the company, Ternus and Apple Chief Financial Officer Kevan Parekh said on the company’s earnings call. Apple has stockpiled cheaper components purchased earlier, but those inventories are dwindling.
When Ternus took over as Apple’s third chief executive of the past 29 years on Sept. 1, he inherited sky-high expectations. The men he followed were among the most successful company leaders in American business history. Steve Jobs revolutionized consumer devices multiple times. Tim Cook expanded Jobs’s creation to spectacular heights.
The expectations are reflected in Apple’s huge valuation. Oppenheimer analyst Martin Yang noted that Apple stock trades at 36 times next year’s expected earnings, a premium to the overall market, even though its earnings are only expected to grow 1%, which is slower than its tech peers.
“We see insufficient upside to justify the premium,” Yang wrote in an investor note, adding that Apple needs to boost iPhone sales growth and turn around its slowing services business to make him more bullish.
Investors have bid up Apple shares because it has been a port in the AI storm—a reliable and capital-efficient business that stands apart from rivals which are spending hundreds of billions of dollars racing to the AI frontier.
While others invest in data centers, Apple has been pouring its own cash into buybacks and dividends. But that safety may be challenged if Ternus can’t speed up Apple’s innovation engine.
Apple’s lagging performance in AI was evident when its new “Siri AI” chatbot arrived this past quarter. Its long-maligned assistant was already stale the day it arrived, surpassed by agents such as Instinct and Muse that can complete multistep tasks for consumers, while Siri still sets kitchen timers.
Apple needs to give people reasons to buy its devices as they get more expensive. The company raised prices across the board last quarter to help offset higher costs. Without compelling new features, a big question is whether consumers will slow the frequency of iPhone upgrades.
The new iPhone Duo appears to be a bright spot. Consumers are scooping up the $1,999 foldable smartphone despite mixed reviews—so many that Apple can’t keep up with demand. Shipping dates jumped out to January soon after the device went on sale, a disappointment for the normally reliable Apple supply chain.
Apple said its revenue grew 12% in the September quarter, slightly ahead of Wall Street’s expectations. Its widely tracked gross profit margin, at 47.9%, also came in just ahead of analyst estimates.
Apple will need to find new growth avenues because a reliable engine during the Cook era—the services business—is slowing. Courts and regulators worldwide have limited Apple’s ability to charge developers big fees to distribute apps through its App Store, the biggest component of the company’s services segment.
One of its most lucrative App Store fee generators has been the ChatGPT app from OpenAI. Around the time Apple accused OpenAI of trade-secret theft this past summer, OpenAI began redirecting potential subscribers to pay via its website instead of the App Store, skirting Apple’s tollbooth.
Apple’s valuation has bumped up against a ceiling in recent weeks. Six times it traded above a $5 trillion market capitalization intraday before finally closing above the threshold, which it has already fallen back below.
News Corp, owner of The Wall Street Journal, has a commercial agreement to supply news through Apple services.