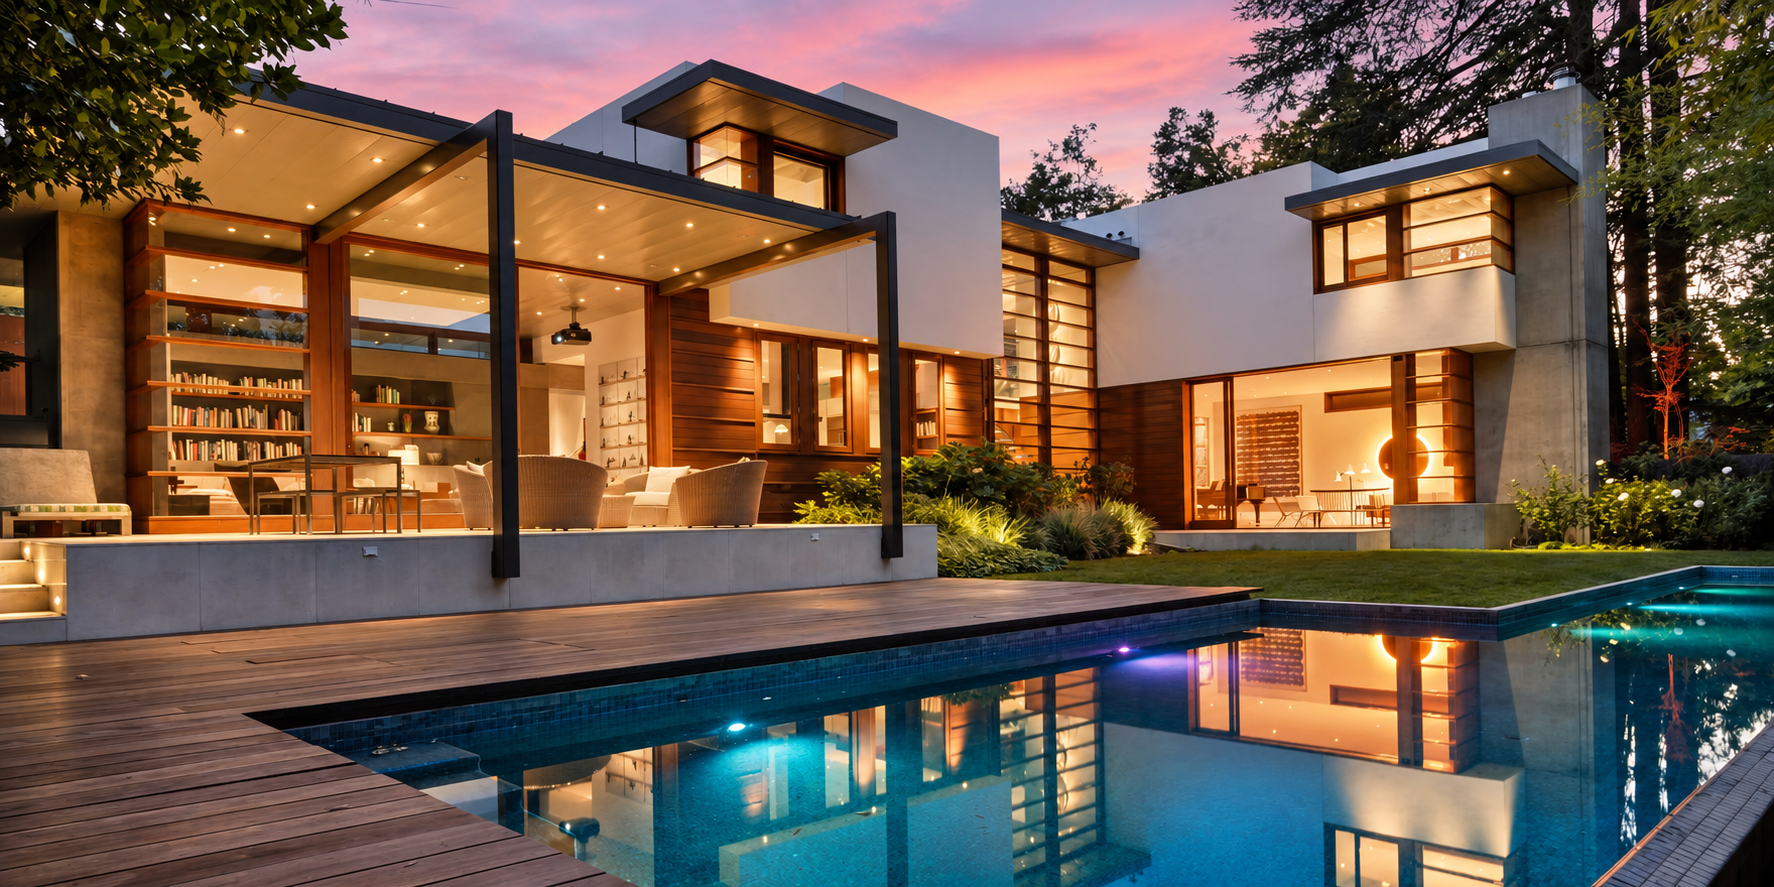
After three years of living in her dream home in a Texas community called Rocky Creek Ranch, Donna Rutter is giving it up to move closer to the accounting firm she bought in the nearby city of Fort Worth.
Rutter spent most of her 30-year career as a CPA for large firms in Dallas and Fort Worth. Even before Covid, she had a work style that allowed her some flexibility. She didn’t have a central office she went to every day, but she had clients she travelled to visit on site. That schedule allowed her to build a home in Rocky Creek, about 20 minutes from downtown Fort Worth.
Then the pandemic hit and she gave up travel and went fully remote. Now, with the pandemic-influenced lifestyle waning and the importance of being in the office growing, she has been drawn back into the workplace but for different reasons. In 2021, she bought her own firm, renamed Donna R Rutter CPA PC, and started working from her desk each week.
“Small businesses weren’t really set up to work remotely,” said Rutter, 59. “My clients want me in the office. They want to meet with me.”
The only problem, she said, was that her office is near central Fort Worth, making her commute about 45 minutes each way. She decided that is too long, and is moving closer to her new business. Her roughly 11-acre ranchette is now on the market for $1.75 million.
Rutter is just one of many homeowners making the decision to relocate closer to work.
According to a September report by Redfin, about 10% of home sellers in the U.S. are looking to move because of return-to-work policies, indicating that after more than three years of remote-work policies dominating behaviour in the housing market, the in-person, 9-to-5 lifestyle is picking up some steam. Average office attendance last week was 50.5% of the pre pandemic level in February 2020 across 10 major U.S. cities, including New York and San Francisco, according to Kastle, which tracks security-badge swipes into the buildings they secure.
In May and June, Redfin’s study surveyed more than 600 people across the country who were likely to sell and move within the next year, according to chief economist Daryl Fairweather. The findings follow more than a year of announcements from major corporations—including Apple, Walt Disney, Google and Tesla—calling remote employees back to the office.
In Seattle, local real-estate agent David Palmer of Redfin said that so far this year, he has received about 10% more inquiries than in 2022 from clients looking to relocate closer to the city because their jobs require a hybrid work schedule.
“I have a buyer who moved out of the city during the pandemic. He now works for Google and, long story short, he needs to commute three days a week and it’s about a two-hour commute each way,” he said. “So he’s actively looking to buy something.” Palmer’s client didn’t respond to a request for an interview.
Google has announced it will consider office attendance records in performance reviews, The Wall Street Journal reported in June. The company began calling employees back to the office a few days a week in April 2022.
Austin-based real-estate agent Matt Holm of Compass said that since Elon Musk called his employees back to the office, he has had several clients looking to move to the city to work for, or with, Tesla, where the company is headquartered. Last year, Musk told Tesla employees they are required to spend at least 40 hours a week in company offices, The Wall Street Journal reported. He sent the same message to employees of his rocket company, Space Exploration Technologies Corp., or SpaceX, which also operates in Texas.
Finding affordable housing in Austin for some of the incoming workers can be tough, Holm said. Those who can’t, often settle down in nearby markets, such as San Antonio and Killeen, because they are cheaper, he said. In October, the median sale price in the Austin metro area was about $444,000, down 6.5% from October 2022, Redfin said.
But for the employees who can afford Austin prices, Holm added, the demand has been a welcome boost to the housing market, which has seen slowed sales due to rising interest rates. On average, homes in the Austin metro area are sitting on the market for 63 days, Redfin stated, up from 53 days during the same period in 2022.
The sentiment around relocating for in-person attendance is mixed, Palmer said, “I have some clients who don’t mind, others who are a bit peeved.”
Rutter and her husband, Steve Lewis, 61, built their roughly 4,000-square-foot ranchette in late 2019. They outfitted it with vaulted ceilings, a heated saltwater pool, a dog shower and an outdoor kitchen, among other features.
While the home they have bought closer to the city is just 20 minutes from her office, it is about 1,000 square feet smaller and sits on about a third of an acre. She declined to disclose the purchase price. “We don’t have as much room,” she said, but added she is excited for a change and a shorter commute.
The couple’s ranchette is garnering interest from potential buyers, according to their listing agent, John Giordano of Compass. Rocky Creek Ranch is a desirable area because of the steady demand for ranchettes and because of its proximity to downtown Fort Worth, he said, adding that homes there rarely come up for sale.


 3 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.