
The Global House Price Boom Could Haunt The Recovery From Covid-19
Decreasing affordability raises both financial and political risks.

By Mike Bird
Mon, May 17, 2021 11:10am 3 min
3 min


Decreasing affordability raises both financial and political risks.
3 min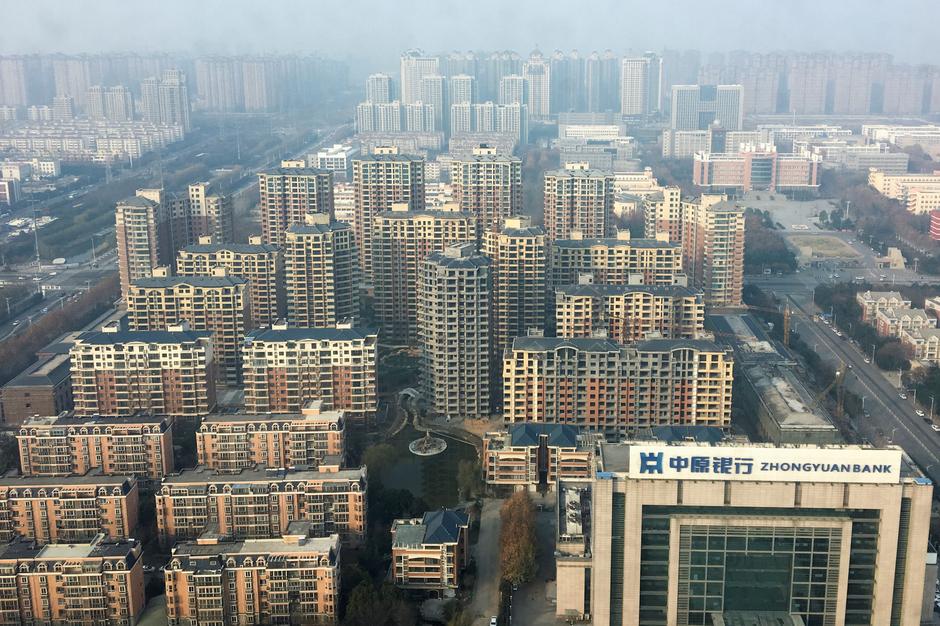
The year of the pandemic saw the largest increase in global house prices since the U.S. housing boom of the mid-2000s. And there is no sign the rally is coming to an end.
That provides immediate economic support for the global recovery from Covid-19. But a prolonged house price upswing would mean big new problems for both financial stability. And it could result in economic strife if middle-class citizens accustomed to a one-way housing bet suddenly find the rug pulled out from beneath them down the line.
House prices rose by 4.91% across 16 economies monitored by the Federal Reserve Bank of Dallas last year, the sharpest increase since 2006. The move was large by the standards of a normal year—but explosive in the context of a global economic contraction of around 3.3%.
And the trend shows little sign of abating. The U.S. housing market is millions of homes short of buyer demand. Prices have climbed in places as varied as the eurozone, South Korea, Australia, New Zealand and Canada.
Booming prices reflect a major difference between the liftoff from the financial crisis of 2008 and the nascent post-pandemic boom. The financial crisis emanated from a fragile, undercapitalized banking sector: The obvious postcrisis response was to lend much more conservatively. But at the beginning of last year, banks were far less overextended and, with greater government support, were much more rapidly able to pass on interest rate cuts to borrowers.
At the same time, banks are far more exposed to housing markets than they once were. Across 18 advanced economies, mortgage lending has grown from around a third of total bank lending in 1960 to very nearly 60%. The financial crisis seems to have only been a brief speed bump in this secular trend.
The experience of countries that didn’t have a major banking crisis in 2008 shows what could happen on a far larger scale now. Most countries with large run-ups in household debt during the last decade—China, South Korea, Thailand, Canada and Sweden—were places where banks didn’t suffer in 2008. And rather than the brief, one-off increase in leverage of the kind many analysts expect following the pandemic today, household borrowing climbed continually over the following decade.
Many such countries have attempted to slow down rapid increases in house prices. The Korean government has enacted dozens of individual tweaks to tax and lending regulations. The latest Canadian federal budget announced a tax on vacant and underused property owned by foreigners, following existing levies in Vancouver and Toronto. So far, few measures have had an impact large enough to stall the boom.
Earlier this year, Swedish central bank governor Stefan Ingves compared the household debt situation to sitting on a volcano. The analogy is apt, given how sensitive the health of economies is to increased leverage among households in particular. Economists Atif Mian, Amir Sufi and Emil Verner have published research demonstrating that burgeoning household debt tends to slow down economic growth.
That’s not to say there’s nothing to be done. There have been a small number of successes in controlling and preventing house price booms to note. They bear much closer examination for policy makers in the rest of the world.
Japan’s case is the most obvious. The country’s lack of zoning restrictions and rent controls are regularly credited with the country’s flat home prices, particularly in Tokyo where the total population is still increasing. All the same, making fair international comparisons is difficult because interest rates have been so much lower than other parts of the world for so much longer, and overall economic growth has been so weak.
According to a study published in the Journal of Housing Economics in 2018, Singapore’s flurry of efforts to cool house prices between 2009 and 2013 also seems to have helped to stall the country’s buoyant house price growth. The measures included higher taxes on home-flipping, higher deposit requirements for second-time buyers, longer residential loan terms, and caps on the amount of a borrower’s income that could be spent on home loan repayments. But Singapore is also an example of how difficult such progress is to defend: Prices jumped to a new record in the first quarter of the year. And Singapore’s market is unique in other respects—the lion’s share of housing is publicly developed for Singaporeans to purchase, and homeownership rates are among the highest in the world.
There are other areas to look at. Outright taxes on the value of houses, the land beneath them, or both are popular with economists but have yet to find their way into public policy in most parts of the world. Even without such radical steps, fixing other positive biases housing receives in tax systems around the world would be a good start.
Dealing with an asset that is a totemic symbol of middle-class security and the main source of household wealth but is also a major financial stability risk is an unenviable task for policy makers.
But with many parts of the world already in the foothills of a new house price boom, it’s an issue that must be considered urgently if they want to avoid the mistakes of the past.
Reprinted by permission of The Wall Street Journal, Copyright 2021 Dow Jones & Company. Inc. All Rights Reserved Worldwide. Original date of publication: May 8, 2021
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
More than 10,000 homes, an expansive central park and a mix of hospitality, retail and wellness facilities will form Azizi Developments’ first master-planned community in the emirate.
2 min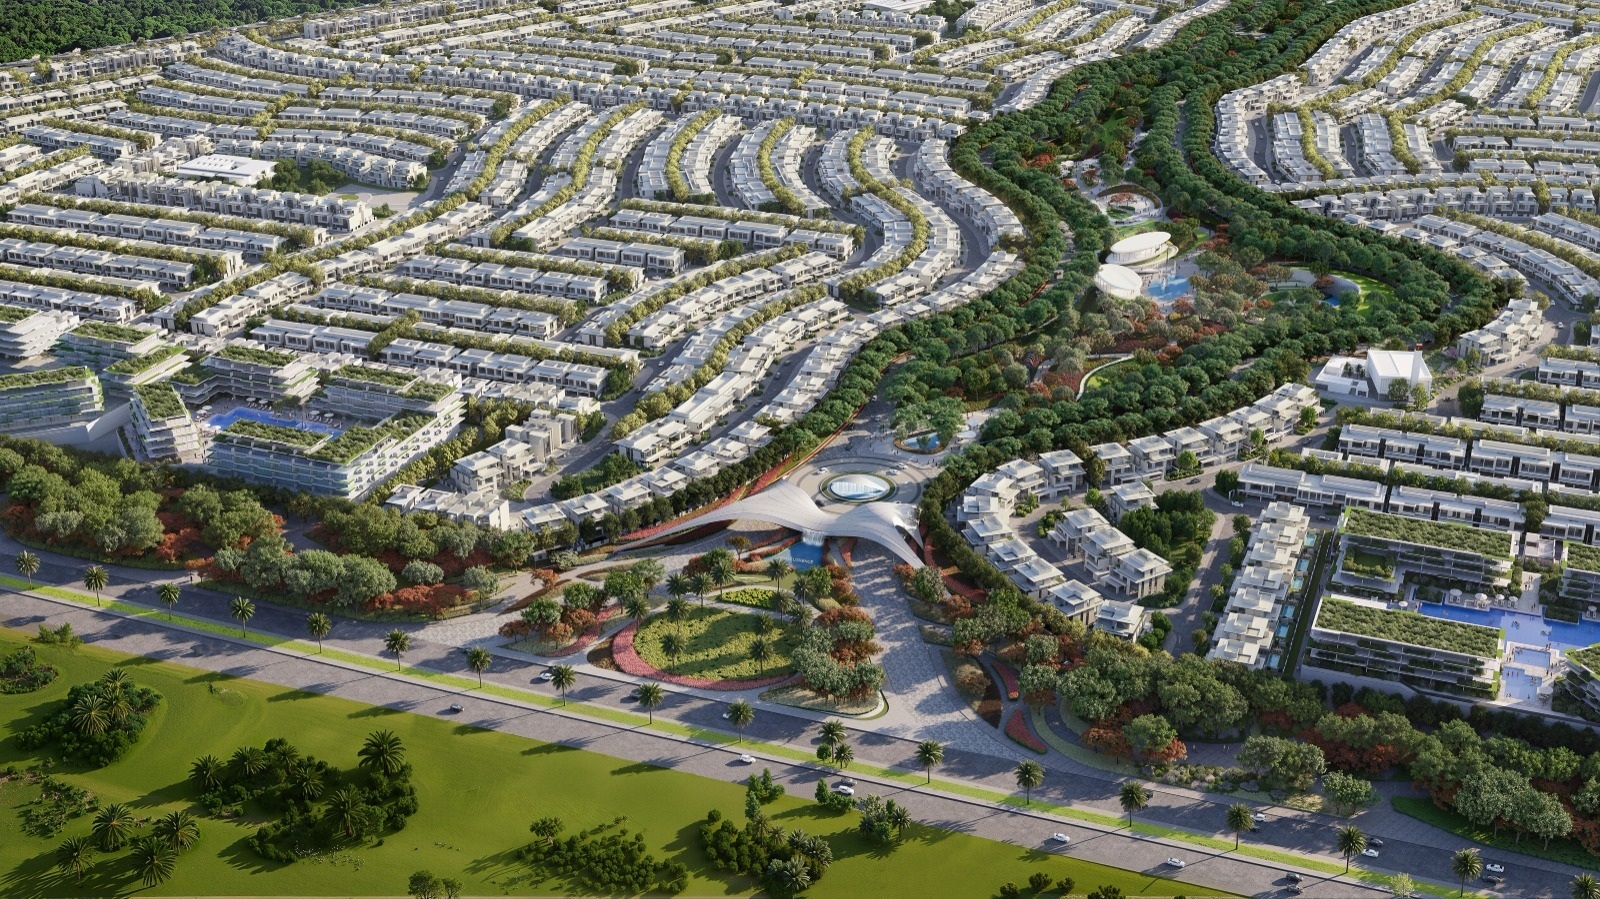
Sharjah is set to receive one of its largest new residential communities, with Azizi Developments unveiling plans for a US$8.1 billion master-planned precinct containing more than 10,000 homes.
Named Azizi Florence, the freehold development will comprise 1,130 villas, more than 6,000 townhouses and 3,500 apartments. Three-bedroom townhouses will start from US$515,000, with an indicative rate of US$231 per square foot of saleable space.
The project marks the Dubai-based developer’s first move into Sharjah, expanding a portfolio that includes the planned Burj Azizi skyscraper and the Azizi Venice community in Dubai.
Rather than treating landscaping as an afterthought, Azizi Florence will be organised around a 1.7 million sq ft central park.
The wider precinct is planned as a self-contained neighbourhood combining homes with retail, hospitality, education, leisure and wellness facilities.
Six residential clusters will sit within the development, each with its own park, clubhouse, community centre and landscaped gardens. The approach reflects a broader shift across large Middle Eastern developments, where greenery, recreation and everyday convenience are increasingly central to the residential proposition.
The scale of Azizi Florence suggests it is intended to function as a neighbourhood rather than a collection of housing estates. Its mix of housing types should also give the project broader appeal, accommodating apartment buyers alongside families seeking townhouses or standalone villas.
Azizi Developments has delivered more than 45,000 homes to buyers from over 100 countries and says it has approximately 150,000 units under construction.
Much of its growth has been concentrated in Dubai, where its portfolio extends across Palm Jumeirah, Mohammed Bin Rashid City, Dubai South, Sheikh Zayed Road and Downtown Jebel Ali.
Its most prominent current project is Burj Azizi, which is intended to become the world’s second-tallest building. Azizi Florence represents a different type of undertaking: a low-rise, family-oriented community built around public space and daily amenity.
For company founder and chairman Mirwais Azizi, the Sharjah project also carries a personal connection. The emirate was his first home in the UAE more than three decades ago, adding a symbolic dimension to the developer’s expansion.
Although Dubai and Abu Dhabi have traditionally captured much of the international attention directed at the UAE property market, Sharjah has been steadily broadening its residential offering.
Large freehold communities such as Azizi Florence have the potential to attract both local families and international purchasers looking for comparatively accessible entry points into the Emirates’ property market.
At a starting price of US$515,000, the project’s three-bedroom townhouses will sit well below the cost of equivalent family homes in many of Dubai’s more established luxury communities.
The ultimate appeal, however, will depend on execution. At this scale, the quality of the public realm, connections between residential clusters and delivery of the promised supporting infrastructure will be as important as the homes themselves.
If those elements come together, Azizi Florence could help establish a new benchmark for large-scale residential development in Sharjah—and give buyers another option beyond the UAE’s better-known property markets.
