
The Real-Estate Downturn Comes for America’s Premier Office Towers
Rents at highest-end buildings fall and rate of leasing slows

By PETER GRANT
Wed, Jan 31, 2024 10:33am 3 min
3 min


Rents at highest-end buildings fall and rate of leasing slows
3 min
The highest quality office buildings have had much better success navigating the industry’s turmoil. Now, even premier towers are starting to wobble.
Rents at the highest-end buildings have been falling, while the rate of leasing has been slowing. Tenants have become more sensitive to costs in a world of higher interest rates and lingering concerns about a possible economic slowdown, market participants say.
Owners of the most elite buildings escaped this fate for a while by convincing the market they had created a new class of office tower—one that surpassed the traditional Class A building at the top of the pecking order.
These landlords persuaded blue-chip tenants that reluctant workers would return if only their offices sparkled with lush roof decks, fully loaded gyms and food prepared by Michelin-starred chefs. Owners invested heavily in these properties, which were usually new developments with the best locations, views, air quality and modern designs.
But that strategy is losing steam as more companies have accepted the reality of hybrid work schedules and, for the most part, have given up on compelling workers to be in five days a week.
“The ship has sailed on full return to the office for most companies,” said Rob Sadow, chief executive of Scoop Technologies, a software firm that developed an index that tracks workplace strategies. “They’re not going to go from three days a week to five days a week by making their space nicer.”
That is one reason why few office developers are considering new ground breakings. Current rents don’t pencil out for building expensive space. The U.S. had only 31 million square feet in office construction starts last year, the lowest level since 2010. New buildings will represent only 1% of inventory by 2027, the lowest in at least 25 years, according to CoStar.
“New starts have essentially ground to a halt,” said Dylan Burzinski, analyst at real-estate analytics firm Green Street.
Premium, amenity-rich office space has outperformed in terms of rent and occupancy throughout the pandemic. In New York, SL Green Realty opened a new office tower called One Vanderbilt across the street from Grand Central Terminal in the fall of 2020. It boasted a 4,000-square-foot terrace and cafe and a menu overseen by star chef Daniel Boulud. The 93-story building quickly filled up even though its top asking rents were near record levels at more than $300 a square foot.
That sort of exceptionalism is beginning to wane. Asking rents for prime space in 16 U.S. markets declined in the third quarter after increasing on average from about $61 a square foot in mid-2021 to close to about $70 in the second quarter of last year, according to CBRE Econometric Advisors. They were just under $69 in the fourth quarter, CBRE said.
The share of leasing activity is also falling among the premier towers. The office properties that data firm CoStar Group defines as five-star buildings accounted for 8% of the market in 2022 and 2023, down from 10% in 2019. Meanwhile, new leases in five-star buildings were on average 43% smaller than 2019, CoStar said, reflecting how companies are becoming more efficient in their space use and tolerating some degree of work from home.
In the fourth quarter, 62% of companies offered some form of remote work, up from 51% one year ago, according to Scoop. On average, those companies with hybrid strategies required workers in the office 2.5 days a week in October, Scoop said. In 2021 and 2022, many companies still expected to bring workers back five days a week and were leasing space with that in mind.
Office buildings that have opened recently have done well, but not by One Vanderbilt’s standards. In Boston, for example, Millennium Partners has leased about 60% of the 812,000 square feet of office space that hit the market last year in the new Winthrop Center project with such tenants as Cambridge Associates and consulting giant McKinsey. But rents are about 10% less than what Millennium originally forecast, said Joe Larkin, principal of MP Boston, the developer’s local arm.
Larkin said that Millennium expects to achieve its goal of taking three years to lease the building. “What we lost in the last couple of years is the hope to exceed how we planned this building,” he said.
High interest rates and concerns about a possible recession are also giving companies second thoughts about trading up to higher quality spaces. Moves are expensive especially when borrowing costs are higher than they’ve been in decades.
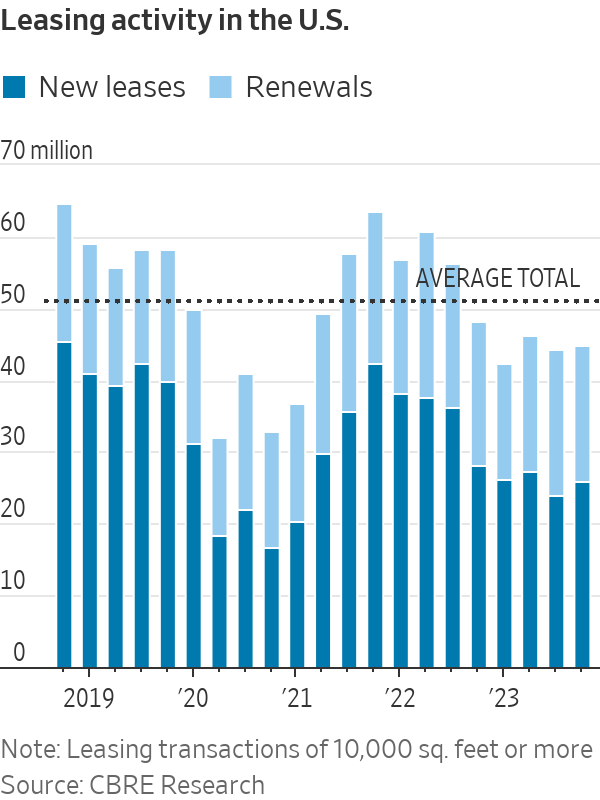
Cost-conscious companies are noticing that the gap between asking rents in top buildings and lower quality buildings is widening. The result: Renewals were 42% of the leasing volume last year, compared with 31% in 2018 and 2019 combined, according to CBRE.
“If companies aren’t going to have people in the office full time, maybe taking the lower-grade space might be a better economic decision,” Sadow said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
A five-bedroom Palo Alto home designed by Steven Ehrlich is listed for $44 million, making it the city’s most expensive listing. Built around a dramatic concrete spine, the home features four courtyards and a pool.
3 min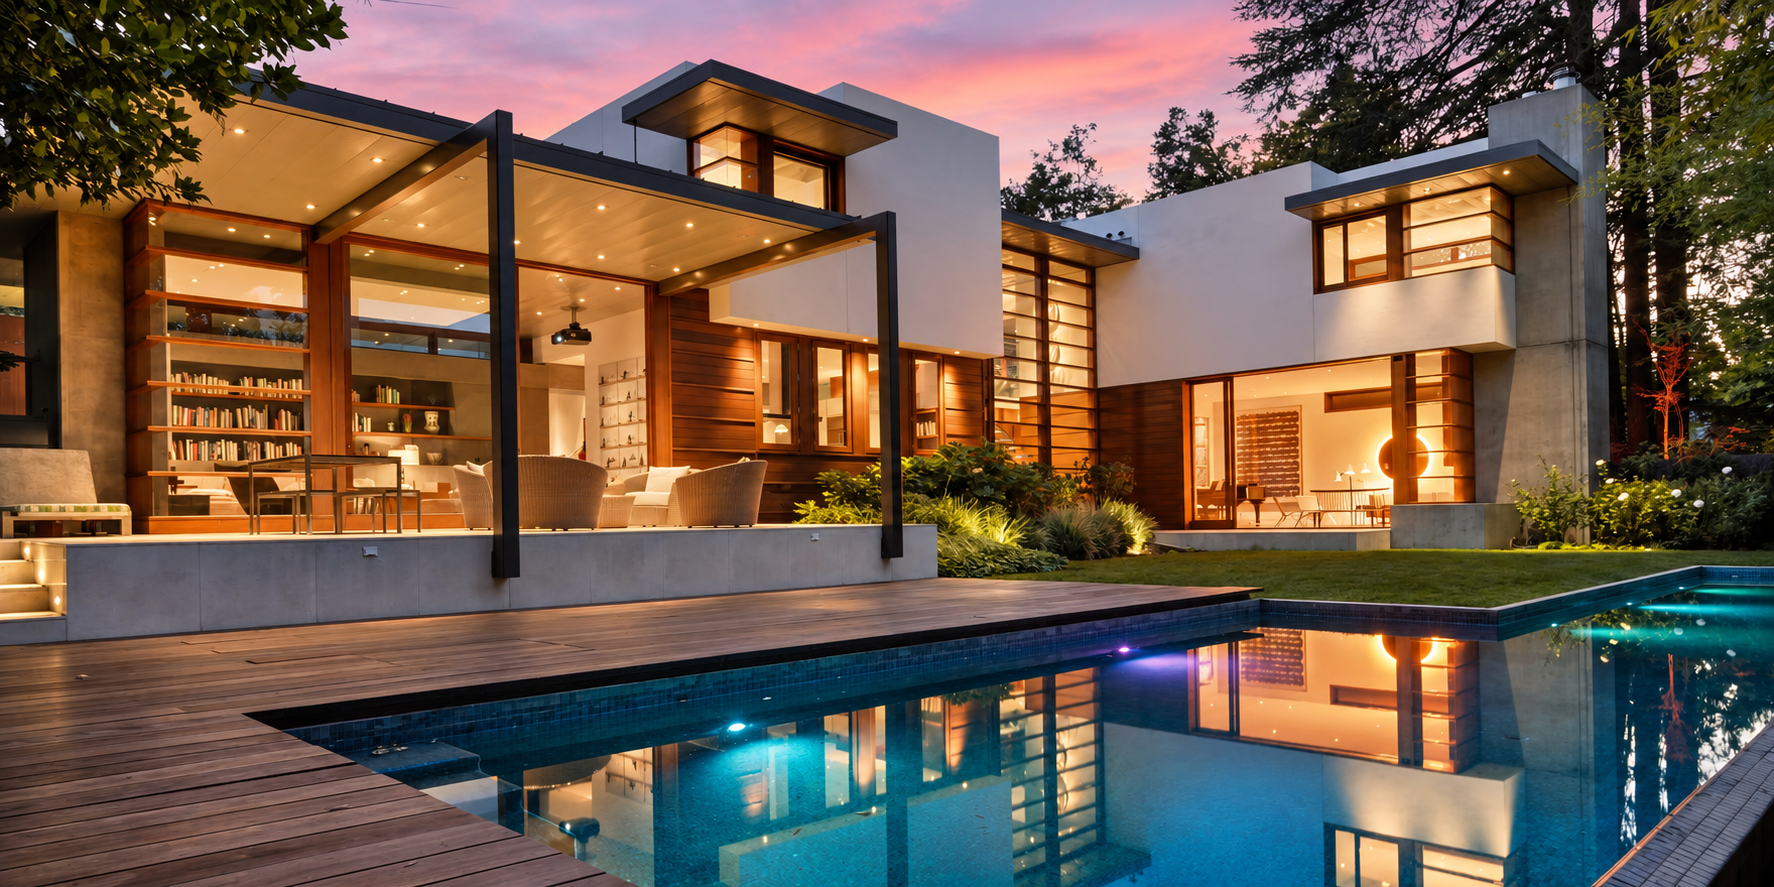
For years, tech entrepreneur Asher Waldfogel and his wife, Helyn MacLean, dreamed of building a modern house in Palo Alto, Calif.
The couple, however, worried about clashing with the Mediterranean-style architecture typically associated with their neighborhood of Old Palo Alto.
So they tapped architect Steven Ehrlich to create a design that paid homage to its surroundings with stucco, mahogany and titanium zinc cladding. They spent $20 million over several years building the house, completed in 2005.
Now looking to be closer to their adult daughter on the East Coast, they are putting the five-bedroom home on the market for $44 million—the most expensive listing in Palo Alto.
Waldfogel is an angel investor who co-founded Redback Networks, a telecommunications-equipment company. MacLean previously had a career in fundraising.
The couple purchased the roughly 0.4-acre site for $7.1 million in 2000 and demolished a circa-1930s Spanish Colonial home. The house they built pinwheels around a central staircase. It has 7,900 square feet of livable space, with four distinct courtyards and a pool.
A key feature of the home is a cast-in-place concrete wall, or spine, that is two stories high and about 80 feet long. “There’s a little bit of controlled chaos in what comes out of the form,” unlike a perfectly uniform surface, Waldfogel said. “If you want that, you do it in plastic.”
Waldfogel said he and his wife are thinking about the next phase of life now that their daughter is grown, although they have not decided where they will move. They also have a home in Sun Valley, Idaho.
“Right now we’re just trying to emotionally let go and decide what to do next,” he said.
Palo Alto, an epicenter of venture capital and tech startups in Silicon Valley, is home to some of the country’s biggest tech titans. Sales volume and prices are rising, with a median sale price of $3.5 million for the three months ending in August, up 5.8% year-over-year, according to real-estate brokerage Redfin.
Arthur Sharif of Sotheby’s International Realty—San Francisco Brokerage has the listing.


