
Green Investors Were Crushed. Now It’s Time to Make Money.
The lessons have been hard, and are a reminder of the basic facts of investing

By JAMES MACKINTOSH
Wed, Dec 6, 2023 9:34am 3 min
3 min


The lessons have been hard, and are a reminder of the basic facts of investing
3 min
Invest according to your political views, and you’re unlikely to make money. Companies that appeal to left-wingers or to right-wingers might be good or bad investments, but the fact of being, on current politics, clean and union-friendly for the left or oily and gun-friendly for the right is neither here nor there. What matters is their ability to make money and how highly they are valued.
This has been rammed home for environmentally-minded investors in the past year, as a coordinated selloff in anything with green credentials crushed the idea of making money while doing good.
It turns out that the real world is tougher than advocates of ESG—environmental, social and governance—investing claimed. The lessons have been hard, but should remind investors in the sector of some of the basic facts of investing. The fall in prices has improved the outlook for the stocks.
This year has been almost universally bad for clean investments. The two worst performers still in the S&P 500 are solar companies Enphase Energy and SolarEdge Technologies, down 60% and 70%, respectively. Hydrogen stocks have fallen sharply, led by Plug Power, which warned it might not survive. Wind-farm developers have been doing so badly they have pulled out of some contracts, with Denmark’s Ørsted off 48% in dollar terms and Florida-based NextEra Energy off 29%.
Electric cars have disappointed too, hitting startups and suppliers and pushing the price of lithium ores, used to produce the battery metal, down by three-quarters or more, although market-leader Tesla’s stock has been an exception.
Just as there was a coordinated green selloff, there has been a coordinated partial rebound in the past month or so.
This provides the first lesson: debt. The clean-energy sector is dependent on vast amounts of borrowing, so high interest rates really hurt. Roman Boner, who runs a clean-energy fund at Dutch fund manager Robeco, points out that major projects are typically financed with 80% debt, so rises in financing costs have a big impact on competitiveness.
Investors who bought into green stocks probably didn’t think they were making a leveraged bet on Treasurys, but that is what they ended up with. It isn’t only about corporate financing costs, either. High borrowing costs hit consumer demand for rooftop solar and for electric cars, both of which are often leased, since leasing costs depend on the cost of debt.
At a very high level, this is about long-term thinking. Low rates encourage investors to think long term, because they make future profits almost as valuable as current profits, and encourage borrowing to try to secure those future profits.
High rates encourage short-term thinking, by making profits today far more valuable than future profits—why bet on the future when you can earn 5% from Treasury bills? Short-term we get fossil-fuel profits, while long-term we get either clean energy or global warming; recently investors have been encouraged by rising rates to think short term.
The second lesson: government. Ronald Reagan overstated it when he said: “The nine most terrifying words in the English language are: ‘I’m from the government, and I’m here to help.’” But investors who rely on state subsidies to ensure profits leave themselves at the mercy of both fickle politicians and the bureaucrats Reagan was concerned about. This year’s selloff has been worsened by the bureaucrats and their failure to provide the details of many of the subsidies promised in last year’s badly named Inflation Reduction Act.
“We’re still hoping to get them by year end,” says Ed Lees, co-head of the environmental strategies group at BNP Paribas Asset Management. The next problem might be the politicians, at least if Donald Trump wins the presidency and torches the IRA. Lees thinks this will be hard, because so many IRA-subsidised projects are heading for Republican states. But Trump certainly has no sympathy for environmental causes.
The third lesson is the one most relevant to buying today: valuation. Buying stocks when they are trendy and wildly overpriced is a recipe for disaster. Perhaps the most extreme example of late is the L&G Hydrogen Economy ETF, launched in London at the height of clean-energy excitement in February 2021. It plummeted from day one, never regained its launch price, and is down 55% since then.
“We’ve seen a very harsh reality check,” said Sonja Laud, chief investment officer of L&G Investment Management.
The question is whether the hype has left. Laud worries that one year of high rates won’t have crushed all the excesses built up in 12 years of near-zero rates. But clearly valuations are much lower than they were, and she is hopeful there are opportunities to be found now.
“The huge green premium you had previously is no longer there,” says Velislava Dimitrova, who runs sustainable funds at Fidelity International. Clean-energy stocks are “much more interesting than they used to be—I don’t believe that renewables are dead.”
In the bond market, investors are no longer paying much if any “greenium,” or extra price for green bonds. In stocks, it is harder to judge: The S&P Global Clean Energy index trades at a discount to the global market on some measures, but not others, making it difficult to conclude that the sector as a whole is a wonderful bargain.
Still, it is good news for buyers that the hype has evaporated. Investors who care about profits more than purpose can finally consider clean-energy stocks again.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
3 min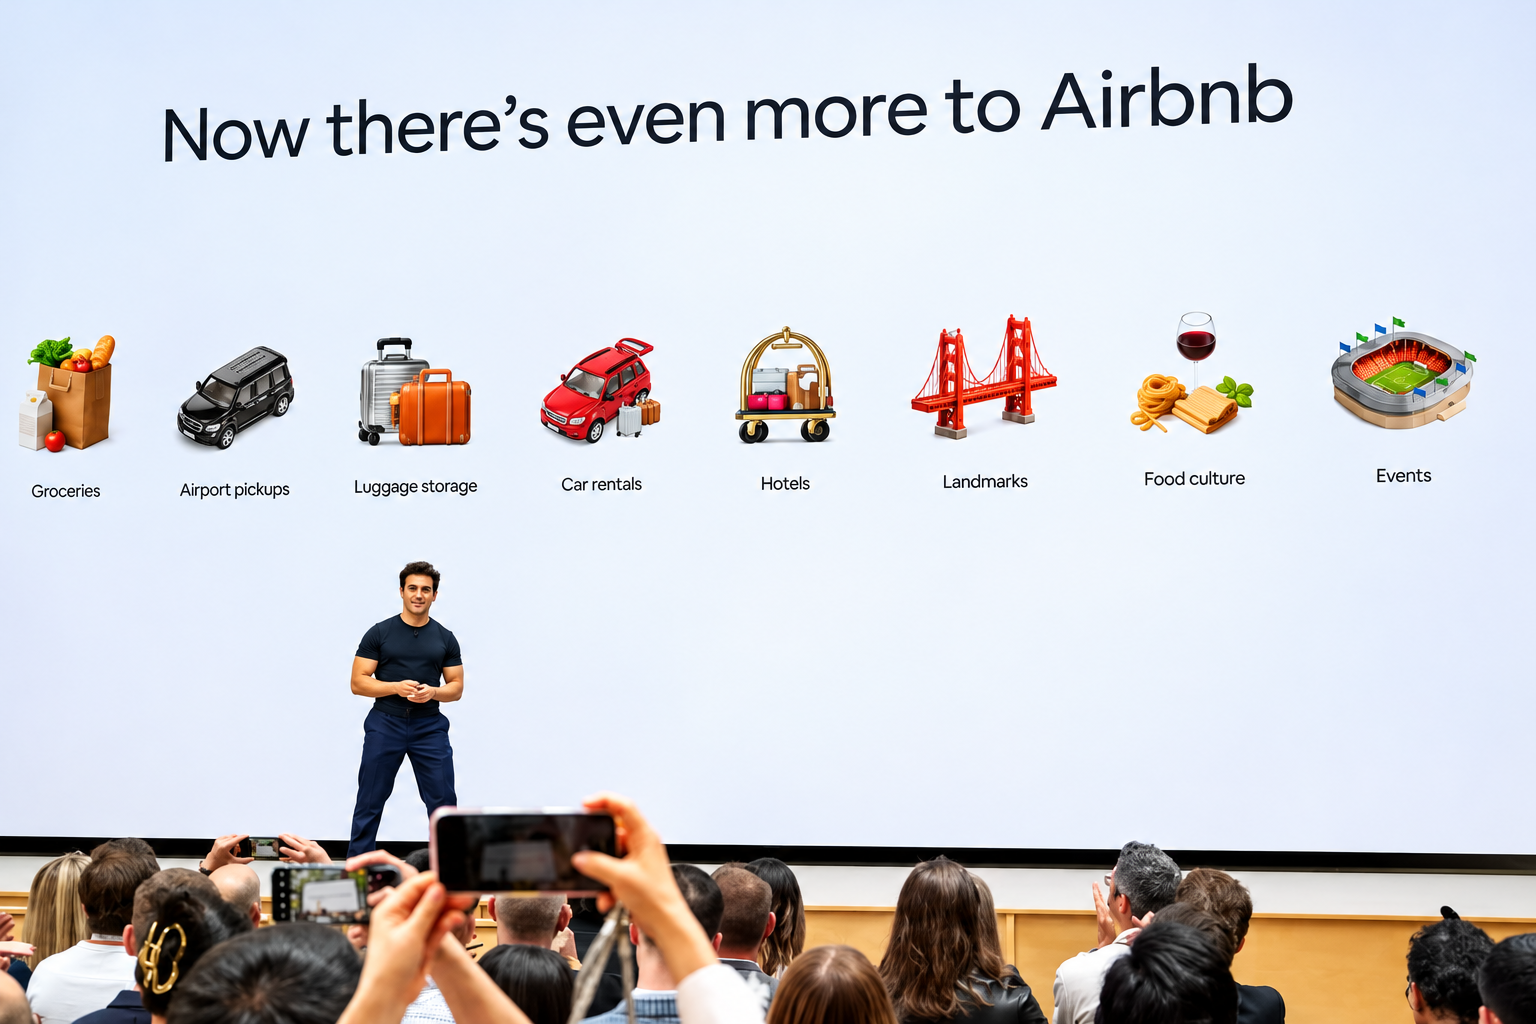
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.
