
China’s Wobbles Could Throw the Global Economy Off Its Axis

By DESMOND LACHMAN
Tue, Jan 30, 2024 11:31am 3 min
3 min

 3 min
About the author: Desmond Lachman is a senior fellow at the American Enterprise Institute. He was previously a deputy director in the International Monetary Fund’s Policy Development and Review Department and the chief emerging market economic strategist at Salomon Smith Barney.
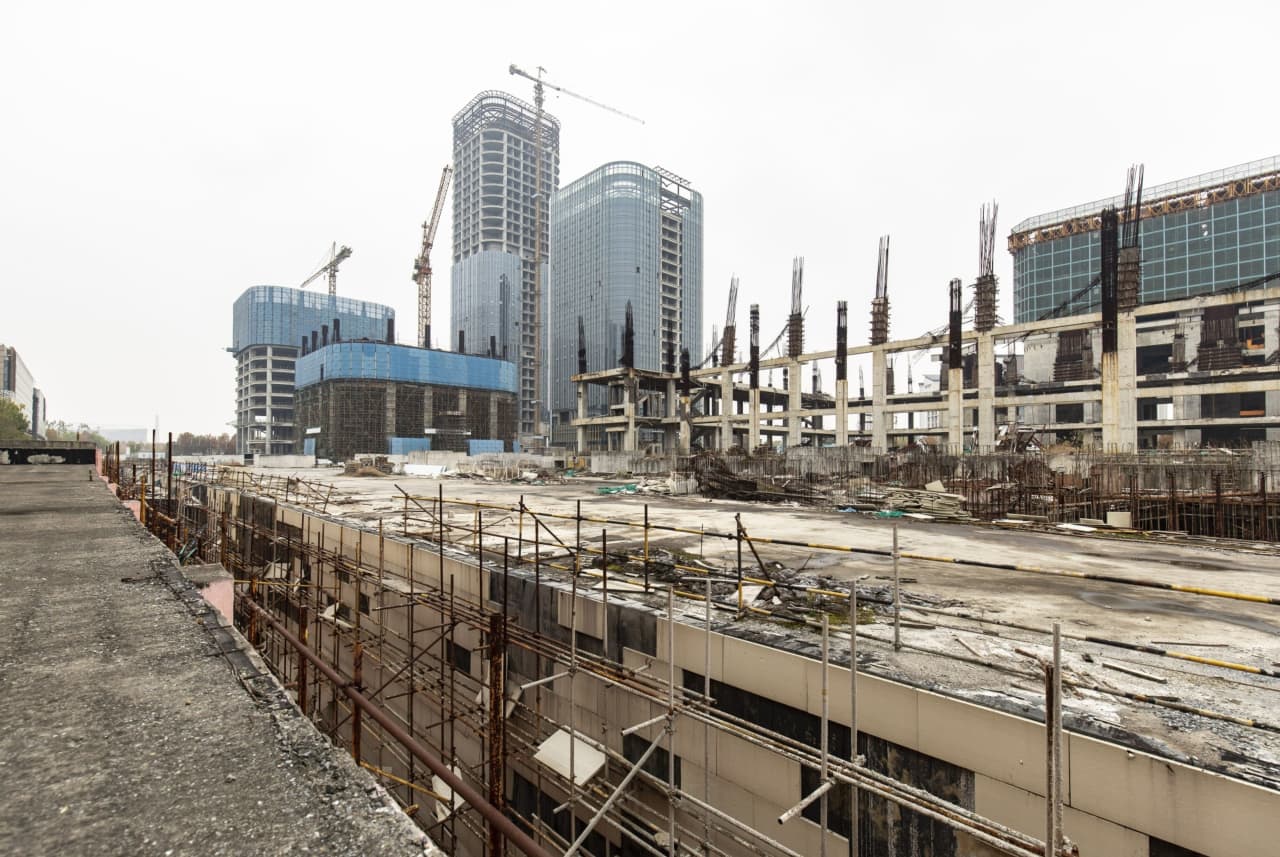
Today, a Hong Kong court ordered the liquidation of Evergrande, a Chinese company that was one of the world’s largest property developers. After years of fruitless negotiations between the company and its creditors over the restructuring of its $300 billion debt mountain, a Chinese court said that “enough was enough.” In a blow to an already troubled Chinese housing market, it ordered that the company’s assets be liquidated to pay back its creditors.
How mainland China handles Hong Kong’s court order could have major implications for Chinese property prices and foreign investor confidence. If it enforces the court’s order, that could see an acceleration in Chinese home-price declines by adding to supply in an already glutted market. It could also heighten social tensions by disappointing around 1.5 million Chinese households who have put down large deposits for homes that are yet to be completed.
If it ignores the Hong Kong court’s order, it risks dealing a further blow to waning investor confidence. Questions would arise about China’s willingness to abide by the rule of law and to offer a safe economic environment for investors.
The Evergrande liquidation comes at an awkward time for the Chinese economy. It is already in deep trouble and could be headed for a Japanese-style lost economic decade. The news also suggests that China will disappoint the consensus view that the Chinese economy is headed for only a minor economic slowdown this year. This could have major implications for the U.S. and world economic outlook, considering that China is the world’s second-largest economy and until recently was its main engine of economic growth.
Even before Evergrande’s liquidation order, a whole set of indicators suggested that the former Chinese economic growth model was dead. Chinese home prices have been falling for more than a year; both wholesale and consumer prices have been falling; stock prices have plummeted as foreign investors have taken fright; and youth unemployment has risen to around 20%.
There have also been questions about President Xi Jinping’s economic stewardship. First, his disastrous zero-tolerance Covid policy contributed to the country’s slowest economic growth in 30 years. Now his increased economic intervention is undermining the underpinnings of the Chinese economic growth miracle unleashed by Deng Xiaoping’s economic reforms in the 1980s.
Chinese stocks rose last week on news that authorities are taking steps to stimulate the economy. But anyone thinking that the Chinese economy will respond favorably to yet another round of policy stimulus has not been paying attention to the size of that country’s housing and credit market bubble that has now burst. Nor have they been paying attention to the troubling degree to which that country’s economy has become unbalanced.
According to Harvard’s Ken Rogoff, the Chinese property market now accounts for almost 30% of that country’s GDP. That is around 50% more than that in most developed economies. Meanwhile, over the past decade Chinese credit to its non financial private sector expanded by 100% of GDP, according to the Bank for International Settlements. That is a larger rate of credit expansion than that which preceded Japan’s lost economic decade in the 1990s and that which preceded the 2008 bursting of the U.S. subprime and housing market.
The overall Chinese economy is highly unbalanced in the sense that it has become overly reliant on investment demand. The Chinese investment-to-GDP ratio is over 40%, according to the Organization for Economic Cooperation and Development. That’s sharply higher than the more normal 25% ratio in most other developed and mid-sized emerging market economies.
The consensus forecast is that Chinese economic growth this year will continue at a 5% clip. Anyone relying on that forecast should reflect on the many failures by the U.S. Federal Reserve and other central bankers to foresee the grave problems of the subprime housing market in the U.S. in early 2008. It would seem that most economists are downplaying indications of major Chinese economic problems that are plain sight. Chinese economic problems could unleash serious deflationary forces for the U.S. and global economy. The Federal Reserve would be ignoring them at its peril.
Guest commentaries like this one are written by authors outside the Barron’s and MarketWatch newsroom. They reflect the perspective and opinions of the authors.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
A five-bedroom Palo Alto home designed by Steven Ehrlich is listed for $44 million, making it the city’s most expensive listing. Built around a dramatic concrete spine, the home features four courtyards and a pool.
3 min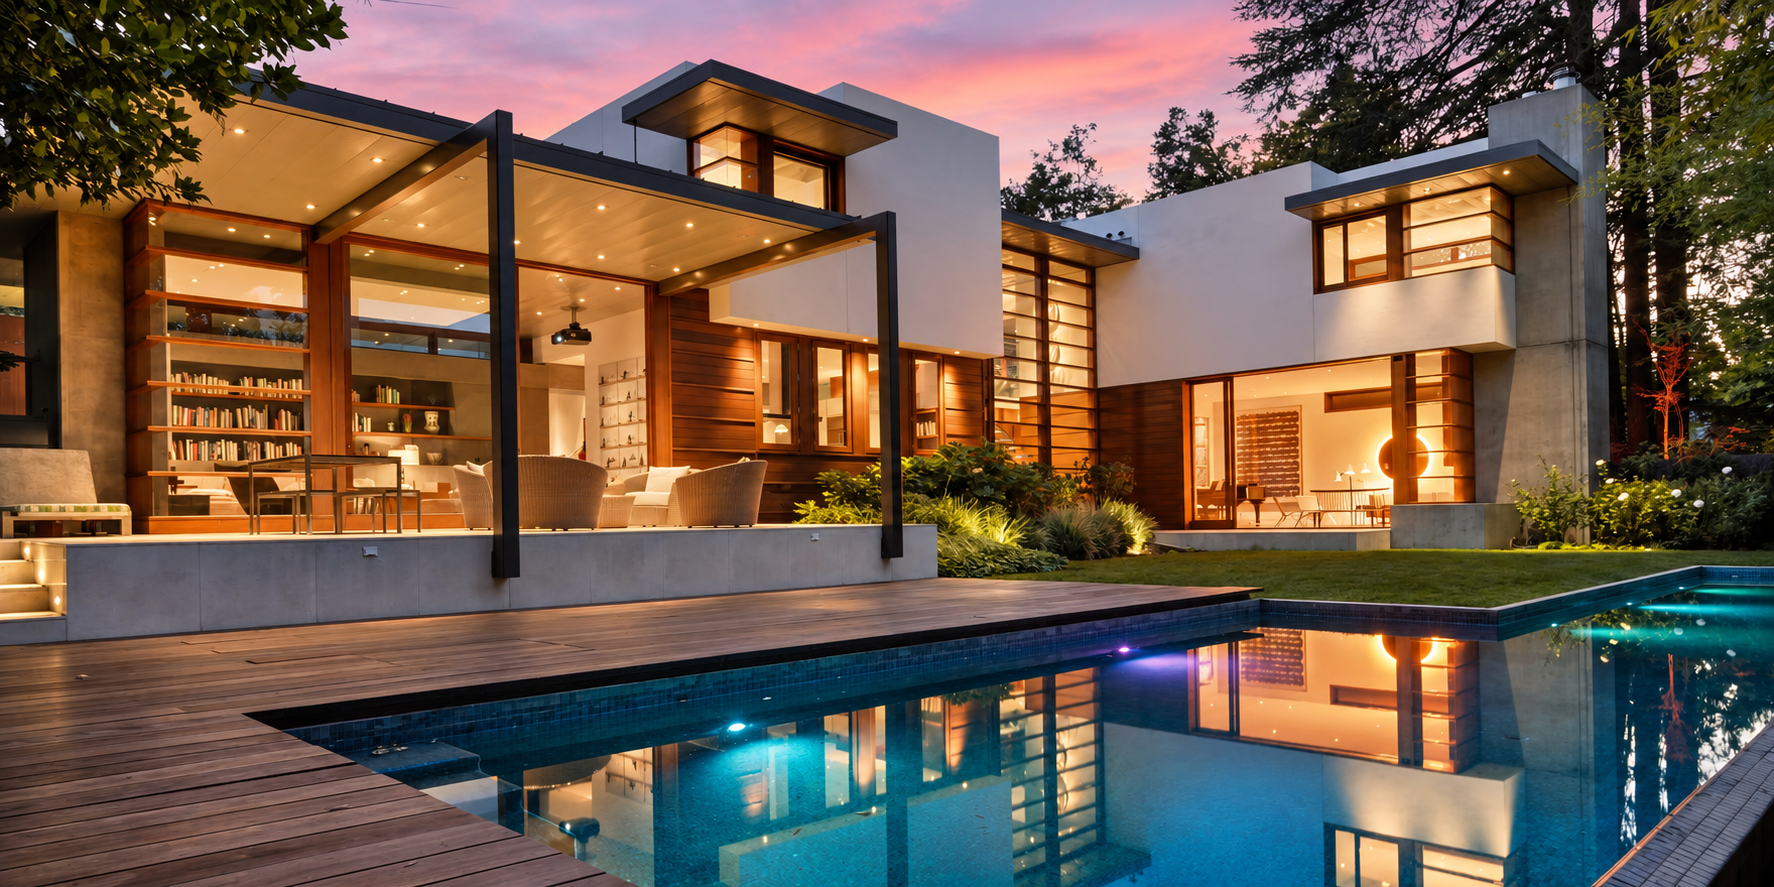
For years, tech entrepreneur Asher Waldfogel and his wife, Helyn MacLean, dreamed of building a modern house in Palo Alto, Calif.
The couple, however, worried about clashing with the Mediterranean-style architecture typically associated with their neighborhood of Old Palo Alto.
So they tapped architect Steven Ehrlich to create a design that paid homage to its surroundings with stucco, mahogany and titanium zinc cladding. They spent $20 million over several years building the house, completed in 2005.
Now looking to be closer to their adult daughter on the East Coast, they are putting the five-bedroom home on the market for $44 million—the most expensive listing in Palo Alto.
Waldfogel is an angel investor who co-founded Redback Networks, a telecommunications-equipment company. MacLean previously had a career in fundraising.
The couple purchased the roughly 0.4-acre site for $7.1 million in 2000 and demolished a circa-1930s Spanish Colonial home. The house they built pinwheels around a central staircase. It has 7,900 square feet of livable space, with four distinct courtyards and a pool.
A key feature of the home is a cast-in-place concrete wall, or spine, that is two stories high and about 80 feet long. “There’s a little bit of controlled chaos in what comes out of the form,” unlike a perfectly uniform surface, Waldfogel said. “If you want that, you do it in plastic.”
Waldfogel said he and his wife are thinking about the next phase of life now that their daughter is grown, although they have not decided where they will move. They also have a home in Sun Valley, Idaho.
“Right now we’re just trying to emotionally let go and decide what to do next,” he said.
Palo Alto, an epicenter of venture capital and tech startups in Silicon Valley, is home to some of the country’s biggest tech titans. Sales volume and prices are rising, with a median sale price of $3.5 million for the three months ending in August, up 5.8% year-over-year, according to real-estate brokerage Redfin.
Arthur Sharif of Sotheby’s International Realty—San Francisco Brokerage has the listing.


